This guide covers mortgage guidelines for buying a new house when starting a new job or facing an employment gap. Getting a new job does not mean you cannot buy a home. You do not have to work for the same employer for two years to qualify for a mortgage. Lenders mainly want to see that your income is steady, easy to verify, and likely to keep coming. Depending on your loan and situation, you could still qualify even if you changed jobs, returned to work after a break, just graduated, left the military, moved for work, or accepted a job that has not started yet. Each loan type, such as conventional, FHA, VA, or USDA, has its own rules. It is important to know which ones fit your situation.
In summary, you can buy a home with a new job or after a break from work. There is no rule that says you must be with the same employer for two years. Lenders look at your full work history, current income, how you are paid, any gaps, and whether your income will continue. Fannie Mae, Freddie Mac, VA, and USDA even offer options for buyers starting new jobs right before closing.
Can You Buy a House With a New Job?
Yes, it is often possible to obtain a mortgage shortly after starting new employment. What matters most is not just how long you have worked for your current employer. Lenders assess whether the applicant’s income is stable and well-documented. For instance, if a registered nurse spent four years at one hospital and just moved to another, they typically do not have to wait two more years at the new job just because they switched employers.
Case Scenario of Buying House With New Job After College Graduation
A recent graduate stepping into their first job can also qualify, even without a classic two-year work history. Fannie Mae requires lenders to evaluate whether the borrower has demonstrated a reliable employment pattern over the past 2 years.
Its current Selling Guide states that, for example, if a registered nurse worked at one hospital for four years and just started at a new hospital, they usually don’t have to stay at the new job for two years just because they switched employers.
Recent graduates can also qualify for a mortgage even without a typical two-year work history. Lenders usually review your work and income from the past two years to see how steady your earnings are. This work history can include time with different employers, not just one. Depending on your loan and situation, education, training, military service, and past jobs can also count as part of your work history. Changing jobs does not mean you have to start a new two-year period.
What Mortgage Underwriters Really Look For
Mortgage Underwriters Focus on a Few Key Questions:
- Is the borrower currently earning enough qualifying income?
- Can that income be documented?
- Is the income stable?
- Does the borrower’s employment history support the amount being used?
- Is there a reasonable expectation that the income will continue?
- In many cases, a new job can meet all these requirements.
Things can get more complicated if you switch from a steady salary to commission, self-employment, 1099 work, changing hours, bonuses, overtime, or other types of income that change from month to month.
How Employment Gaps Affect Mortgage Approval
Having a gap in your work history does not automatically stop you from getting a mortgage. Lenders usually check how long the gap lasted, when it happened, your jobs before and after, and what kind of income you have. Someone out of work for three months but now in a steady salaried job is viewed differently than someone who has left and returned to work many times. Your overall work history matters.
A Short Break Between Jobs is Usually Easier to Explain Than a Long Time Away From Work
You May Need to Tell the Lender Why Your Last Job Ended and When Your New Job Began
Common reasons include layoffs, moving, family needs, going back to school, military transitions, company closures, or planned career shifts. No universal employment gap waiting period applies to every mortgage program.
Extended Employment Gaps
- Lenders look more closely at longer breaks from work.
- FHA has one of the clearest agency rules for an extended employment absence.
- Under FHA rules, if the borrower has a work gap of six months or more, current income can be counted if they have been in the same type of work for at least six months as of the case start date, and the lender can show a two-year work history before the break.
- The lender must review the full work history and decide if the income is steady and reliable.
Returning to the Workforce
- Being away from work for a long time does not always mean you cannot get a mortgage.
- Parents returning after raising kids, people returning after an illness, recent grads, or anyone with a good reason for a long break may still qualify if they meet the loan’s terms.
- The guidance recognizes borrowers re-entering the workforce and allows it if the applicant has been with the current employer for at least 6 months and has a prior work history.
- Rules: Each loan program has its own rules, so do not assume FHA guidelines work for conventional, VA, or USDA loans.n You
Get a Mortgage With Less Than Two Years of Employment?
Yes, you can. Two years matter in mortgage approval, but it is not always a strict rule. FHA says a shorter work history can be okay if there are good reasons to offset it. Borrowers with less than two years of primary employment may still qualify if the lender can demonstrate that the employment is stable. Freddie Mac specifically gives examples involving someone returning to the workforce after an extended absence and someone who recently attended school or a training program before entering current employment.
Recent College and Trade-School Graduates
If you just graduated, you usually do not need two years of work experience to get a mortgage, as long as you were in school before. Time spent in school or training can help fill gaps in your work history.
Lenders may request transcripts, diplomas, training records, employment contracts, pay information, or other supporting documents.
If your education relates to your new career, it can help demonstrate that your job is stable, but it does not have to be a perfect match.
Starting a New Career
Changing careers does not automatically stop you from getting a mortgage. If you start working in a new field, lenders may look more closely at your qualifications and the stability of your new income. But you are allowed to change careers.
FHA requires additional analysis when a borrower changes employers more than three times during the previous 12 months or changes lines of work.
The lender may need education or training documentation demonstrating qualifications for the new position or employment documentation showing increasing income or benefits. VA also directs lenders to analyze frequent employment changes and gives favorable consideration to changes made for career advancement in the same or a related field.
Can You Buy a House With a Job Offer Letter?
In some cases, you can. This is especially relevant for borrowers relocating for a new job, graduating, transitioning from military service, or moving before receiving their first paycheck from a new employer. However, the rules for job offer letters vary by mortgage program. Do not assume that a job offer letter accepted by one loan program will be accepted by another.
Fannie Mae Mortgage With a New Job Offer
Fannie Mae allows qualifying with certain employment offers or contracts. Its current rules include an option allowing a borrower to close before obtaining a pay stub from the new employer. This option applies only to single-unit primary residences, and you must qualify based on fixed income.
Employment documentation must identify the employer and borrower, state the position, type and rate of pay, and include the start date. For the option without a pay stub before closing, you must also show extra financial resources.
This might mean having six months of housing costs saved or enough money to cover monthly payments until your job starts, plus one more month. Fannie Mae permits an applicable employment start date up to 90 days after the note date under its employment-offer provisions. This can be very helpful for people moving for a salaried job who want to buy a home before they start work.
Freddie Mac Mortgage With Future Employment
Freddie Mac also permits qualifying income that starts after the mortgage note date under specific conditions. The new job usually must be your main job with steady salary or hourly pay. For hourly jobs, you need a guaranteed minimum number of hours each week. Under one Freddie Mac option, the new job can begin up to 90 days after the note date.
Freddie Mac also allows qualifying income if employment begins before loan delivery and can be verified with acceptable documentation.
The borrower must also have sufficient additional funds to cover the applicable housing expense and monthly liabilities during the period before the income begins, plus an additional month, subject to the detailed calculation in the Freddie Mac Guide.
VA Loans and New Employment Offers
VA rules can also apply to borrowers employed for less than 12 months if the facts show the job is steady and reliable. VA instructs the lender to consider whether prior employment, education, or training provided skills that relate to the borrower’s current position. The VA Lenders Handbook also recognizes that a borrower may have a verifiable employment offer that begins on or after the anticipated closing date, even if a pay stub may not yet be available. This makes VA loans especially helpful for eligible veterans and service members who are moving for work.
USDA Loans and Employment Offer Letters
USDA Guaranteed Loans also have options for borrowers who are about to start a new job. USDA guidance states that a borrower with less than a two-year employment history may be considered when documentation shows that the applicant was attending school or a training program immediately before current employment.
For applicants about to start a new job, USDA allows using a firm job offer that starts within 60 days of closing, if proper documents and savings are shown.
USDA’s income guidance also recognizes a combination of employment, education, or military service when establishing the required history for certain employment-offer income.
What About FHA and a Future Job Offer?
Do not assume that the rules for job offers with conventional loans also apply to FHA loans. FHA underwriting focuses on income that meets HUD’s definition of effective income and contains specific rules for employment history, gaps, current employment, and employment verification. The current FHA Handbook also contains defined requirements when an extended gap of six months or more has occurred. Because situations vary depending on the start date, the length of any work gap, and the pay type, FHA borrowers moving for a job should have their employment verified before signing a contract contingent on a future job offer.
New Job? Employment Gaps? We Can Help You Buy a Home!
Reach out now to discuss how we can help you secure financing for your new home.Conventional Loan Employment Guidelines With a New Job
Conventional loans are mortgages that follow rules set by Fannie Mae or Freddie Mac. Their rules are similar in many ways, but not exactly the same.
Fannie Mae Employment History Guidelines
Fannie Mae requires the lender to review the borrower’s work history to determine whether it represents a reliable pattern over the most recent two years. This does not mean you must have two years with your current employer. A shorter work history can be enough if you have other strengths. People who change jobs can often still have steady income if their pay stays consistent and predictable.
Freddie Mac Employment History Guidelines
Freddie Mac states that, in most cases, borrowers should have at least a two-year history of primary employment. However, when the history is shorter, the lender can determine that the employment is stable based on the borrower’s circumstances, income characteristics, prior employment, education, training, and overall ability to repay.
Freddie Mac specifically recognizes borrowers returning to the workforce and borrowers entering employment after school or training as examples in which less than 2 years may be supportable.
The main idea is that two years of work history does not have to mean two years with the same employer. FHA loans can be suitable for borrowers. FHA loans can work well for people who have recently changed jobs, as long as HUD rules are followed properly.to remain with the same employer for 2 years.
Income and Employment Mortgage Guidelines
Employment and income is one of the most important factors in qualifying and getting approved for a mortgage. Lenders look at your job income and how steady it is.
If you have been out of work for six months or more, special rules apply. These apply when you have at least six months in the same type of work when the case starts, and a two-year work history before the long break.
Do not confuse this rule with the mistaken idea that everyone with a job gap must wait six months. The six-month rule only applies to certain extended absences as defined by FHA guidelines.
Frequent Job Changes on FHA Loans
Switching jobs does not automatically disqualify you. However, if a borrower has changed employers more than three times during the previous 12 months or has changed lines of work, FHA requires additional analysis of employment stability. Certain fields where workers often move among employers, such as some temporary and union trades, may be treated differently under HUD guidance.
VA Underwriters Check if Your Income is Steady, Reliable, and Enough When They Review Your Full Financial Situation
The VA will not deny you just because you have been at your current job for less than a year. When employment is less than 12 months, the lender may determine that the income is stable if the borrower’s prior employment, training, or education supports the new position and the probability of continued employment is strong. The reason you changed jobs recently also matters. VA tells lenders to give favorable consideration to career advancement in the same or a related field while taking a closer look at job changes with no apparent improvement or changes into an unrelated occupation. For eligible borrowers, your whole career story counts more than just how long you have been at your current job.oyer.
USDA Employment Guidelines With a New Job
USDA Guaranteed Loans require lenders to make sure your income for repaying the loan is steady and reliable. Federal USDA regulations require the lender to examine the applicant’s past income record for at least the previous two years, along with applicable education or training, and to establish the anticipated income and likelihood of continuance.
USDA does not have a one-size-fits-all rule for employment gaps. Lenders look at your full work history.
USDA also recognizes newly employed borrowers, people re-entering the workforce, education or training before employment, and certain future employment contracts. This is yet another reason not to assume one loan’s employment gap rules fit every mortgage program.
How a New Job Changes the Income Used to Qualify
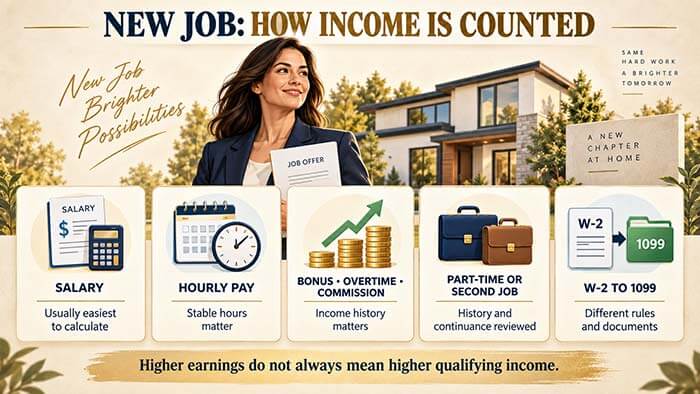
- Starting a new job is just one part of the process.
- How you are paid can be just as important.
- Two people starting new jobs on the same day might be treated very differently if one has a fixed salary and the other relies on commission or changing hours.
Fixed Salary or Fixed Base Pay
Fixed-base income is usually easier for lenders to calculate because they know exactly what you are expected to earn each pay period. For example, a verified annual salary can usually be converted to monthly qualifying income by dividing by 12, subject to the program’s verification requirements. Fixed-base pay is also the most commonly used for future employment options with conventional loans.
Hourly Income
Hourly pay is judged by whether your hours are steady or change from week to week. A guaranteed 40-hour week is very different from a schedule that varies between 20 and 45 hours. Fannie Mae’s current guidance requires at least a 12-month history for variable base income. Freddie Mac similarly distinguishes stable non-fluctuating earnings from fluctuating income.
Bonus, Overtime, Commission, and Tip Income
A common mortgage myth is that bonus, commission, overtime, or tip income cannot be used unless you have received it for two full years. In reality, the rules are more flexible than many people think.
For Fannie Mae loans, a two-year history of bonus, commission, overtime, and tip income is recommended, but income received for at least 12 months may be acceptable when positive factors reasonably offset the shorter history.
Other programs have their own rules. Lenders also look at whether your income is going up, staying steady, dropping, unpredictable, or likely to keep coming. For example, if you start a new job with a $60,000 base salary and expect a $30,000 bonus, do not assume all $90,000 will count right away for mortgage qualification. Bonus pay may be treated differently during underwriting.
Part-Time or Second-Job Income
Part-time work can count toward your qualifying income. The main question is whether you have enough history to show your part-time income is steady and will continue. Fannie Mae prefers to see two years of income from multiple jobs, but may accept just 12 months if you have other strengths. This means part-time income can count.
Switching From W-2 Employment to Self-Employment or 1099 Income
Moving from a W-2 job to self-employment or 1099 work is a big change, so talk with your lender before making the switch. If you earn $100,000 as a W-2 employee and then start a business earning the same, you might not qualify right away with your new income. Self-employment has its own history, documentation, tax returns, business stability, and income-calculation requirements. The same goes if you switch from a steady salary to commission-based or independent-contractor pay. Earning more on paper does not always mean you can use the full amount to qualify for a mortgage.
Documents You May Need When Buying a House

The paperwork you need depends on your loan type and how you are paid. Lenders might ask for recent paystubs, W-2s, proof of employment, a signed job offer or contract, information from past employers, tax returns, school records, training certificates, and a short note explaining any job gaps. They may also check your job status again right before closing.
For example, Fannie Mae generally requires verbal verification of employment income within 10 business days before the note date, subject to its permitted alternatives.
The purpose is to confirm that the borrower remains employed before the mortgage. Since your job can be rechecked late in the game, let your loan officer know right away if anything changes with your employer, pay, hours, leave, or compensation.
Common New-Job Problems That Can Delay a Mortgage
The most difficult new-job mortgage cases are not always about the job change itself. Problems often come up when new job details are not checked early. You may think your new compensation is a guaranteed salary, but part of it is actually a bonus. Your offer letter might have conditions you have not yet fulfilled. Keith Richardson, NMLS 165137, President of Coast 2 Coast Mortgage Lending says the following about common delays in mortgage closings due to a new job. The start date may be outside the timeframe allowed by your choice.
You might switch from a W-2 job to 1099 contract work right before closing. Variable hourly pay might be counted as if you always work 40 hours, even if your schedule actually changes.
A recent grad might forget to provide transcripts or proof connecting their education and training to their job history. My employment history. Another common pitfall is changing jobs after getting preapproved and thinking your approval still stands. Preapproval relies on your exact income and job details. If anything changes, your lender might have to recalculate, redo underwriting, ask for new paperwork, or even switch your loan program. If you can, have your new employment reviewed before you give notice to your current employer.
Lender Overlays Can Affect Borrowers
With agency rules, a lender’s own requirements do not always align. the same. Fannie Mae, Freddie Mac, FHA, VA, and USDA establish the underlying requirements for their respective mortgage programs. A lender might add extra rules on top of the agency’s minimum standards additional requirements are commonly called lender overlays. For example, agency guidelines may allow a shorter employment history, but a lender may require more documentation or a longer history in line with its risk policies. That difference can have a big impact. If you are applying for a new job or employment gap, you may still qualify under the mortgage program’s guidelines.
Agency Mortgage Guidelines vs Lender Overlays
Meeting agency guidelines is not a sure ticket to approval. You still have to meet credit, debt, asset, property, underwriting, and lender-specific requirements. Examples for Borrowers With New Employment. Take a nurse who spent five years at one hospital, then took a better-paying salaried job at another.
There is no blanket rule forcing the nurse to wait two years before applying for a mortgage. The lender will review the new job and income under the appropriate program.
Consider a college student or picture a college grad who just finished four years of school and landed a salaried accounting job that starts soon after closing loan program and documentation, this borrower may qualify even without two years of traditional employment.
Case Scenario Where Borrower Had Extended Employment Gap
A third scenario: someone who was out of work for three years and just started a new job requires a different analysis. If using FHA financing and the absence is considered an extended employment gap, the FHA six-month current employment requirement applies. A fourth example: a borrower who spent ten years as a salaried employee, then left a month before buying a house to launch a consulting business. This borrower could face tougher hurdles, even if the new business is set to earn more, because self-employment income is subject to different mortgage rules. The details of your job situation matter much more than simply having a new job.
How to Improve Your Chances of Mortgage Approval After Changing Jobs
Talk to your loan officer before making any job changes while you are buying a home. Share your full work history and do not leave anything out. Send your actual offer letter or job contract to your lender as soon as you can. Make sure your lender knows if you are paid by salary, hourly, commission, overtime, bonus, tips, 1099 income, or a mix. Keep enough money on hand for closing costs and reserves, especially if you are using a future-employment option that requires additional funds. Hold off on new debt while your lender reviews your recent job change. Most importantly, let your loan officer help you find the mortgage program that fits your job situation, instead of trying to fit into one with rules that do not work for your income.
How Long Must You Be on Your Job Buying House With New Job
Save for a larger down payment. A higher down payment can compensate for a less-than-ideal employment history and improve your loan-to-value ratio. Buying house with new job with no prior employment experience is possible right after graduation with a solid offer employment letter by the employer.
How Gustan Cho Associates Reviews New Job and Employment Gap Files
Borrowers with recent job changes or gaps are often told to wait just because they have not spent two years with the same employer. is not always the correct answer. First, figure out your income type, work history, how long any gaps lasted, your new job’s start date, how you are paid, and which loan program you want.
A recent job change should be reviewed carefully rather than automatically denied. If you have been told you do not qualify because of a new job, short work history, career change, or job gap, have your entire file reviewed under the actual rules for your loan program.
The file can then be reviewed under the applicable Fannie Mae, Freddie Mac, FHA, VA, USDA, or alternative mortgage guidelines. If you cannot qualify right now, your next steps should be clear and specific. Instead of just hearing, “You need more job history,” you should know exactly what is needed, such as working a certain amount of time, getting your first paystub, showing past work, meeting an offer letter condition, or building enough history for variable income. This way, you get a clear, step-by-step path to mortgage approval.
Final Thoughts on Buying a House With a New Job or Employment Gap
You can buy a house with a new job, and changing employers does not automatically restart a two-year waiting period for a mortgage. Lenders mainly want to see that your income is documented, steady, and likely to continue.
You might qualify after changing jobs, coming back to work, graduating, moving for a job, leaving the military, or accepting a job that starts soon. The right answer depends on your specific mortgage program.
Fannie Mae and Freddie Mac allow shorter employment histories in appropriate circumstances and have detailed provisions for certain future employment income. VA permits lenders to consider employment lasting less than 12 months when the facts support stability and to recognize verifiable future job offers. USDA provides flexibility for education, re-entering the workforce, and certain employment contracts. FHA has its own rules, including a defined standard for employment gaps lasting six months or more.
How To Start the Mortgage Loan Application Process
For more information about the content in this guide or other mortgage topics, please contact us at Gustan Cho Associates at 800-900-8569 or text us for a faster response. Or email us at gcho@gustancho.com. Gustan Cho Associates is a national mortgage company licensed in multiple states with no lender overlays on government and conventional loans. We also offer W-2 income only mortgages and bank statement mortgage for self-employed borrowers with no income tax returns required.
FAQ: Buying House With New Job and Employment Gaps
Can I Buy a House with a New Job and Gaps in My Employment History?
Yes, purchasing a home is possible even if you’ve recently started a new job or have employment gaps. Lenders consider various factors beyond just employment history when assessing mortgage applications.
Do I Need to Have Been in the Same Job for the Past Two Years to Qualify for a Mortgage?
Although lenders prefer a stable employment history, it is not mandatory. Multiple jobs or employment gaps only qualify you if you meet other requirements.
How Important are Income and Employment When Qualifying for a Mortgage?
Income and employment are crucial factors determining your ability to repay the mortgage. To determine eligibility, lenders assess your income stability, credit history, and overall financial situation.
What Documents Do I Need to Provide to Prove My Income?
You’ll typically need to provide recent pay stubs, W-2 forms, and additional documentation if you’re self-employed or have irregular income.
How Can I Improve My Chances of Getting Approved for Mortgage with New Job or Employment Gaps?
Maintain good credit, explain employment gaps, show job stability, and consult an advisor for guidance.
How Long Do I Need to be in My Current Job Before Buying House with New Job?
While longer job tenure is viewed favorably, buying a house with a new job offer letter is possible, especially if you’re a recent graduate or have prior full-time education.
What Are the Guidelines for Different Types of Loan Programs Regarding Employment History?
Each loan program (Conventional, FHA, VA, USDA) has specific requirements regarding employment history, but generally, full-time education can count towards prior employment history, and job offer letters may be accepted.
How is income calculated for different types of earners (hourly, salaried, commission, self-employed)?
Income calculation methods vary based on the type of employment. For example, income is typically calculated by dividing the annual salary by 12 months, while self-employed borrowers may need to provide two years of tax returns for income verification.
Can I Qualify for a Mortgage with a Bonus, Overtime, or Commission Income?
Yes, bonus, overtime, and commission income can be used for qualification purposes. Still, lenders typically require a two-year history of earning such income.
What if I Have Gaps in My Employment History? How Do I Handle Them?
It’s important to be ready to explain any employment gaps, including relevant details such as medical leave, family responsibilities, or education. Showing stability in your current job and maintaining strong financials can also help offset concerns over employment gaps.
For further assistance or inquiries about mortgage options, contact Gustan Cho Associates, NMLS 2885337, a DBA of Coast 2 Coast Mortgage Lending, LLC, NMLS 376205, at 800-900-8569 or email gcho@gustancho.com. Text us at 262-627-1965l Our team at Gustan Cho Associates are specializes in various loan programs and can provide personalized guidance based on your needs. This Guide About Buying House With New Job and Employment Gaps Was Updated on September 4, 2026.