
A debt-to-income ratio mortgage calculator estimates the percentage of your qualifying monthly income needed for housing and recurring debt payments. It calculates your front-end DTI, which measures housing expenses, and your back-end DTI, which includes housing plus other qualifying monthly debts. Enter your qualifying monthly income, the full proposed housing payment—including principal, interest, property taxes, homeowners insurance, applicable mortgage insurance, and HOA dues—and the monthly payments necessary for debts like credit cards, car loans, and student loans. The results provide an estimate of your mortgage DTI. Acceptable ratios depend on the mortgage program, underwriting requirements, and overall application. The calculator does not establish an approved loan amount or guarantee mortgage approval.
- Conv
- FHA
- VA
- Jum/Non
- USDA
Debt-to-Income Ratio Mortgage Calculator
A debt-to-income ratio mortgage calculator compares your qualifying monthly income with your proposed housing payment and recurring monthly debts. The result is usually shown as two percentages:
- Front-end DTI — housing expenses compared with qualifying income.
- Back-end DTI — housing expenses plus other monthly debts compared with qualifying income.
Mortgage lenders use these ratios as part of the underwriting process, but the acceptable DTI depends on the loan program and overall file.
How to Use the Debt-to-Income Ratio Mortgage Calculator
Use the mortgage payment calculator first to estimate your total monthly housing expense. Then use that amount in the separate DTI calculator with your qualifying income and other monthly debt payments.
Step 1: Calculate Your Monthly Housing Payment
Select the applicable loan program and enter the home price or value, down payment or equity, interest rate, and loan term. Enter property taxes and homeowners insurance as annual amounts in the fields labeled yearly. Enter HOA dues and applicable mortgage insurance as monthly amounts where requested. Review the estimated total monthly payment. Confirm that it includes the applicable housing costs and add any required expenses the payment calculator does not capture.
Step 2: Enter the Housing Payment in the DTI Calculator
Use the full monthly housing expense in the separate DTI calculator’s “Monthly Mortgage Payment” field. If that field is already populated, verify that the amount matches your estimated total housing expense. Otherwise, transfer the amount manually. Using only principal and interest would understate your housing expense.
Step 3: Add Your Other Monthly Debt Payments
Enter the total required monthly payments for all applicable obligations (i.e., auto loans, credit card minimums, student loans, and child support). Use the monthly payment amounts rather than the outstanding balances. Don’t include the proposed housing payment in this field again.
Step 4: Enter Qualifying Income and Review Your Results
Use the income that the lender will accept for qualification purposes. Match that amount to the monthly or annual income field in the calculator. Check the estimated front-end and back-end ratios. If you alter the property, the financing terms, the income, or the debt service, you’ll need to update the relevant inputs and recalculate.
How to Calculate Front-End and Back-End DTI
Both DTI ratios compare monthly obligations with qualifying monthly income. The difference is whether you count housing expenses alone or housing plus other qualifying debts.
Front-End DTI: Your Housing Ratio
Front-end DTI measures the percentage of qualifying monthly income required to cover the full proposed housing payment. Front-end DTI = (Monthly housing expense ÷ Qualifying monthly income) × 100 Use the total qualifying housing expense, including applicable taxes, insurance, mortgage insurance, and association dues.
Back-End DTI: Your Total Debt Ratio
Back-end DTI measures the percentage of qualifying monthly income needed to cover housing and other required monthly debt payments, such as auto loans, student loans, and credit card minimum payments. Back-end DTI = [(Monthly housing expense + Other qualifying monthly debt payments) ÷ Qualifying monthly income] × 100 Count the housing payment once, then add the other monthly obligations required by the mortgage program.
Worked Example: Calculating Both Ratios
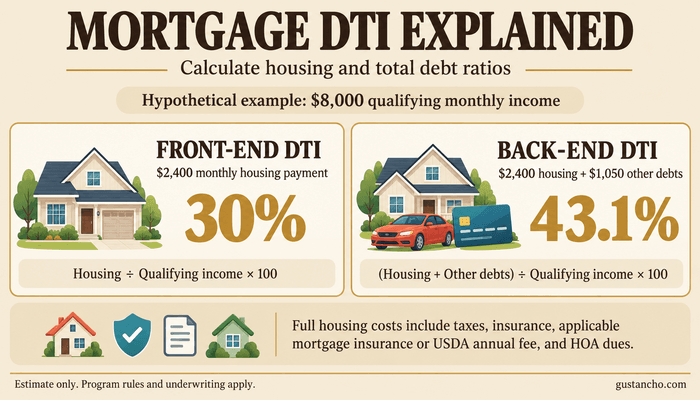
Assume a borrower has $8,000 in qualifying monthly income, a $2,400 full monthly housing payment, and $1,050 in other qualifying monthly debt payments. The front-end calculation is ($2,400 ÷ $8,000) × 100 = 30%. The back-end calculation is [($2,400 + $1,050) ÷ $8,000] × 100 = 43.125%, or approximately 43.1%. This borrower’s housing expense uses 30% of qualifying income, while housing and other qualifying debts together use approximately 43.1%. Whether those ratios are acceptable depends on the loan program and underwriting requirements.
What to Include in Your Monthly Housing Payment
Your qualifying housing expense includes more than the mortgage’s principal and interest. PITI stands for principal, interest, taxes, and insurance, but additional property-related obligations may also count. Include applicable expenses even when you pay them separately from the mortgage.
Principal, Interest, and Subordinate Financing
Start with the first mortgage payment required for qualification. Include the applicable qualifying payment on a second mortgage or HELOC secured by the property. The lender must review the subordinate loan’s terms to determine its treatment, including any payment deferral. Count each required payment once; do not add it again under other monthly debts if it is already included in housing expenses.
Property Taxes and Insurance
Include the property-tax amount expected to apply to the home. A seller’s existing tax bill may not reflect taxes after a purchase, reassessment, or completion of new construction. Include homeowners insurance, flood insurance when required, and other applicable supplemental property insurance. Use property-specific estimates and insurance quotes when available.
Mortgage Insurance and USDA Annual Fees
Include applicable monthly FHA mortgage insurance premiums or conventional private mortgage insurance. For a USDA-guaranteed loan, include the monthly amount attributable to the annual guarantee fee when applicable. USDA expressly includes this expense in its housing-payment calculation.
HOA Dues and Other Required Charges
Add applicable homeowners association or condominium dues. Other qualifying housing expenses may include ground rent, cooperative fees, and required property assessments. These charges can affect qualification even when they are collected separately from the mortgage payment.
Converting Annual Expenses to Monthly Amounts
When calculating DTI manually, divide annual expenses by 12 to determine their monthly amounts. For example: $7,200 in annual property taxes ÷ 12 = $600 per month That $600 counts toward the qualifying housing expense. When using the calculator, follow each field’s stated billing period. Enter annual figures in fields labeled “yearly” so you do not double-count the same expense.
What Counts as the Monthly Housing Payment?
For mortgage qualification, the housing payment is more than principal and interest. Depending on the property and loan, the lender may include:
- Principal and interest.
- Property taxes.
- Homeowners insurance.
- Flood insurance is required.
- FHA mortgage insurance or conventional PMI when applicable.
- HOA or condominium dues.
- Other required property-related assessments.
Use the estimated total housing expense when entering numbers into a debt-to-income ratio mortgage calculator. Using only principal and interest will understate the actual DTI.
PITI, Mortgage Insurance, and HOA Dues
 PITI stands for: Principal + Interest + Taxes + Insurance Mortgage insurance and HOA dues are separate expenses, but they can still be included in the monthly housing payment for mortgage qualification.
FHA Mortgage Insurance
FHA loans generally include a monthly mortgage insurance premium, or MIP, which must be included in the housing expense.
Conventional Mortgage Insurance
A conventional loan with a higher loan-to-value ratio may require private mortgage insurance, or PMI. If PMI is required, the monthly premium is included in the calculation of the qualifying housing payment.
HOA and Condominium Dues
HOA and condominium association dues are also included when applicable. A borrower with a $2,000 PITI payment and $350 monthly HOA dues does not have a $2,000 qualifying housing expense. The HOA payment must also be considered.
What Monthly Debt Payments Should You Enter?
Enter the required monthly payments for debts counted by the mortgage program. A credit card with a $5,000 balance requires a minimum monthly payment of $125. This means you have a $125 obligation each month, according to the lending guidelines.
Common entries include auto and personal loans, credit card minimum payments, qualifying student loan payments, vehicle leases, and applicable support obligations or tax payment agreements. Count each payment once, including any obligations already included in your housing expense.
Disclose debts even when they do not appear on your credit report. Provide current statements, repayment agreements, court orders, or other records so the lender can determine the qualifying payment.
When Can a Debt Be Excluded From DTI?
An exclusion is program-specific and will depend on the supporting documentation. A family member paying the account, a business paying the account, or an account that is approaching payoff will not, in itself, make the obligation eligible for exclusion. For debts paid by someone else, you’ll need to provide the payment history and any supporting documentation required by the program. For obligations paid by the business, provide the business payment records and the documentation that shows how the expense was accounted for in the business income analysis.
Few Remaining Payments Do Not Guarantee Exclusion
Under Fannie Mae rules, an installment debt which is approaching payoff may still be included if the payment has a material effect on repayment ability. Lease payments are generally included regardless of how many payments remain. Do not apply an installment loan exception to a vehicle lease.
Confirm the Benefit Before Paying Off Debt
If a debt must be paid off to qualify, the lender will have to verify the payoff and the applicable source-of-funds requirements. Before you use any cash, make sure that removing the payment will, in fact, improve your qualification and that you’ll have sufficient funds available for closing and reserves. Hold the payment in your original estimate until the lender confirms that a documented exclusion is in place.
What Income Should You Enter in the DTI Calculator?
Enter the income the lender expects to use for qualification, converted to a monthly amount. This may differ from your latest paycheck, total earnings, or bank deposits.
Regular Salary and Hourly Wages
For a fixed salary or hourly rate with a set number of qualifying hours, the lender will generally look at your documented gross income (before tax and payroll deductions). Where you have hourly employment with variable hours, the lender may require you to average your income rather than use the most recent pay statement.
Variable Income
Overtime, bonuses, commissions, tips, and other variable income will require a review of the payment history and income trend. The lender may elect to average the eligible income or use a lower stabilized amount where income has declined. An exceptionally good month does not, in itself, establish the amount available for qualification.
Self-Employment Income
Business revenue and bank deposits are not in themselves qualifying income. The lender will review the relevant business records, expenses, cash flow, and allowable adjustments to determine the income available under the chosen mortgage program. You enter that qualifying amount rather than the total business receipts. There is no requirement to have two full years of income from every source. The required history and documentation will vary depending on the income source, the mortgage program, and your individual circumstances. Always confirm the qualifying amount before relying on the calculator’s results.
Mortgage DTI Guidelines by Loan Program
Mortgage programs evaluate DTI differently. Some use published housing and total-debt ratios, while others rely more heavily on automated underwriting and the borrower’s overall financial profile. When two ratios appear together, the first represents housing expenses and the second represents total qualifying monthly obligations.
FHA DTI Guidelines
Automated underwriting: Most FHA forward mortgages are evaluated through the FHA TOTAL Mortgage Scorecard within an automated underwriting system. TOTAL assesses the submitted application and returns an Accept or Refer classification. The manual-underwriting ratios below should not be presented as universal limits for every automated FHA file. Manual underwriting: FHA ties higher qualifying ratios to specific credit score and compensating factor requirements. For borrowers with a minimum decision credit score of 580 or higher, the following tiers apply. The first number is the housing ratio; the second is total DTI. 31/43: No compensating factor required. This is the standard starting point, although all other manual-underwriting requirements still apply. 37/47: One permitted compensating factor. The borrower must document qualifying cash reserves, a minimal increase in housing expense, or qualifying residual income. Significant additional income excluded from effective income is not a standalone compensating factor for this tier. 40/40: HUD’s no-discretionary-debt provision. Other than housing, the borrower must not have any outstanding balances that are carried month to month. All credit accounts in the borrower’s name must have been open for at least 6 months and must be supported by documentation showing that the account was paid in full each month for the previous 6 months. Having very little debt or no credit history at all does not automatically satisfy this requirement. 40/50: Two permitted compensating factors. Eligible compensating factors are qualifying cash reserves, a modest increase in housing expenses, qualifying residual income, and a significant amount of additional income not included in effective income. Each factor must meet HUD’s requirements. Additional income may be used as one of the two factors provided it is properly documented. Borrowers with scores in the 500-579 range or with no credit score are generally restricted to 31/43; normal compensating factors won’t get them into the higher tiers. HUD’s own provisions for qualifying energy-efficient homes can allow for 33/45 (including for otherwise-eligible lower-score/no-score borrowers). The lender must have the property certified as meeting those requirements.
VA DTI Guidelines
VA uses a 41% total DTI benchmark and places substantial importance on residual income—the amount remaining after specified taxes, debts, and shelter expenses. Manual underwriting: A ratio above 41% requires closer evaluation under VA’s guidelines. Tax-free income and residual income exceeding the applicable standard can affect the additional review requirements. Automated underwriting: The lender follows the applicable AUS findings and VA requirements, including residual-income analysis. VA does not use the same front-end-to-back-end ratio matrix as FHA manual underwriting.
USDA DTI Guidelines
USDA’s standard benchmarks are 29% for housing expenses and 41% for total debt. GUS Accept files: Applications receiving an Accept or Accept Full Documentation recommendation do not require a separate debt-ratio waiver simply because their ratios exceed 29/41. Purchase files requiring a waiver: For GUS Refer, Refer with Caution, and manually underwritten purchase files without GUS assistance, USDA may approve a documented waiver allowing ratios up to 32% housing and 44% total debt. That waiver requires a validated credit score of at least 680 for every applicant, at least one acceptable compensating factor, supporting documentation, and Agency approval. These conditions apply to this purchase-waiver route. USDA addresses refinance waivers separately.
Fannie Mae DTI Guidelines
Desktop Underwriter: Fannie Mae generally permits a maximum 50% total DTI for DU-underwritten loans. This is a total debt limit, rather than a universal 50% housing ratio limit. Manual underwriting: The standard maximum total DTI is 36%, with an increase to 45% available if the borrower meets the applicable credit score and reserve requirements. Certain transactions have additional requirements or exceptions, so the lender must apply the rules specific to the loan.
Freddie Mac DTI Guidelines
Loan Product Advisor (LPA): LPA calculates and evaluates qualifying ratios based on the submitted information. An Accept recommendation means LPA has found those ratios acceptable for that application. Manual underwriting: Freddie Mac uses a 36% total DTI guideline. A higher ratio requires documented justification, and a manually underwritten mortgage with a total DTI exceeding 45% is ineligible for sale to Freddie Mac.
How AUS Findings and Lender Overlays Affect These Guidelines
An AUS recommendation evaluates the information submitted; the lender must verify that information and satisfy the applicable borrower, property, and documentation requirements. Lenders may also impose additional restrictions, called overlays, such as a lower DTI ceiling. Changes to income, debts, or the qualifying housing payment may require updated underwriting. A calculator result alone does not establish mortgage approval.
Know Your Debt-to-Income Ratio Before You Apply
Use the mortgage calculator to estimate your front-end and back-end DTI, then explore how your income, monthly debts, and housing costs may affect mortgage qualification.How Property Taxes Affect DTI
Property taxes are part of the monthly housing expense used to calculate mortgage DTI. The lender generally converts the expected annual property tax obligation into a monthly amount and includes it in the mortgage payment. For example: That $600 counts toward the qualifying housing expense. $7,200 annual property taxes ÷ 12 = $600 per month
Higher Taxes Can Reduce Buying Power
Two homes with the same purchase price and mortgage amount can have different DTIs if their property taxes differ. This is especially important when comparing properties in different counties, municipalities, or tax districts. When using a debt-to-income ratio mortgage calculator, use a realistic property tax estimate for the property in question whenever possible.
How Homeowners Insurance Affects DTI
Homeowners insurance is also included in the monthly housing expense. If the annual homeowners’ insurance premium is $2,400: $2,400 ÷ 12 = $200 per month That monthly amount is added to the qualifying mortgage payment.
Additional Insurance Can Increase the Housing Payment
Depending on the property, the lender may also need to include other required insurance costs, such as flood insurance. A property with unusually high homeownership or flood insurance premiums can materially increase DTI even when the principal-and-interest payment remains the same. For that reason, borrowers should avoid using a generic insurance estimate once an actual quote is available.
How HOA Dues Affect DTI
Homeowners’ association and condominium dues are considered qualifying housing expenses when they apply to the property. For example, if the mortgage payment, including taxes and insurance, is $2,400 and the HOA dues are $300 per month, the lender generally evaluates a $2,700 monthly housing expense. HOA dues are not technically part of PITI, but they still affect both the housing ratio and total DTI.
Use the Actual HOA Amount When Available
A small difference in monthly HOA dues can change a borrower’s qualification who is already near the allowable DTI. Once a specific property has been identified, use the actual association dues instead of a general estimate.
How Student Loans Affect DTI
Student loans can significantly affect mortgage qualification, especially when the balance is large or the credit report shows a $0 payment. The payment used for DTI depends on the mortgage program.
FHA Student Loans
FHA includes outstanding student loans in the mortgage DTI, regardless of repayment status. The lender uses the reported or documented actual monthly payment when that amount is greater than zero. When the credit report shows a $0 monthly payment, FHA generally uses 0.5% of the outstanding balance. Lenders need written confirmation from the creditor or student loan servicer for any payment amount lower than what’s on the credit report. This confirmation must include the actual payment amount, payment status, outstanding balance, and loan terms. A borrower’s statement alone is not sufficient to verify a lower qualifying payment.
Fannie Mae Student Loans
Fannie Mae generally permits lenders to use the monthly student loan payment shown on the credit report. If that amount is incorrect, the lender may use the payment amount shown on the most recent student loan statement. A documented $0 payment under an income-driven repayment plan may be used as $0 for qualification. Deferred loans and loans in forbearance receive different treatment when no payment is reported, or the reported payment is $0. The lender may use either 1% of the outstanding balance or a fully amortizing payment calculated from documented repayment terms. A $0 entry on the credit report alone does not establish eligibility for exclusion of the payment.
Freddie Mac Student Loans
Freddie Mac typically uses the positive monthly payment amount indicated on the credit report for student loans in repayment, deferment, or forbearance. Acceptable documentation may support a different positive current payment. When the credit report shows a $0 payment, the lender generally uses 0.5% of the outstanding balance, unless acceptable documentation establishes a different current payment greater than zero.
Income-Driven Repayment: Recertification or Payment Changes
A separate rule applies when documentation shows that income recertification is required or that the payment will increase on or before the first due date of the mortgage payment. In that situation, the lender must use one of these qualifying-payment options:
- The higher of the current payment or 0.5% of the outstanding balance.
- A documented future payment that exceeds the current payment.
- An approved future payment equal to or below the current payment, provided the borrower has completed income recertification and the approved amount is greater than zero.
For your DTI estimate, use the payment supported by the applicable rule and documentation. Applying the greater-of calculation to every Freddie Mac student loan could overstate your monthly debt.
USDA Student Loans
Under USDA’s current Chapter 11 guidance, the lender uses the payment reported on the credit report or the documented actual payment when the amount is greater than zero. When the payment is $0, USDA uses 0.5% of the outstanding balance, supported by the credit report or creditor verification. This calculation applies regardless of the student loan’s payment status. Use the resulting qualifying payment in your DTI estimate rather than automatically entering zero for a deferred loan or a repayment plan with no current payment.
VA Student Loans
VA may exclude a student loan payment when written evidence establishes that repayment will remain deferred for at least 12 months after closing. For loans already in repayment or scheduled to enter repayment within 12 months of closing, the lender calculates a monthly threshold: Monthly threshold = (Outstanding student-loan balance × 5%) ÷ 12 If the credit-report payment exceeds that threshold, the lender must use the reported payment. A lower reported payment requires a statement from the student loan servicer that shows the actual loan terms and payment information. The document needs to be dated within 60 days before the closing date. A lower actual payment may be used when supported by the required documentation; borrowers should not assume either the threshold or their reported payment automatically controls. See the VA Lender’s Handbook, Chapter 4, Topic 5 for the applicable student-loan requirements.
Hypothetical Mortgage DTI Examples
This hypothetical comparison shows how property costs can change DTI while the loan amount, principal-and-interest payment, qualifying income, and other debts remain unchanged. Assume the borrower has $9,000 in qualifying monthly income and $1,080 in other qualifying monthly debts: a $600 auto payment, $300 student-loan payment, and $180 in credit-card minimum payments.
First Property: 42% Back-End DTI
The first property has a total monthly housing expense of $2,700. Adding the borrower’s other debts produces $3,780 in total monthly obligations. ($3,780 ÷ $9,000) × 100 = 42% back-end DTI
Second Property: Approximately 50.3% Back-End DTI
The second property costs an additional $250 per month in property taxes, $200 in homeowners insurance, and $300 in HOA dues. Those expenses increase the housing payment by $750, bringing it to $3,450. Total monthly obligations rise to $4,530. ($4,530 ÷ $9,000) × 100 ≈ 50.3% back-end DTI The higher property costs may affect qualification, so the borrower may need a different property, lower qualifying debt payments, or another financing approach for which they are eligible.
Ways to Lower DTI Before Applying for a Mortgage
DTI can decrease when you reduce counted monthly debt payments, lower the proposed housing expense, or document additional eligible qualifying income.
Paying off a counted obligation can reduce DTI when the lender verifies that its monthly payment can be removed. A partial principal reduction may leave an installment loan’s required monthly payment unchanged, producing no immediate DTI improvement.
For example, assume qualifying monthly income is $8,000. Eliminating a counted $250 monthly payment reduces DTI by: ($250 ÷ $8,000) × 100 = 3.125 percentage points That reduction assumes the lender excludes the payment and all other inputs remain unchanged. Other options may include choosing a property with lower taxes, insurance, or association dues; reducing the proposed mortgage payment; or documenting eligible income that was not initially counted. Before using cash to pay off debt or increase your down payment, confirm the expected underwriting benefit. Preserve sufficient funds for the down payment, closing costs, required reserves, and your household’s emergency needs.
Calculator Limitations
A debt-to-income ratio mortgage calculator provides an estimate based on the numbers entered. It does not replace mortgage underwriting. Mortgage qualification does not establish what you can comfortably spend each month. Household affordability also depends on take-home income, maintenance, utilities, childcare, transportation, savings, and other expenses. Compare the proposed housing payment with your actual household budget, including room for repairs and unexpected costs. The calculator cannot determine whether:
- All income entered qualifies as qualifying income.
- A debt qualifies for exclusion under the applicable program.
- A student-loan payment must be recalculated.
- Either a collection or a tax payment must be included.
- The property qualifies for the selected mortgage program.
- Automated underwriting will approve the loan.
- The lender has additional overlays.
The Final DTI May Be Different
A lender may calculate a different DTI after reviewing income documents, credit reports, student loans, property taxes, insurance, HOA dues, and other obligations. Use the calculator as an early planning tool, not a guarantee of loan approval.
Frequently Asked Questions About Mortgage DTI
Does Paying Off a Credit Card Immediately Lower My Mortgage DTI?
It can lower DTI once the lender verifies the payoff and confirms that the monthly payment can be removed. Paying down only part of the balance helps DTI by reducing the qualifying monthly payment. Do not assume the underwriting calculation changes automatically after you make a payment.
Do Medical Bills Count Toward Mortgage DTI?
Medical collections, provider payment plans, credit-card balances, and court judgments can receive different treatment. Some programs exclude medical collections or certain medical payments. USDA, for example, excludes medical collections and medical payments under its ratio-analysis guidance. However, payments on ordinary credit cards or personal loans used to cover medical expenses may still count. A judgment requires separate review under the applicable program.
Does Rent Count in My DTI When I Am Buying a Home?
Current rent is generally not treated as a continuing housing expense when the new primary residence replaces the rental housing. Continuing rental obligations may require different treatment, including when buying a second home or investment property. Your rental-payment history may also remain relevant to underwriting.
Can Child Support Income Help Lower My DTI?
Eligible child-support income may increase qualifying income and lower DTI when the applicable documentation, receipt, and continuance requirements are met. Include only the amount the lender expects to use for qualification.
Does a 401(k) Loan Count in Mortgage DTI?
Some programs allow payments on loans secured by the borrower’s retirement assets to be excluded when the required documentation supports that treatment. The loan may still reduce the assets available to satisfy reserve requirements. The lender should confirm whether the payment must be included in DTI before you remove it from the calculator.
Can Mortgage DTI Change After I Am Preapproved?
Yes. Changes to qualifying income, debt payments, interest rates, the loan amount, taxes, insurance, mortgage insurance, or association dues can change DTI before closing. Recalculate when you select a property and obtain more accurate costs. Material changes may require updated underwriting.
Final Thoughts on Using a Debt-to-Income Ratio Mortgage Calculator
A useful DTI estimate connects three figures: qualifying monthly income, the full proposed housing payment, and the other monthly debts required by the mortgage program. Accurate documents and property-specific costs help the calculator reflect the numbers an underwriter is likely to evaluate. Program rules, underwriting findings, and any lender requirements determine how those figures affect qualification. Your household budget answers a separate question: whether the proposed payment leaves enough take-home income for everyday expenses, maintenance, savings, and unexpected costs. Consider both when evaluating the financing and property.
This article about “Debt-to-Income Ratio Mortgage Calculator: Calculate Front-End and Back-End DTI” was updated on October 22nd, 2026.
