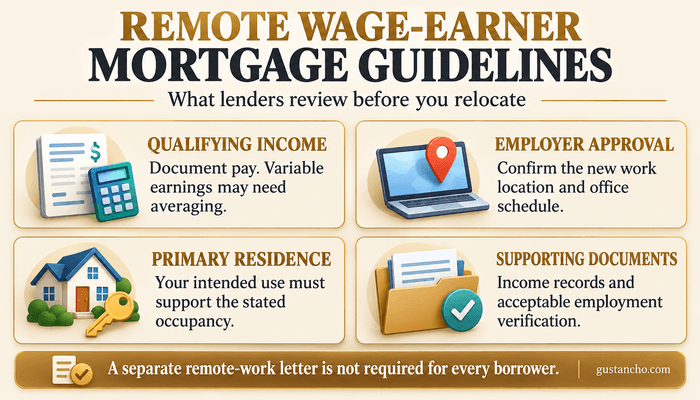
Yes. A remote W-2 employee may qualify for a mortgage, including when buying a primary residence in another state. In general, remote wage-earner mortgage guidelines follow the same income and employment rules as those for other W-2 borrowers. Your income must qualify, your work arrangement must support the move, and the home must meet the loan program’s occupancy requirements. If your move raises any questions, the lender may ask your employer to confirm that you can work from the new location and will also want to know about any changes to your pay or any change to the amount of time you need to be in the office. A separate remote work letter is not required for every borrower.
Buying a Home Far From Your Employer or in Another State
You may be able to buy a primary residence far from your employer’s office, including in another state. Distance alone does not determine mortgage eligibility. The lender reviews whether your employer permits the proposed work arrangement, whether your qualifying income is expected to continue after the move, and whether your work schedule is compatible with occupying the new home as your primary residence. If regular office attendance is required, you may need to explain how you will manage that travel. Before you move, you must check that your employer will allow you to work from the new location. If the move conflicts with your current arrangement, the lender will require evidence that you will continue to earn qualifying income after the move. An approved change in work location or office attendance requirements may address the issue, subject to review of the arrangement and its effect on your pay.
Fully Remote Employment
A fully remote position generally offers more flexibility when choosing where to live. If the job does not require regular office attendance and the employer permits work from the new location, the distance from the office is easier to explain.
Hybrid Employment
A hybrid employee still has in-person responsibilities. The lender may need to understand how the required office schedule and travel arrangements are compatible with living in the proposed home.
Temporary Remote Employment
A temporary work-from-home arrangement requires consideration of what happens when it ends. If returning to the office from the new home would be impractical, the lender may request documentation of an approved arrangement that supports continued employment after that date.
Why Occupancy Matters for Remote Workers
Employer permission to work from home will establish that your job can continue from that location. Occupancy is a different issue entirely: it’s about how you intend to use the home. An employer letter in itself will not establish that the property will become your primary residence. Fannie Mae’s occupancy guidelines differentiate between primary residences, second homes, and investment properties. When you’re applying to buy your own primary residence, your intended use of the property must be as such. You will also, of course, have to satisfy the occupancy requirements of the applicable mortgage program (including any required move-in dates).
Income and Employment Documents Remote Workers May Need
Remote W-2 employees generally document their income using the same methods as other employees. Depending on the mortgage program and income type, the lender may use recent paystubs and W-2 forms, written verification from the employer, or an acceptable electronic employment and income verification service. Employment may also need to be reverified before closing.
The documents requested depend on which verification method provides the information needed for your application. You do not automatically need to supply every form of verification.
For example, Fannie Mae’s documentation standards recognize documentation from borrowers, employers, and third-party verification providers, subject to the applicable requirements. If you have already started a new remote job, the lender will review your current employment and earnings in accordance with the required verification rules. You might need to provide an offer letter or employment agreement, depending on your situation. If you are qualifying with income from a job you have not started yet, the mortgage program’s future-employment rules will apply. For Fannie Mae loans, the lender will use its Employment Offers or Contracts guidelines.
Additional Documentation for Remote Work or Relocation
If ordinary income documents leave questions about your work arrangement, the lender may request additional employer confirmation. This may address permission to work from the new location, required office attendance, any scheduled end to remote work, and changes to compensation after relocation. A separate remote-work letter is not automatically required for every borrower. Additional documentation helps resolve questions that the standard income and employment verification does not answer.
When a Letter from the Employer May Be Needed
A lender might ask for a letter from your employer if regular employment verification does not clearly show how your job will continue after you move. This request could be due to a specific underwriting concern or simply part of the lender’s documentation process. However, it is not a rule that applies to all remote employees.
What Should the Employer Letter Confirm?
If asked, the letter can confirm your approved work location, any required office attendance, whether there is an end date for your remote work, and any pay changes related to your move. The employer should only describe what is currently approved, not promise permanent remote work or a job that will never end. Fannie Mae’s general rules say your income should be expected to continue. If your income does not have an end date and you meet the income history rules, you usually do not need to show extra proof unless something suggests otherwise. If your move does not match what your employer has approved, you may need to provide more documents.
Fully Remote vs. Hybrid vs. Temporary Remote Work
The type of remote arrangement matters when the new home is far from the employer.
Fully Remote Employment
A fully remote employee typically does not have to report to a physical office regularly. If the employer confirms that the position can continue from the new location, the employer’s distance is generally easier to explain.
Hybrid Employment
A hybrid employee still has an in-person work requirement. If the borrower must report to an office several days per week, the lender may question a new primary residence that is too far away for a reasonable commute.
Temporary Remote Employment
Temporary work-from-home arrangements require additional attention. If the borrower is expected to return to the office later, the lender needs to determine whether the employment arrangement is compatible with the new home’s location.
Do Remote Employees Need a Two-Year Work History?
 Working remotely does not create a separate employment-history requirement. Under Fannie Mae’s employment standards, the lender reviews whether your work history shows a reliable employment pattern over the most recent two years. A shorter history may be acceptable when positive factors in your employment profile reasonably offset it. That broader review is different from the history required for a particular type of income. Your time with the current employer, overall employment history, and the length of time you have received specific earnings are separate considerations.
Fixed Base Income
Fannie Mae’s base-income guidelines define fixed base income as a set salary or a fixed hourly rate with guaranteed minimum hours. There is no minimum history of receiving that fixed base income for it to be considered qualifying income. The lender must still complete the applicable employment review, document the earnings, and satisfy the remaining qualification requirements.
Variable Base Income
Variable base income is income at a fixed hourly rate with variable hours or an hourly rate that varies. You must have at least 12 months of variable base income according to Fannie Mae. The lender will review the earnings trend and calculate the qualifying income in accordance with the applicable rules. These distinctions are important when a remote worker moves into a new job or a new pay structure. A new fixed salary and a variable hourly rate will require different income analysis, even if both roles are remote.
How Pay Structure and Relocation Affect Qualifying Income
Even if your remote-work setup is approved, it doesn’t decide how much of your income the lender can count. Salary, hourly pay that changes, overtime, bonuses, and commissions all need different paperwork and calculations. Depending on your mortgage program and income type, the lender might average your earnings, look at your pay history, or check for any drop in your income. If your pay changes after you move, this will also affect your mortgage review. For example, if your employer lowers your salary when you relocate, the lender will use your new, lower pay. Fewer hours, less overtime, or changes to bonuses and commissions can also affect how much income counts. Let your mortgage professional know about any changes early, so your qualification matches what you’ll actually earn after the move.
Working Remotely? Explore Your Mortgage Options
Remote employment may be acceptable for a mortgage when your job, income, and ongoing employment can be properly documented. Gustan Cho Associates can help you review what lenders may need.FHA, VA, USDA, Fannie Mae, and Freddie Mac Guidelines
The applicable mortgage program and income type determine how your employment and earnings are evaluated. These official sources explain the requirements relevant to remote W-2 borrowers.
Fannie Mae
Fannie Mae’s employment standards address employment patterns, job changes, and gaps. Its separate base-income requirements explain how fixed and variable earnings are documented and calculated. The lender considers your broader employment history separately from the history required for each income source. Moving into a remote position does not automatically determine whether all your earnings qualify.
Freddie Mac
Freddie Mac Section 5302.2 addresses employed-income documentation and verification, including the applicable employment verification before closing. Confirmation that you work remotely may resolve a question about your work location. The lender must still obtain acceptable documentation of the employment and earnings used to qualify you.
FHA
HUD Handbook 4000.1 explains FHA’s employment verification and effective income requirements—the rules governing which earnings count toward qualification. Employment gaps, job changes, and variable earnings may require additional review under the applicable handbook provisions. Remote-work permission helps explain the employment arrangement but does not replace that income analysis.
VA
VA’s Chapter 4 credit-underwriting guidance requires qualifying income to be verifiable, stable, reliable, and expected to continue for the foreseeable future. Two years with the same employer is not required to reach that determination. For a relocating remote employee, the lender must have sufficient information to evaluate whether the employment and income remain dependable under the proposed arrangement.
USDA
USDA HB-1-3555, Chapter 9 distinguishes household income used to determine program eligibility from repayment income used to qualify for the mortgage. For repayment income, the lender must document the source, evaluate its stability, and establish the likelihood that it will continue for at least 3 years into the mortgage term. This requires a supported underwriting assessment; it does not mean your employer must guarantee three years of employment.
Remote W-2 Employees vs. Self-Employed Workers
Working from home describes your work location. Your employment relationship and ownership interest in the business help determine which mortgage income rules apply. W-2 employees generally qualify based on the applicable employment income documentation. However, receiving a W-2 does not always establish ordinary employee treatment. Under Fannie Mae’s employment standards, a borrower with a 25% or greater ownership interest in the business must meet self-employment requirements, even if the business pays that borrower a W-2 salary. Freelancers and independent contractors generally require an analysis of self-employment income. The documents and calculations depend on the mortgage program and business structure. For more information about tax returns, business records, and available documentation options, see our guide to self-employed mortgage loans.
Hypothetical Remote-Worker Mortgage Examples
These examples demonstrate how different forms of working can impact the employment and occupation review.
Fully Remote Employee Moving to Another State
A W-2 employee works remotely for a CA company and is looking to purchase a primary residence in Arizona. The issue is whether or not the employer permits work in Arizona. Verification from the employer regarding the approved work location, attendance requirements, and compensation would be useful in answering that question. The lender will still have to verify qualifying income and determine whether the proposed occupancy satisfies the mortgage program’s requirements.
Hybrid Employee Buying Far From the Office
A borrower has to report to a Chicago office three days per week and would like to purchase a home several hundred miles away. The issue is whether that reporting schedule is workable while living in the new home. Written employer approval to reduce the office requirement could go some way towards establishing a viable arrangement. If the reporting schedule remains as is, the lender will have to assess the proposed travel and living arrangements before accepting the explanation of employment and occupancy.
Longtime Employee Recently Approved for Remote Work
A borrower has been with the same employer for five years and has just been approved to work from home following a move. A dated employer letter confirming the approved location, the effective date, and any changes to remuneration will serve as the supporting document for the remote working arrangement. The lender will then assess the earnings in accordance with the relevant income rules. The fact that the individual has now been working from home does not in itself constitute a new source of income.
Employee With a Temporary Remote Arrangement
A borrower can work from home for six months and is then expected to return to an office far from the proposed home. The issue of what happens to employment after that point remains unresolved. Written approval for continued remote work or a transfer to a more local office could provide a viable solution. The lender will need to assess the actual arrangement as documented, its length, and the income expected to be available under it before deciding whether that income is sufficient to support qualification.
How Remote Workers Can Prevent Mortgage Delays
Answer questions about your work location, schedule, and pay early. This helps make sure your mortgage application matches the setup you’ll have after you move.
- Employer approval for the destination state is unclear. If you’re not sure your employer allows you to work from your new state, check before you move. If the lender asks for more proof, get written confirmation from the right person at your company.
- Hybrid attendance requirements conflict with the move. If your job has hybrid attendance rules, find out how often and where you need to go to the office. Talk with your mortgage professional about your schedule, and keep records of any changes your employer approves that make your move possible.
- Temporary remote permission is approaching its end date. If your remote work approval is ending soon, find out what will happen when you’re expected back in the office. Get proof of any extension, transfer, or new arrangement that lets you keep working from your new home.
- Compensation will change after relocation. If your pay will change after you move, let the lender know about any changes to your salary, hours, overtime, bonuses, or commissions. Give them written confirmation from your employer with the new details and when they start, so the lender can review your future income.
- Employment records contain conflicting information. If your employment records don’t match up, check your application for mistakes and tell your mortgage team about any differences in your job title, dates, pay, or work setup. Ask your employer to clear up or fix any issues before the final review.
FAQs About Remote Wage-Earner Mortgage Guidelines
Can I Get a Mortgage if My Employer is in Another State?
Yes you can qualify even if your employer is in a different state. The lender must establish that your qualifying income and approved work arrangement support the purchase and that the property meets the applicable occupancy requirements.
Does My Employer have to Put ‘Remote’ on My Paystub?
No. A paystub is an earnings statement and not a statement of your approved work location. If the lender requires any clarification regarding remote working, it can be addressed via a standard employer verification or other appropriate supporting documentation.
Can My Employer Confirm My Remote Working Arrangement by Email?
Possibly. It will depend on the requirements of the mortgage program and the lender’s verification process. Ask your mortgage professional whether an employer email address will meet the requirement or if some other form of verification is needed.
Does Working from Home Affect Your Mortgage Interest Rate?
Remote employment in itself is not generally a separate pricing factor. Your rate will be determined by the mortgage program, your credit, your LTV, occupancy, property type, points, and lender pricing.
Can I Buy a Primary Residence Before Moving to the New State?
Potentially. The lender will need to assess your intended occupation, the move-in requirements of the mortgage program, and whether your qualifying employment and income will continue after you’ve moved. It’s important to discuss the proposed purchase and move-in dates as early as possible so that the application reflects your actual plans.
Do I Need to Provide My Tax Returns if I Work Remotely?
Remote work in itself doesn’t create a tax return requirement. It will depend on the mortgage program, your sources of income, whether you own a business, and the required documentation. Some W-2 employees will be required to file a tax return for reasons unrelated to working remotely.
Final Thoughts on Remote Wage-Earner Mortgage Guidelines
Mortgage qualification for a remote employee depends on how the documented income, approved work arrangement, and intended occupancy fit together. The lender must be able to evaluate the earnings used for qualification and understand how the borrower will continue working while occupying the proposed home. The remaining decision is whether the available documentation supports approval under the selected mortgage program. Additional verification may resolve an unclear work arrangement, while changes to compensation or required office attendance may call for a revised employment arrangement or reassessment of loan qualification before the purchase can proceed.
This article about “Remote Wage-Earner Mortgage Guidelines: How Lenders Verify Remote Employment ” was updated on October 23rd, 2026.