Fannie Mae second home guidelines require the borrower to occupy the property for part of the year and keep exclusive control of it. The home must be a one-unit property suitable for year-round use. It cannot be structured primarily as a rental property or timeshare. Second-home loans also have specific requirements for down payment, reserves, credit, DTI, and Desktop Underwriter approval.
What Qualifies as a Second Home Under Fannie Mae Second Home Guidelines?
Under Fannie Mae’s occupancy requirements, a second home must:
- Be a one-unit property.
- Be suitable for year-round occupancy.
- Be occupied by you for part of the year.
- Remain under your exclusive control, without an agreement giving a management company control over occupancy.
- Not be a timeshare or a property purchased primarily for rental income.
Common Second-Home Problems to Check Before Making an Offer
Review these details early, so the lender can identify potential financing problems:
- Reservation restrictions: Check owner-use rules for blocked dates, advance booking requirements, or limits on personal stays. Give the lender the actual agreement.
- Mandatory rental programs: Find out whether ownership requires participation in a rental pool or hotel-management program. Have the lender review those terms before you commit.
- Seasonal access: Confirm whether roads, water, utilities, and other essential services remain available year-round.
- Missing expense documentation: Provide current mortgage statements, tax bills, insurance information, and association dues for existing properties. Obtain estimates for the proposed home so the lender can accurately calculate housing expenses.
Have Your Second-Home Purchase Reviewed
Before making an offer, send Gustan Cho Associates the property listing and any rental or management agreement. Ask for a review of the property, your qualifying payments, and available funds.
Does a Second Home Have to Be 100 Miles Away?
Currently, Fannie Mae does not mandate a specific distance for a second home.
As it stands, there is no 50-mile, 100-mile, or similar distance rule in Fannie Mae’s second-home guidelines.
Even so, distance can raise underwriting issues when the proposed occupancy is illogical. For example, a lender may be interested in why a borrower is purchasing another home very close to the primary residence. The issue is not whether the property goes beyond a certain distance. It is whether the property is being purchased and used as a second home.
Down Payment and LTV Requirements for a Second Home
Currently, Fannie Mae permits up to 90% loan-to-value for one-unit second-home purchases in Desktop Underwriter. This allows the borrower the opportunity to purchase the home with a 10% down payment. Having a 10% down payment does not guarantee approval. The borrower must satisfy all the requirements relating to credit, income, assets, reserves, mortgage insurance, and Desktop Underwriter. Higher down payments can reduce the loan-to-value ratio. The preferred mortgage insurance and loan pricing can be impacted as a result.
Credit Score and Desktop Underwriter Requirements
For standard Fannie Mae second-home purchases, a Desktop Underwriter (DU) Approve/Eligible recommendation is required. Lenders need to check the supporting documents and make sure the borrower, property, and loan meet all eligibility requirements. Fannie Mae does not set a minimum credit score for DU casefiles. DU looks at creditworthiness as part of its full risk assessment. However, individual lenders might have their own minimum scores or extra requirements.
DTI Requirements for a Fannie Mae Second Home
DU’s maximum allowable total debt-to-income (DTI) ratio is 50%, but approval can require a lower ratio. DTI compares your required monthly debt payments with your gross qualifying monthly income. The calculation includes the second-home housing payment, applicable primary-residence housing expenses, and other qualifying debts. DU evaluates this ratio alongside credit, assets, reserves, and other risk factors.
Reserve Requirements for a Second Home
When a second home is bought using Desktop Underwriter (DU), Fannie Mae usually requires a minimum of two months’ worth of reserves. These reserves are the eligible assets left over after the amount needed to complete the transaction has been deducted. One reserve month is equal to the second home’s qualifying housing payment, which includes the amounts for principal, interest, and the relevant taxes, insurance, mortgage insurance, and association dues. So, if the payment in question is $2,500, a requirement covering two months means that there must be $5,000 left from eligible assets after the closing. Additional reserves may be required for other financed properties. That calculation excludes the home being financed and your primary residence. A mortgage on your primary residence alone does not trigger the additional-property reserve calculation. DU may also require more reserves based on the overall loan profile.
Can You Rent Out a Fannie Mae Second Home?
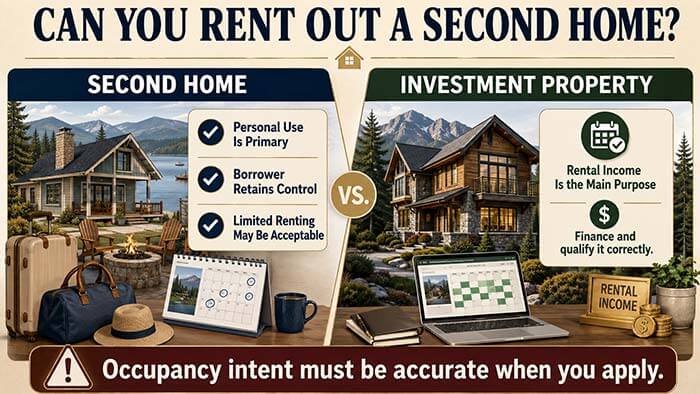 Some rental activity does not automatically disqualify a property from second-home financing. The home must still meet all second-home requirements, including your personal occupancy and exclusive control over its use. Rental income from a second home cannot be used to qualify for the mortgage. You must qualify without that income, although you may use rental receipts toward your mortgage payments.
Short-Term Rentals and Management Agreements
Fannie Mae’s occupancy guidance does not establish a universal Airbnb or Vrbo rental-day allowance. The lender must review the property’s intended use and any rental agreement. An agreement giving a management company control over when you may occupy the home conflicts with Fannie Mae’s exclusive-control requirement. Have the lender review those terms before making an offer.
Rental Management Agreements
An eligibility issue can arise from an agreement that allows the operator of a hotel, a rental management company, or another management company to determine when the borrower may occupy or use the property. The borrower must be able to determine occupancy.
Second Homes vs. Investment Properties
The key difference is the property’s end use.
A second home is a property that the borrower uses for personal occupancy that meets Fannie Mae requirements.
An investment property is the type of property purchased primarily for a cash flow, an appreciation, or other investing purpose and is not occupied personally. The end use of the property determines the amount of the deposit and reserves, pricing, treatment of rental income, and underwriting requirements. Prospective borrowers should accurately describe the proposed end use of the property. An investment property should not be misrepresented as a second home. It can result in underwriting and occupancy problems.
Why Second-Home Mortgage Pricing Can Be Higher
Fannie Mae adds a special fee, called a loan-level price adjustment (LLPA), to some second-home loans. Investment properties have their own separate fees. These fees do not create a standard interest rate difference for different types of occupancy. Other factors like your credit, down payment, property type, loan terms, lender pricing, and the market also affect your loan offer. To see what you will pay upfront and each month, compare the interest rate, points, mortgage insurance, and closing costs for each option.
Second-Home Reserve Requirements Can Affect Approval
Borrowers with multiple financed properties may need additional verified reserves after closing. We’ll review your assets and reserve requirements upfront.Common Second Home Problems to Check Before Making an Offer
Second-home loans can run into problems when the property use or documentation does not match Fannie Mae requirements.
Rental Income Is Needed to Qualify
Rental income from a second home generally cannot be used to qualify the borrower. If the loan only works when projected rental income is included, the property may need to be evaluated under investment-property guidelines instead.
A Management Company Controls Occupancy
Some resort and vacation properties require owners to place their units in a rental program or to give a management company control over reservations. That arrangement can conflict with Fannie Mae’s requirement that the borrower maintain exclusive control over the property.
The Property Does Not Support Year-Round Occupancy
A property may pose an eligibility problem if it cannot reasonably be occupied year-round due to its construction, utilities, access, or other limitations.
Additional Properties Increase Reserve Requirements
Borrowers who already own other financed properties may need more reserves than someone purchasing a second home with no additional financed real estate. This should be reviewed before the borrower makes an offer.
Hypothetical Fannie Mae Second Home Example
Assume a borrower purchases a one-unit lake home for $400,000, with an appraisal supporting that price. A 10% down payment of $40,000 leaves a $360,000 loan. The borrower’s monthly figures are:
- Gross qualifying income: $12,000
- Primary-residence housing payment: $2,200
- Second-home housing payment: $2,500
- Other qualifying debts: $700
The housing payments include principal, interest, and applicable taxes, insurance, mortgage insurance, and association dues. Total monthly obligations are $5,400, giving a DTI of: $5,400 ÷ $12,000 = 45%
How Much Money Does the Borrower Need?
The $40,000 down payment is only part of the cash picture. Closing costs and applicable prepaid expenses must also be covered. If the qualifying payment used for reserves is $2,500 and the reserve requirement is two months, $5,000 in eligible assets must remain after closing. The borrower, therefore, needs $45,000 in eligible funds, plus closing costs and prepaid expenses, before any additional reserve requirements are met. Of that $45,000, $40,000 goes toward the down payment, and $5,000 remains available as reserves.
What to Have Your Lender Check Before Making an Offer
Give your lender the property details and ask for a review of:
- Rental or management agreements: Share the actual contracts, including reservation rules, owner-use restrictions, and any required participation in rentals.
- Condo-project information: If this applies, share the listing and any association or project documents you have. A quick review can identify any issues, but a full project review may still be required.
- Your intended personal use: Let us know when you plan to stay at the home and if you expect to rent it out at other times.
- Both housing payments: Share your current housing costs and estimates for the second home, including taxes, insurance, mortgage insurance, and association dues if they apply.
- Assets remaining after closing: Ask your lender to review your asset statements and estimate what will be left after the down payment, closing costs, and prepaid expenses.
Have Your Second-Home Purchase Reviewed
Fannie Mae guidelines on second homes focus heavily on how the property will actually be used.
A qualifying second home must be occupied by the borrower for part of the year, remain under the borrower’s control, and meet Fannie Mae’s property and underwriting requirements. There is no universal 100-mile rule, and the property does not have to be located in a traditional vacation area.
Before making an offer, borrowers should have their proposed occupancy, down payment, DTI, reserves, other financed properties, and property type reviewed. Identifying a second-home eligibility problem early can prevent the loan from having to be restructured as an investment-property transaction later in underwriting.
FAQs About Fannie Mae Guidelines on Second Homes
Can Gift Funds Be Used to Buy a Fannie Mae Second Home?
Yes. Eligible gifts can cover the down payment, closing costs, and reserves. If LTV, CLTV, or HCLTV exceeds 80%, you must contribute 5% of the purchase price from your own funds—$20,000 on a $400,000 purchase — with a supporting appraisal. When all three ratios are 80% or less, no contribution from your own funds is required. Gift eligibility and documentation requirements still apply.
Can a Condo Qualify as a Fannie Mae Second Home?
Yes. A condo unit can qualify as a second home, but the property must meet both the second-home occupancy requirements and applicable Fannie Mae condo-project requirements. Certain hotel-style, timeshare, fractional-ownership, or occupancy-restricted projects are not eligible.
How Many Financed Properties Can I Own and Still Buy a Second Home?
Fannie Mae currently allows a borrower financing a second home through Desktop Underwriter to have up to 10 financed properties. Owning multiple financed properties can also increase the reserve requirement for the new loan.
Can I Own More Than One Second Home?
Potentially, yes. Fannie Mae does not limit a borrower to only one property classified as a second home. Each property must independently meet the applicable occupancy requirements, and the borrower must still qualify financially while staying within Fannie Mae’s financed-property limits.
Can a Manufactured Home Qualify as a Fannie Mae Second Home?
Yes, but Fannie Mae currently limits second-home eligibility for manufactured housing to eligible multi-width manufactured homes. The property and loan must also satisfy the applicable manufactured-housing requirements.
This article about “Fannie Mae Second Home Guidelines: Occupancy, Down Payment, and Reserves” was updated on September 30th, 2026.