Verified assets for home loan approval are funds that lenders can verify are available for the down payment and closing costs, and for holding in reserve. Verified assets may include checking and savings accounts, investments, eligible retirement accounts, gifts, or other approved sources. Underwriters need to review recent transactions and account activity. This helps determine that the funds for closing come from an approved, acceptable source.
Why Mortgage Lenders Verify Assets
Mortgage lenders verify assets to ensure the borrower has sufficient funds for the down payment, closing costs, any prepaid amounts, and any required reserves. The various aspects of a loan case file, including documentation, are reviewed by the underwriter. This includes the source and the amount of funds. Funds that cannot be well-documented cannot be used to facilitate the transaction.
What Assets Can Be Used for Mortgage Qualification?
Verified assets for a home loan must satisfy the program’s requirements, be available to the borrower, and be documented.
Checking and Savings Accounts
Checking, savings, money market accounts, and CDs held by the borrower are typically used for down payment, closing costs, and reserves when proper documentation is provided.
Investment Accounts
Brokerage accounts, stocks, bonds, and mutual funds may also be used. In some cases, the lender may also need to verify the account and determine whether a sale is required.
Retirement Accounts
Vested funds from a retirement account (401k or IRA) may also be used. The closing funds or reserves may be used if the loan program permits the use of retirement funds and the borrower has access to the funds.
Additional Funding Sources
Additionally, other approved funding sources (sale of personal property, real estate, etc.) may be acceptable funds, as may gift funds, depending on the mortgage program.
How Underwriters Verify Bank Statements and Assets
Mortgage lenders may verify assets through bank and investment statements, a verification of deposit completed by the financial institution, or an approved third-party electronic asset-verification service. The documents generally must identify the financial institution, borrower, account, statement period, transaction activity, and ending balance.
For a Fannie Mae loan using standard statement documentation, purchase transactions generally require the most recent full two months of account activity. Refinance transactions generally require the most recent full month.
These periods are not universal. Desktop Underwriter asset validation, third-party electronic verification, and specific DU findings may result in different documentation instructions. FHA, VA, USDA, Freddie Mac, and Non-QM loans may also have different requirements. Borrowers should provide the documents requested for their specific loan rather than assume every mortgage requires two months of statements.
Large and Unusual Bank Deposits
A large deposit does not automatically prevent mortgage approval. The lender must determine whether the funds come from an acceptable source and are needed for the transaction. A large deposit for a Fannie Mae purchase loan is a single deposit that exceeds 50% of your total monthly qualifying income. If the money is needed for the down payment, closing costs, or reserves, the lender must document the source of the funds. Payroll deposits, tax refunds, and transfers between verified accounts generally do not need additional documentation when the source is clearly identified. If a large deposit cannot be fully documented, the lender may subtract the unsourced portion from the account balance. The remaining funds may still qualify as verified assets for a home loan if they are sufficient to cover the transaction requirements. For a Fannie Mae refinance, an explanation is not required solely because a deposit is large, but the lender must still identify borrowed funds and account for any related debt.
Earnest Money and Asset Verification
Earnest money is credited toward the buyer’s required funds at closing. When the deposit is part of the borrower’s required contribution, the lender may need to verify both the source of the money and proof that the escrow holder received it. Earnest money deposits are typically credited towards closing costs. However, you will be required to provide proof of the earnest money deposit.
Large earnest money deposits may require additional verification such as bank statements, a canceled check, or written confirmation that the escrow holder received the deposit.
Proof of payment should be kept by the buyer, as the purchase contract will only state that the deposit has been made.
Gift Funds and Other Acceptable Sources of Funds
Gift funds may qualify as verified assets for a home loan when the donor, property, and transaction meet the applicable mortgage-program requirements. The lender must document that the money is a true gift and that the borrower is not required to repay it. For eligible Fannie Mae loans, personal gifts may be used toward the down payment, closing costs, or financial reserves on a principal residence or second home. Personal gifts are not permitted on an investment property. Minimum borrower contribution requirements may apply depending on the property type, occupancy, and LTV. An acceptable donor may include a relative, domestic partner, fiancé, former relative, or certain other people who have a documented, long-standing familial-like or mentorship relationship with the borrower. The donor must also satisfy Fannie Mae’s interested-party restrictions. The gift letter must identify the donor, the donor’s relationship to the borrower, the gift amount, and the fact that repayment is not expected. The lender must verify that the donor had sufficient funds and that those funds were transferred to the borrower or the closing agent. FHA, VA, and USDA loans have their own donor, documentation, and permitted-use requirements, so Fannie Mae gift rules should not be applied to every mortgage program.
Using Retirement Accounts and 401(k) Funds
Vested retirement funds may qualify as verified assets for a home loan when the mortgage program’s requirements are met. For eligible Fannie Mae loans, vested funds in an IRA, SEP, Keogh, or 401(k) account may be used for the down payment, closing costs, or financial reserves.
The lender must verify that the borrower owns the account, that the funds are vested, and that the account permits the required withdrawal or access. When retirement funds are needed for closing, the lender may also require evidence that the required amount has been liquidated or received. Funds used only as reserves generally do not need to be withdrawn from the account.
Fannie Mae does not impose a universal rule limiting every retirement account to 60% of its value. The usable amount depends on the account terms, accessibility, vesting, and the type of assets held in the account. FHA, USDA, Freddie Mac, VA, and individual lenders may use different calculations or documentation standards, so borrowers should not apply Fannie Mae’s treatment to every mortgage program.
Do You Have Enough Verified Funds to Close?
Your down payment, closing costs, prepaid items, reserves, and earnest-money deposit may all need documentation. We’ll help calculate what you need upfront.Mortgage Reserve Requirements
When a mortgage is processed, the borrower’s cash is reduced by the down payment, closing costs, and other costs. The remaining cash is the mortgage reserve. In most cases, mortgage reserves are expressed as the number of months of total housing payments. The required reserves depend on the loan program, the type of property, the number of mortgaged properties, the underwriting approach, the risk, and other factors. Reserves are established on a case-by-case basis based on the transaction and the borrower profile. Cash and cash equivalents, as well as some retirement accounts, may qualify as reserves. Closing funds may not be considered reserves.
Assets That Cannot Automatically Be Used for Closing
Owning something of value does not automatically make it an acceptable source of mortgage funds. The money must be accessible, properly documented, and permitted under the applicable loan program.
For Fannie Mae loans, undocumented cash on hand generally cannot be used for the down payment, closing costs, or financial reserves. Personal unsecured loans, including signature loans, credit card lines, and overdraft protection, are also unacceptable sources of funds.
Proceeds from selling a vehicle, boat, artwork, or another personal asset may qualify when the borrower documents ownership, the sale, the buyer’s payment, and the deposit of the proceeds. Funds borrowed against an acceptable asset may also qualify under Fannie Mae’s separate requirements for secured borrowed funds. Cryptocurrency cannot be used directly as verified mortgage assets. For Fannie Mae to consider the proceeds, the cryptocurrency must be exchanged for U.S. dollars and deposited into an eligible regulated financial institution. The lender may also need to document the transaction and evaluate the deposit in accordance with the applicable large-deposit requirements.
Conventional, FHA, VA, and USDA Asset Rules
Asset and reserve requirements depend on the mortgage program, property type, occupancy, AUS findings, manual underwriting rules, and lender overlays. Borrowers should not apply a Fannie Mae deposit threshold or reserve rule to an FHA, VA, or USDA loan.
Conventional Loans
Fannie Mae and Freddie Mac have their own requirements for documenting bank accounts, investments, gifts, retirement funds, and reserves. The documentation and reserve requirements may also depend on Desktop Underwriter, Loan Product Advisor, the transaction type, and the number of financed properties. A one-unit principal residence does not automatically require reserves under Fannie Mae, but DU or other transaction requirements may call for them.
FHA Loans
FHA lenders must verify that the borrower has sufficient acceptable funds for the required investment and cash needed at closing. Reserve requirements depend on the property, underwriting method, and complete loan file. Reserves may be required for certain multi-unit properties or manual underwrites and may also be considered as a compensating factor.
VA Loans
VA borrowers must document the funds needed for any down payment, borrower-paid closing costs, and other required expenses. VA does not impose one universal reserve requirement on every home purchase. However, reserves may be required due to the property type, treatment of rental income, underwriting findings, or lender overlays.
USDA Loans
USDA does not universally require borrowers to have cash reserves remaining after closing. However, verified liquid reserves may affect the risk assessment produced by the Guaranteed Underwriting System (GUS). Funds used for closing and assets entered into GUS must be properly verified, and gift funds are not counted as cash reserves in GUS. Mortgage guidelines and lender overlays can change. Borrowers should confirm the asset and reserve requirements for their specific program before moving money, accepting gift funds, or liquidating an account. 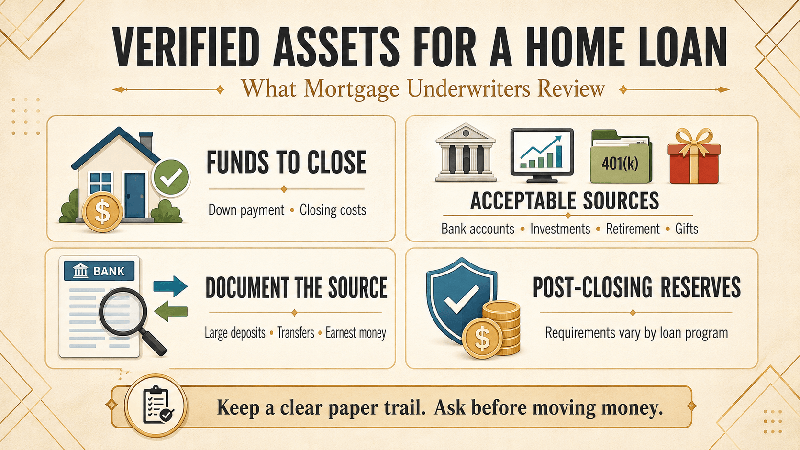
Mortgage Asset Verification Example
Suppose a buyer is purchasing a $350,000 home with a 5% down payment of $17,500. Estimated closing costs and prepaid expenses are $9,000, bringing the total estimated funds needed to $26,500. The buyer has already paid a $5,000 earnest-money deposit. For this example, assume the lender has documented the source and confirmed that the deposit was received. Because the earnest money will be credited at closing, the buyer’s remaining estimated cash requirement is $21,500. The buyer has:
- $17,000 in checking, including an $8,000 deposit from selling a vehicle
- $10,000 in savings
- $50,000 in a retirement account
The checking and savings accounts contain $27,000 in total. However, that amount includes the $8,000 vehicle-sale deposit. If the buyer documents ownership of the vehicle, the sale, the buyer’s payment and the deposit of the proceeds, the lender may accept the full $27,000 as verified liquid funds. That would be enough to cover the estimated $21,500 still needed at closing. If the $8,000 deposit cannot be documented and must be excluded, the borrower has only $19,000 in verified liquid funds:
- $27,000 in checking and savings
- Minus the $8,000 unsourced deposit
- Equals $19,000 in verified liquid funds
The borrower would then be $2,500 short of the estimated $21,500 needed at closing. Eligible retirement funds could potentially cover the shortage if the borrower owns the account, the funds are vested and accessible, and the applicable mortgage program permits their use. Final approval would depend on the lender’s documentation requirements and the borrower’s actual cash-to-close amount.
Common Asset Verification Mistakes Before Closing
Here are some verification pitfalls home buyers tend to spot after assets have been verified, prior to closing. These include, but are not limited to:
- Moving or structuring funds in a manner that does not provide a complete, verifiable paper trail.
- Depositing a significant amount of cash without a supporting document.
- Borrowing money (unsecured) for the down payment or closing costs.
- Thinking you can sell personal property for cash (car, artwork, crypto, etc.).
- Spending cash that is intended to be held in reserve for closing costs.
- Leaving unverified gift funds.
- Closing account(s) before verifying funds to the lender is complete.
Borrowers should keep all records, documents, and receipts associated with each transaction and cash withdrawals until the loan process is complete. Large transactions made to support underwriting may create last-minute roadblocks (but may not be apparent until then). Speaking with your loan officer is advised.
Final Thoughts on Verified Assets for Home Loan
Documentation of funds is a crucial part of the closing process for a home loan. However, some borrowers choose to move funds without a clear documentation trail, causing issues at closing.
Borrowers should plan to avoid transfers and organize records of funds to eliminate unnecessary steps when explaining the source of funds for major transactions when applying for a loan. The requirements for verified assets for home loan approval are dictated by the mortgage program, the specific transfer, and the underwriter’s findings.
Even if the borrower has the funds in an account, the lender still needs adequate documentation for the fund’s availability and the purpose for which those specific funds can be used.
FAQs About Verified Assets For Home Loan
Can Funds From My Business Be Used for a Down Payment?
For a Fannie Mae loan, business assets can be used for the down payment, closing costs, or reserves if the borrower owns the account and the funds are verified. If income from the business is also used to qualify for the mortgage, the lender must conduct a cash-flow analysis to ensure that withdrawing funds won’t harm the business or the qualifying income. The lender may ask for recent business account statements, a current balance sheet, or other necessary documents to assess the impact of the withdrawal.
Can Funds From a Foreign Bank Account Be Used To Buy a Home in The U.S.?
Fannie Mae allows such funds on eligible loans, provided the proper documentation is provided. Foreign documentation must be translated into English, or an exact translation must be provided. The funds must be converted to U.S. dollars and held in a U.S.- or state-governed financial institution prior to the Close.
Can Money from a Trust Be Used on a Mortgage?
Fannie Mae allows funds from a trust account if the borrower has access to the trust funds. The lender is required to verify the value of the trust and the terms under which the borrower has access to the funds.
Can Credit Card Reward Points Be Used Toward a Home Purchase?
For Fannie Mae, credit card reward points translate to down payment, closing costs, and reserve funds, provided points are converted to cash prior to closing. Additional documentation may be required to support the cash received, and if the funds would create a large deposit.
Can the cash value of Life Insurance Be Used for Closing?
The cash value of a life insurance policy can be used for closing costs and a down payment when the policy owner sells the policy or takes out a policy loan, per Fannie Mae guidelines. To satisfy the lender, the borrower is required to provide evidence of funds drawn toward closing.
Can a Bridge Loan Provide Funds for the Next Home Purchase?
Per Fannie Mae guidelines, a bridge or swing loan may be used for funding. The lender’s obligation is to ensure that loans on both the properties (old and new) and obligations on the bridge loan are serviceable by the borrower. The loan must also not be cross-collateralized against the new property.
This article about “How Mortgage Underwriters Consider Verified Assets For Home Loan” was updated on August 27th, 2026.