This guide covers VA loans with no credit scores in detail and examines the DTI (Debt-to-Income) requirements. VA loans stand out for their accommodating mortgage criteria compared to other loan programs. Despite their flexibility, it’s important to note that the Veterans Administration has taken a critical stance on recent late payments within the past year.
It may be possible to get a VA loan even if you have no credit score. Find out about VA credit rules, alternative credit, residual income, lender overlays, and the various no-score approval options.
While VA loans offer more forgiving terms for borrowers without established credit scores, timely payment history remains crucial in the evaluation process. Getting an automated underwriting system approval with late payments in the past 12 months will be very difficult. Many borrowers do not know that mortgage brokers like Gustan Cho Associates offer VA loans with no credit scores and DTI requirements.
Mortgage Guidelines vs Overlays on VA Loans
The Department of Veterans Affairs (VA) does not impose strict requirements regarding minimum credit scores or debt-to-income ratios for borrowers seeking approval through an automated underwriting system. At Gustan Cho Associates, numerous borrowers have successfully secured VA loans despite having credit scores in the 500s and debt-to-income ratios exceeding 60%, as long as they receive an approved/eligible status from the automated underwriting system. However, the question arises as to why many lenders establish minimum credit score criteria and debt-to-income ratio limits for VA loans.
VA Loans With No Credit Scores: 2026 Mortgage Guidelines
Even if a borrower does not have an adequate traditional credit history to enable the generation of a credit score, the lender must still decide whether the borrower has shown a reasonable ability and willingness to pay their financial obligations on time;
Is it Really Possible to Obtain a VA Loan if you Have No Credit Score?

The lender can review alternative or nontraditional credit, which can be verified, to determine whether the applicant is an acceptable credit risk.
No Credit Score Is Not the Same as Bad Credit
A third borrower could have a poor credit record, for example, one involving recent delayed payments, defaults, collections, charge-offs, bankruptcy, or foreclosure. They represent three distinct underwriting situations.
Why Some VA Lenders Require a Credit Score Anyway
Lender Overlays on VA Loans
For people with no credit score, a high residual income can be used to demonstrate that the suggested housing payment is financially reasonable when considered alongside the rest of the loan file
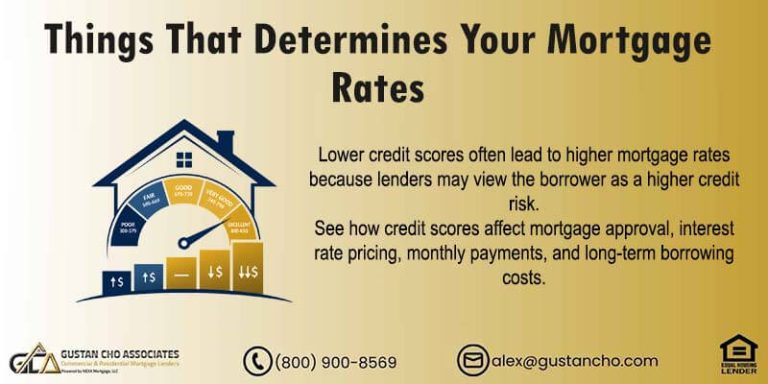
VA Loans With Credit Scores Down to 500 FICO

With VA loans with no credit scores, borrowers can still be eligible for approval through the automated underwriting system, even if their credit score is 500. However, some lenders may require a higher credit score despite automated approval. This practice is entirely legal, and Gustan Cho Associates stands out as one of the national lenders that adhere to this standard with no overlays on VA loans.
Gustan Cho Associates only goes by VA Agency Guidelines. As long as borrowers meet all basic VA agency guidelines, get an AUS approve/eligible, and meet the conditions, Gustan Cho Associates will approve and close their VA loan.
While many lenders typically set a credit score requirement of 620 for VA loans, Gustan Cho Associates has successfully processed numerous VA loans for borrowers below 600. As a zero overlays mortgage lender, Gustan Cho Associates maintains a policy of no additional requirements or restrictions on VA loans, ensuring fair access to financing for eligible borrowers.
VA Loans DTI Guidelines
Some borrowers may need to be made aware that the VA does not enforce a specific minimum debt-to-income ratio requirement, though individual lenders often set their guidelines. These guidelines typically range from 41% to 50% for VA loans. However, Gustan Cho Associates has successfully secured approval through the automated underwriting system for VA borrowers, even with debt-to-income ratios exceeding 60%, a rarity in the industry.
VA loans have no maximum debt-to-income ratio cap. Gustan Cho Associates has recently closed on a VA loan with a 543 credit score and a 64 debt-to-income ratio on a manual underwrite. Over 80% of our borrowers are folks who could not qualify at other lenders.
When borrowers have higher debt-to-income ratios, residual income becomes crucial for getting approval from the automated underwriting system. Gustan Cho Associates distinguishes itself as one of the few national lenders that do not impose overlays on debt-to-income ratios for VA mortgages. As long as borrowers demonstrate robust residual income, they stand a good chance of receiving automated approval, even with elevated debt-to-income levels.
Click Here To Talk To A Mortgage Officer About VA Loans
Obtaining a Certificate of Eligibility on VA Loans
Gustan Cho Associates specializes in helping active and retired members of the United States Military secure VA loans with no credit scores. Individuals with a Certificate of Eligibility from the Department of Veterans Affairs can apply for these loans. Our dedicated team ensures a seamless process by promptly assisting borrowers in obtaining their Certificate of Eligibility. With our support, borrowers can acquire this essential document within hours, as our experienced loan officers and mortgage processors handle the necessary procedures on behalf of our clients.
VA Eligibility Requirements

VA home loans are for owner-occupant homes only. VA loans are one of the best loan programs in the U.S. It is only for our U.S. Armed Services veterans with COE.
Here are the Basic VA Eligibility Requirements:
- VA offers 100% financing
- Upfront VA Funding Fee can be rolled into the VA loan balance.
- No closing costs: closing costs can be covered with seller concessions and lender credit
- The 2-year waiting period after Chapter 7 Bankruptcy, foreclosure, deed in lieu, short sale
- Borrowers can qualify for VA loans one year into a Chapter 13 Bankruptcy Repayment Plan
- No Waiting Period after the Chapter 13 Bankruptcy discharge date
- Outstanding collections and charged-off accounts do not have to be paid.
- One to four-unit properties are eligible
- 100% cash-out refinance is allowed.
Is 41% the Maximum Debt-to-Income Ratio Maximum Cap on a VA Loan
According to current VA guidelines, the additional review can be conducted differently if the residual income is at least 20% above the relevant VA limit, or if the higher ratio results from qualifying tax-free income. That is why it is inaccurate to state that all VA borrowers have to have a DTI under 41%.
It may be possible to have a higher debt-to-income ratio, but approval will depend on the full file, residual income, credit profile, underwriting findings, and the lender’s requirements.
Recent Late Payments Are Different From Having No Credit
Even recently, frequent late payments can still pose serious problems for underwriters, as they may indicate difficulty meeting current financial obligations.
Is it Possible to Obtain a VA Loan if Your Credit Score is 500?
Gustan Cho Associates has arrangements with wholesale lenders who are willing to consider VA borrowers even if their credit scores are below the minimum scores generally required by most lenders. Approval is still based on the entire loan file.
Should You Establish a Credit Score Before Applying for a VA Loan?
In some cases, establishing traditional credit can improve a borrower’s financing options; in other cases, the better approach is to maintain an otherwise clean record without a credit score and instead document current payment history.
Certificate of Eligibility and No-Score VA Loans
Veterans, currently serving military personnel who qualify, and some surviving spouses may be eligible for the VA home loan program, provided they meet the relevant requirements.
Does Zero Down Mean Zero Cash Needed?
No. Eligible VA borrowers with sufficient entitlement can often purchase a qualifying home without a down payment, subject to the property’s value, purchase price, entitlement, and loan approval. Most non-exempt VA borrowers also pay a VA funding fee, which can generally be financed into the loan on an eligible transaction. Certain veterans and other qualifying borrowers may be exempt from the funding fee.
The VA funding fee is also paid by most borrowers who are not exempt, and it can usually be financed into the loan as part of an eligible transaction. However, some veterans and other eligible borrowers are exempt from paying the funding fee.
That does not automatically mean the transaction will require zero dollars at closing. There can still be closing costs, prepaid expenses, escrows, appraisal-related expenses, and other transaction costs. Some costs may potentially be covered through permitted seller concessions, seller-paid costs, lender credits, or other allowable sources, depending on the transaction.
Is It Required for Borrowers to Have a Debt-to-Income Ratio of at Least 41%
The debt-to-income ratio is described by VA as being merely advisory and is considered to come second to residual income. When the debt-to-income r that the transaction will need no money at closing.
What We Would Review Before Telling a Veteran to Establish New Credit
The loan officer should also decide whether the file is likely to receive an acceptable result from automated underwriting or will require a manual or alternative-credit underwriting approach.
VA Loans With No Credit Scores and Lender Overlays
It isn’t until the various factors have been considered that one can decide whether establishing new traditional credit would, in fact, improve the borrower’s position. A preliminary review can prevent veterans from spending months trying to resolve a credit score issue they might not even have.
How VA Underwriting Works When You Have No Traditional Credit
Traditional Credit vs Non-Traditional Credit
A lender could, in certain situations, assess payment records for housing or other regular obligations, since rent is especially important;
Rental History Can Become Especially Important
Borrowers with no traditional credit trade lines will most likely not have a credit score. Borrowers with no active credit trade lines do not have to run out and get a bunch of secured credit cards or other types of credit and rent an apartment and keep the lease for two years to qualify for a mortgage.
What is Considered Alternative or Nontraditional Credit When Applying for a VA Loan?
People may be told that they automatically need three or four nontraditional credit accounts in order to obtain a VA mortgage. This requirement could arise from a specific lender, an investor, a credit-reporting service, or another mortgage program. It ought not to be treated as a general requirement of the VA.
Does a VA Loan with No Credit Score Need Manual Underwriting?
The specific path will depend on the borrower’s credit record, the results of the AUS review, the lender’s underwriting system, and the requirements of the wholesale investor providing the loan funds. That is another reason why the choice of lender is important.
VA Underwriters Look Beyond the Credit Score
Credit is Just One Part of the Analysis by Underwriters on VA Loans
Residual Income Can Be Critical on VA Loans
The Veterans Administration uses income guidelines based on factors such as geographic area, family size, and loan amount.
Qualifying For VA Loans With No Credit Scores With a Lender With No Overlays
For borrowers needing VA loans without strict credit score requirements, Gustan Cho Associates offers a solution. Our team’s proficiency in navigating the complexities of VA loan processing sets us apart. Explore financing options for veterans and active-duty military personnel in multiple states. Contact us via phone, text, or email today.
Gustan Cho Associates are mortgage brokers licensed in 48 states, including Washington DC, Puerto Rico, and the United States Virgin Islands. The team at Gustan Cho Associates and its DBA subsidiaries have over 300 wholesale lenders. Dozens of our lending partners are wholesale lenders with no lender overlays on FHA, VA, USDA, and conventional loans.
The team at Gustan Cho Associates only goes by agency lending guidelines and have zero lender overlays. Our pre-approvals will close due to our smooth and streamlined verification and mortgage process. With a network of 300 wholesale lending partners, we have dozens of wholesale lenders of government and conventional loans with no overlays and hundreds of different mortgage options on non-QM and alternative lending mortgage loan programs. The team at Gustan Cho Associates is available seven days a week, evenings, weekends, and holidays.
FAQ – VA Loans With No Credit Scores Mortgage Guidelines
What Are VA Loans, and How Do They Differ from Other Loan Programs?
VA loans are mortgage loans offered to eligible veterans, active-duty service members, and surviving spouses, backed by the Department of Veterans Affairs. They stand out for their flexible mortgage criteria compared to other loan programs, accommodating borrowers with no established credit scores and high debt-to-income ratios.
Can I Qualify for a VA Loan with No Credit Scores or a Low Credit Score?
Yes, VA loans have no strict minimum credit score requirements. Some lenders, like Gustan Cho Associates, even offer VA loans to borrowers with credit scores in the 500s, provided they receive an approved/eligible status from the automated underwriting system.
Why Do Some Lenders Have Credit Score Requirements for VA Loans Despite the VA Not Mandating Them?
While the VA does not impose strict credit score requirements, individual lenders may implement their criteria as a risk management strategy. Lenders may perceive lower credit scores as presenting greater financial risk and choose to set additional criteria to mitigate potential losses or align with their underwriting standards.
What are VA Lender Overlays, and How Do they Affect Eligibility?
VA lender overlays are additional requirements individual lenders impose within the VA Agency Guidelines. Despite the absence of a minimum credit score requirement in VA guidelines, some lenders may have overlays, making it crucial for borrowers to choose lenders like Gustan Cho Associates, with no overlays on VA loans.
Can I Qualify for a VA Loan with a Credit Score as Low as 500?
Yes, borrowers can still be eligible for a VA loan with a credit score as low as 500, as long as they meet the basic VA agency guidelines and receive an approved/eligible status from the automated underwriting system. Some lenders may impose higher credit score requirements, but Gustan Cho Associates strictly follows VA Agency Guidelines.
Are There Debt-to-Income Ratio Requirements for VA Loans?
While the VA does not enforce specific minimum debt-to-income ratio requirements, individual lenders often set their guidelines. Gustan Cho Associates has successfully processed VA loans with debt-to-income ratios exceeding 60%, offering more flexibility than many other lenders.
How Can I Obtain a Certificate of Eligibility for a VA Loan?
Borrowers with a Certificate of Eligibility (COE) from the Department of Veterans Affairs can apply for VA loans. Gustan Cho Associates specializes in helping borrowers obtain their COE promptly by handling the necessary procedures.
What Are the Basic VA Eligibility Requirements?
VA loans are for owner-occupant homes only, available to U.S. Armed Services veterans with a Certificate of Eligibility. The basic eligibility requirements include 100% financing, the ability to roll upfront VA Funding Fee into the loan balance, no closing costs, and specific waiting periods after bankruptcy or foreclosure.
This Guide on VA Loans with No Credit Scores Mortgage Guidelines Was PUBLISHED and UPDATED on September 25, 2026.
Ready To Start Your Homeownership Journey? Call Us Now!