When are two appraisals required?
Two full appraisals are not standard for most mortgages. A second appraisal may be required for certain FHA property flips, some higher-priced mortgage loans, qualifying FHA 203(k) transactions, or when a lender or investor has a documented valuation requirement. A lender generally cannot order another appraisal simply because the first value was lower than expected.
Why Would a Mortgage Require a Second Appraisal?
Generally, a mortgage would not require a second appraisal. However, a second appraisal may be necessary due to certain loan program requirements, a deficient first appraisal, or a lender or investor review.
Program Requirement
Certain mortgage programs may require a second appraisal under specific circumstances. An example is the FHA property-flipping rule.
Appraisal Deficiency or Review
A second appraisal may be necessary if the first appraisal is deficient and additional review is warranted. A second appraisal would not be warranted simply because the borrower, seller, real estate agent, or lender is dissatisfied with the appraisal value.
Lender- or Investor-Specific Requirements
There may be specific valuation requirements for jumbo loans, portfolio loans, and other mortgage programs. Under certain guidelines, a lender may require a second appraisal or another type of collateral review. These requirements are specific to certain lenders or investors and do not apply to every mortgage.
When Lenders or Investors Require Additional Appraisal Review
A property’s high price or unusual design does not automatically require two full appraisals. However, the lender, mortgage program, appraisal review system, or investor purchasing the loan may require additional valuation support before approving the property. Additional review may be requested when:
- The property is unique, rural, mixed-use, or difficult to compare with recent sales.
- The appraised value is substantially higher than the contract price or surrounding property values.
- The appraisal contains unsupported adjustments, inconsistent information, or weak comparable sales.
- The property falls outside the lender’s standard eligibility requirements.
- An automated collateral-review system identifies an elevated valuation risk.
- The loan amount, program, or secondary-market investor requires additional valuation documentation.
- The lender applies an appraisal overlay that is stricter than the minimum agency guideline.
What We Check When a Mortgage May Require Two Appraisals
When a mortgage transaction raises the possibility of a second appraisal, the Gustan Cho Associates loan team first determines which rule applies and what type of valuation the lender actually requires. We do not assume that every appraisal concern requires two complete appraisal reports. Our review generally includes:
- The mortgage program: FHA, conventional, VA, USDA, jumbo, non-QM, and HPML transactions may have different appraisal requirements.
- The seller’s acquisition date: We review the seller’s deed and available property records to determine when the seller obtained legal ownership.
- The purchase-contract date: For rules based on a resale period, we confirm the date on which all parties executed the purchase agreement. The application date, appraisal date, and scheduled closing date may not control the calculation.
- The seller’s acquisition price: This amount is compared with the borrower’s contract price when evaluating a potential rapid resale or property-flipping requirement.
- The borrower’s purchase price: A significant increase does not automatically establish fraud or require another appraisal, but it can trigger additional review under certain programs.
- Available exemptions: We check whether an FHA property-flipping exception, HPML exemption, or another program-specific exception applies before treating a second appraisal as mandatory.
- The valuation product ordered: We confirm whether the lender requested a second full appraisal, a desk review, a field review, an appraisal update, an automated valuation model, or a reconsideration of value. These are not interchangeable.
- Responsibility for the fee: We decide who. The borrower, lender, seller or another party. May cover the cost based on the program rules and what the disclosures require.
- Appraiser availability and closing deadlines: A second appraisal can impact the closing timeline especially if the property is in an area has high value is complex or is in a location where qualified appraisers are limited.
A reconsideration of value often called an ROV is not an appraisal. It is a formal request asking the lender and appraiser to consider possible factual errors, omitted comparable sales, or other relevant information in the original report. Similarly a desk review or field review does not always mean a full second appraisal is needed. By figuring out the requirement early our team can explain why more valuation work was asked for who might be responsible, for the cost and whether the closing deadline should change.
An Appraisal Review Is Not Always a Second Appraisal
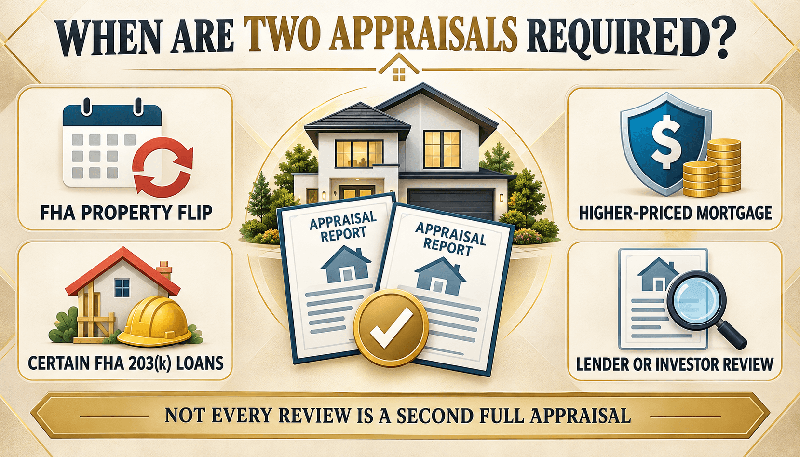
Additional valuation work does not necessarily require another appraiser to complete an entirely new appraisal. Depending on the concern, the lender may order:
- An automated valuation model, or AVM
- A desk review of the original appraisal
- A field review that includes an exterior inspection
- Additional comparable sales or corrections from the original appraiser
- A full second appraisal was completed as a separate assignment
A second full appraisal is generally used when a review cannot adequately resolve questions about the property’s value, condition, marketability, or eligibility.
What Are Lender Appraisal Overlays?
A lender appraisal overlay is a rule that a lender or the investor buying the mortgage adds on top of the basic guidelines. These rules often go beyond what FHA, VA, USDA Fannie Mae or Freddie Mac say is required. For instance while agency rules might allow one appraisal, a specific lender or investor could ask for a field review or even a second appraisal. This usually happens when the property is unusual or when the valuation seems riskier, than normal. Borrowers should ask whether the additional valuation is a program requirement, an automated underwriting condition, or a lender-specific overlay. They should also confirm whether an additional fee will apply before the work is ordered. Fannie Mae says lenders must check appraisal reports carefully. They need to make sure the report has all the information that the data is correct that the comparable sales are strong and relevant and that the final value conclusion is well supported. Freddie Mac likewise permits collateral-assessment requirements beyond the minimum report type when additional support is necessary. These review requirements do not mean that every expensive or unusual property needs two appraisals.
FHA Two-Appraisal Requirements for Property Flips
FHA maintains specific requirements for properties acquired by a seller and resold within a short period. For FHA purposes, the seller’s acquisition date refers to the date the seller obtains legal ownership of the property. The resale date is the date on which all parties sign the new sales contract that will result in an FHA-insured mortgage.
FHA 90-Day Property-Flipping Rule
Generally, a property resold within 90 days of the seller’s acquisition is not eligible for FHA-insured financing unless the transaction meets an FHA property-flipping exemption. Ordering a new appraisal does not eliminate the 90-day restriction.
FHA 91-to-180-Day Second-Appraisal Rule
FHA guidelines say you need a second appraisal if you resell a property between 91 and 180 days after buying it and if the selling price is at least double what you paid for it. A resale price that is 100% above the acquisition price means it is twice what the seller originally paid. For example:
- Seller’s purchase price: $120,000
- New contract price: $240,000
- Resold on Day 120
The $240,000 resale price is 100% above the seller’s $120,000 acquisition price. Since the resale occurred within the 91- to 180-day time frame, a second appraisal will be required unless an FHA exemption applies. The FHA test compares the resale price with the seller’s acquisition price. The requirement is not waived due to additional seller expenses, such as renovations, holding costs, or commissions.
FHA Property-Flipping Exceptions
FHA’s property-flipping time restrictions do not apply to certain exempt transactions. The exceptions include:
- Sales where the property was purchased by a relocation agency or employer and is subsequently sold as part of an employee relocation
- HUD REO resales
- Sales by other agencies of the U.S. government
- Sales by certain HUD-approved nonprofit organizations
- Sales of inherited property
- Sales by government-sponsored enterprises and state- or federally chartered financial institutions
- Sales by state or local government agencies
- Certain properties located in Presidentially Declared Major Disaster Areas when the applicable FHA exception is in effect
FHA property-flipping restrictions do not apply to a builder selling a newly built home or a builder constructing a home for a borrower planning to use FHA-insured financing. The lender must determine whether the transaction qualifies for an FHA exemption.
Who Pays for the Second FHA Appraisal?
Under FHA’s 91-to-180-day property-flipping rule, the borrower cannot be charged for the required second appraisal. Who ultimately pays depends on the transaction and the lender’s arrangements, but the FHA prohibits passing the cost of the required second appraisal to the borrower.
Need Help With a Two-Appraisal Mortgage Requirement?
Complete an application or send your property scenario. We will review the application details, appraisal requirement, loan program, property history, property value concerns and next steps, toward closing.What Happens If the Second FHA Appraisal Is Lower?
Under the FHA property-flipping rule, if the second appraisal is more than 5% lower than the first appraisal, FHA requires the lower value to be used when determining the property’s adjusted value. For example:
- First appraisal: $300,000
- Second appraisal: $280,000
The second appraisal is approximately 6.7% lower than the first. Because the difference is more than 5%, the lower amount, $280,000, must be used. This lower value can affect the maximum loan amount, the required cash investment, and whether the purchase price needs to be renegotiated.
Can a Lender Order Another Appraisal Because the First Value Is Low?
A lender cannot order another appraisal solely because the first value is lower than expected. Mortgages subject to Fannie Mae’s Appraiser Independence Requirements may use a subsequent appraisal in the following situations:
- There are documented indications that the original appraisal is inaccurate, lacks credibility, or does not comply with applicable legal or professional standards.
- The subsequent appraisal is obtained under a written, established underwriting or quality-control process.
- A subsequent appraisal is required by law.
When multiple appraisals are available, Fannie Mae requires the lender to follow a policy of selecting the most reliable appraisal, not simply the one with the highest value. FHA also prohibits ordering another appraisal merely to obtain a higher value or avoid required repairs. A subsequent appraisal may be permitted when a documented material deficiency cannot be resolved under FHA requirements.
Appraisal Independence and Value Shopping
Appraisers must be allowed to develop an independent opinion of value. Lenders, loan officers, brokers, borrowers, sellers, and real estate professionals cannot improperly pressure an appraiser to reach a predetermined value. Appropriate communication is allowed. Under federal valuation-independence rules, an appraiser may be asked to:
- Consider additional relevant property information.
- Provide further explanation or support for a conclusion.
- Correct factual errors in the appraisal
The rule prohibits coercion or improper influence. It does not prohibit legitimate communication about property information or factual errors.
Who Chooses the Mortgage Appraiser?
Generally, neither borrowers nor people involved in mortgage production select the appraiser assigned to perform a lender-required conventional appraisal. For Fannie Mae loans, the lender or an appropriately independent authorized party is responsible for the appraisal engagement. Loan officers, mortgage brokers, borrowers, and real estate agents cannot select the appraiser for a specific transaction in a way that violates appraisal-independence requirements. This does not prevent requests for factual corrections, additional property information, or clarification of the appraisal.
FHA 203(k) Appraisals: When Is an As-Is Appraisal Required?
Every FHA 203(k) transaction requires an appraisal that estimates the property’s after-improved value. The appraiser develops this value under the assumption that the proposed repairs and improvements have been completed. FHA does not, however, automatically require two appraisal reports. Whether the lender also needs a separate as-is appraisal depends on the transaction.
FHA 203(k) Purchase Transactions
For a purchase, the lender generally establishes the property’s Adjusted As-Is Value using the lesser of:
- The purchase price, minus any inducements to purchase, or
- The property’s as-is market value, when an as-is appraisal is performed.
A separate as-is appraisal may not be necessary when the lender can use the adjusted purchase price. However, the lender must obtain an as-is appraisal when needed to comply with the FHA’s property-flipping requirements.
FHA 203(k) Refinance Transactions
For a refinance, the lender must obtain an as-is appraisal when:
- The existing debt on the property plus the cost of repairs exceeds the property’s after-improved value; or
- The borrower acquired the property less than 12 months before the FHA case number assignment date, subject to FHA’s applicable exception for property acquired through a gift or inheritance from a family member.
If the borrower acquired the property at least 12 months earlier and the existing debt plus repair costs does not exceed the after-improved value, FHA permits the lender to establish the Adjusted As-Is Value using the existing debt plus qualifying fees associated with the new mortgage. The lender may instead choose to obtain an as-is appraisal.
Do As-Is and After-Improved Values Require Two Reports?
Not necessarily. The presence of both an as-is value and an after-improved value does not, by itself, mean that two separate appraisal reports are required. Every 203(k) transaction requires the after-improved appraisal. A second, separate as-is appraisal is required only when FHA’s purchase or refinance rules call for one, or when the lender obtains one as permitted under the program. When both appraisals are required, they are treated as separate appraisal assignments and reports. These requirements reflect the August 12, 2026, version of HUD Handbook 4000.1 and HUD’s FHA 203(k) calculator guidance. Lender overlays may impose additional requirements.
Additional FHA Situations That May Require a Second Appraisal
FHA recognizes circumstances other than property flipping in which another appraisal may be necessary.
Appraisal Transfer or Portability Issues
If a borrower changes FHA lenders, the original appraisal is generally transferable with the FHA case under HUD’s appraisal-transfer requirements. The receiving lender cannot simply have the original appraisal readdressed to itself. If the receiving lender identifies a material deficiency, another appraisal may be permitted when FHA’s requirements for a subsequent appraisal are met.
Expired Appraisal
FHA appraisals have specific validity periods. In certain circumstances, an allowable appraisal update may extend the original appraisal’s validity. If the appraisal is no longer valid and cannot be used or extended under FHA guidelines, a new appraisal may be necessary.
Material Appraisal Problems
An FHA lender may not order a subsequent appraisal simply to obtain a higher value. For the original mortgagee, a subsequent appraisal may be requested if the Direct Endorsement underwriter determines that the first appraisal is materially deficient and the original appraiser is unable or unwilling to resolve the deficiency. The lender must document the deficiency in the mortgage file and is responsible for the cost of the subsequent appraisal when required under these circumstances. FHA’s current systems also address second-appraisal situations involving certain appraisal transfers, appraisal expiration, property flipping, and qualifying 203(k) transactions.
How Much Can a Second Appraisal Delay Closing?
There is no predetermined amount of time that a second appraisal will add to a mortgage closing. Timing depends on:
- Appraiser availability
- Property location
- Property complexity
- The type of appraisal required
- Turnaround time for the report
- Whether the second valuation creates additional underwriting conditions
A straightforward appraisal may not add much time to the process. A unique property, limited comparable sales, or a significant difference between appraisals may require additional review. Borrowers purchasing a property that clearly falls under FHA property-flipping rules should identify the second-appraisal requirement early in the mortgage process.
Hypothetical FHA Property-Flipping Example
Imagine an investor buys a house for one hundred twenty five thousand dollars. Then the investor signs a deal to sell that house to an FHA buyer for two hundred fifty five thousand dollars.
- Sellers acquisition price: $125,000
- FHA buyers contract price: $255,000
- Resale date: Day 120
- Increase over acquisition price: 104%
The sale occurs between days 91 and 180, and the resale price is 104% above the seller’s acquisition price. Assuming no FHA property-flipping exemption applies, a second appraisal by another appraiser is required. Suppose the appraisals are:
- First appraisal: $255,000
- Second appraisal: $238,000
The second appraisal is approximately 6.7% lower than the first. Because the second appraisal is more than 5% lower, FHA requires the lower value of $238,000 to be used for the transaction. The borrower cannot be charged for the second appraisal required under the FHA property-flipping rule.
Final Thoughts on Two Appraisals
While two appraisals are not standard for every mortgage, a second appraisal should have a valid program, investor, underwriting, quality-control, legal, or valuation reason.
FHA has a specific second-appraisal rule for certain property flips. When a property is resold between 91 and 180 days for 100% or more above the seller’s acquisition price, a second appraisal is required unless an FHA exemption applies. The borrower cannot be charged for that required appraisal. If the second appraisal is more than 5% lower than the first, the FHA requires that the lower value be used.
Other valuation rules may still apply to jumbo, portfolio, conventional and rehabilitation mortgages. You should know why an extra appraisal is needed and whether the rule comes from the mortgage program, investor or lender.
Frequently Asked Questions About Two Mortgage Appraisals
Is a Second Appraisal the Same as a Home Inspection?
No. An appraisal calculates the property’s market value. Checks whether it satisfies the mortgage program’s property rules. A home inspection gives you a look at the home’s condition, systems and possible repair needs. One does not replace the other.
Can I Waive a Lender-Required Second Appraisal?
Generally no. If the second appraisal is demanded by the mortgage program, lender, investor or underwriting team it must finish before the loan can get approval. Waiving an appraisal contingency, in the purchase contract does not remove the lender’s valuation rules.
Will I Receive Copies of Both Appraisal Reports?
For a typical mortgage secured by a first lien on a residential property, borrowers are entitled to receive copies of the appraisals and other written valuations obtained by the lender. The lender generally must provide them promptly after completion and no later than three business days before closing. The borrower cannot be charged for receiving copies, although the lender may charge a reasonable fee for obtaining the appraisal or valuation.
Can a Buyer Renegotiate or Cancel After a Low Second Appraisal?
A low second appraisal does not automatically cancel the purchase contract. Depending on the contract and loan program, the buyer may be able to ask the seller to reduce the purchase price, Pay part of the appraisal gap from personal funds, Request a reconsideration of value when credible supporting information is available,
Modify the loan structure, Terminate the contract under an applicable appraisal or financing contingency.
Does a Higher Second Appraisal Allow the Buyer To Borrow More?
Usually not. For a purchase mortgage, the lender generally calculates the loan amount using the lower of the purchase price or the property value the lender accepts. A second appraisal higher than the contract price typically does not increase the borrower’s maximum purchase loan amount or provide cash back at closing.
Why Can Two Appraisers Give the Same Property Different Values?
An appraisal is a supported professional opinion rather than a guaranteed number. Two qualified appraisers may select different comparable sales, make different market-supported adjustments, or evaluate the property’s condition and features differently. A difference between two appraisals does not automatically mean that one appraiser made an error. The lender reviews the reports to determine which value is best supported and acceptable under the applicable mortgage guidelines.
This article about “When Are Two Appraisals Required for a Mortgage?” was updated on September 17th, 2026.