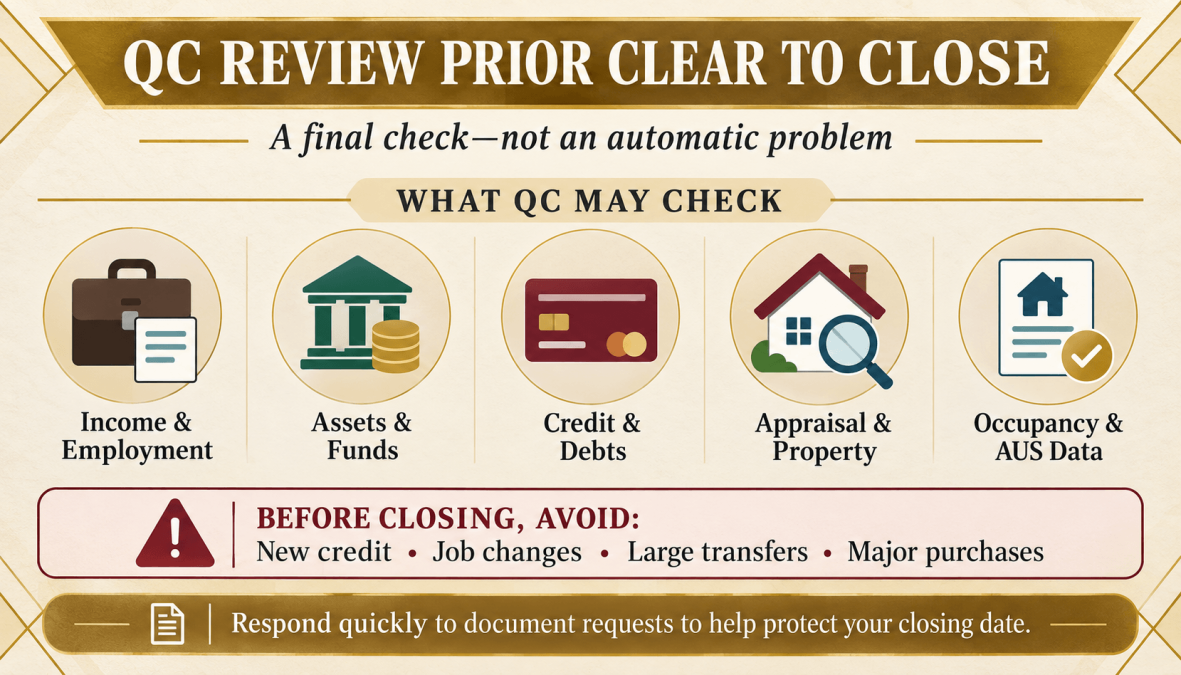
A mortgage QC review prior clear to close is an additional check of selected loan information before closing or funding. The reviewer may examine income, employment, assets, credit, occupancy, appraisal information, and data entered into the automated underwriting system. Selection for QC does not automatically mean the loan has a problem, but missing documents or material changes can create new conditions, delay closing, or affect final approval.
What Is a Mortgage QC Review?
A mortgage quality-control review confirms that information used to approve a loan is correct, complete, and consistent with the applicable underwriting standards and guidelines. A QC review prior to the Clear to Close may refer to the lender’s final internal review or may refer to a formal pre-funding QC review with specific parameters established by the lender.
Final Underwriting Versus Prefunding QC
Final underwriting and prefunding quality control are related but not the same process. Final underwriting is part of the lender’s normal approval process. Prefunding QC is a separate review used to identify errors, missing documentation, inconsistent information, or unsupported underwriting decisions before the loan closes or is acquired by an investor.
Not every final lender review is a formal prefunding QC review. Some lenders use terms such as final review, senior underwriting review, compliance review, and QC review interchangeably. Borrowers should ask their loan officer which type of review is being performed and whether any documents or conditions remain outstanding.
What Happens During Final Underwriting?
During final underwriting, the underwriter confirms that the borrower and property meet the applicable loan requirements. The underwriter reviews the documents supporting the borrower’s income, employment, assets, credit, debts, occupancy, and property value.
The underwriter also confirms that:
- All underwriting conditions have been satisfied
- Information entered into the automated underwriting system matches the supporting documents
- The borrower has enough verified funds for closing and any required reserves
- The appraisal, title, insurance, and other property documents are acceptable
- No material changes have affected the borrower’s eligibility
Once the remaining conditions have been cleared, the underwriter may issue the Clear to Close. However, the lender may still need to complete employment verification, prepare closing documents, confirm final figures, or perform another required review before closing or funding.
How Is Prefunding QC Different?
A formal prefunding QC review is a separate quality-control function. Its purpose is to identify defects before the lender closes, purchases, or delivers the mortgage.
For loans sold to Fannie Mae, the lender must maintain a written prefunding QC plan and review a sample of its loans before closing or acquisition. The review must be conducted by people who were not involved in originating, processing, or underwriting the loan being reviewed. This separation gives the lender an independent assessment of the original underwriting decision.
Being selected for prefunding QC does not automatically mean that the underwriter found a problem. A loan may be selected based on the lender’s sampling procedures, production channels, loan volume, product mix, or areas considered to present greater risk.
FHA-approved mortgagees must also follow HUD’s applicable quality-control requirements. However, this does not mean that every FHA loan receives a separate pre-closing QC review. The lender’s approved procedures determine which loans are selected and what the review covers.
Full-File Versus Component QC Reviews
A prefunding QC review may cover the entire mortgage file or focus on one part of the loan.
Full-File QC Review
A full-file review is a comprehensive evaluation of the underwriting decision. For a Fannie Mae loan, the review may include:
- Data entered into the automated underwriting system
- Borrower identity and Social Security number
- Income calculations and supporting documents
- Employment documentation and required verification
- Assets needed for closing and reserves
- Credit history and qualifying liabilities
- Appraisal or other collateral documentation
- Required mortgage insurance
- Intended occupancy
The reviewer compares the information used to approve the loan with the documents in the file. Inconsistent data, unsupported calculations, missing documents, or information that changed after approval may require further review.
Component QC Review
A component review focuses on a specific area, such as:
- Income and employment
- Assets and funds to close
- Credit and liabilities
- Occupancy
- Appraisal or property eligibility
- Automated underwriting system data
A component review is narrower than a full-file review. Lenders may use component reviews to examine a higher-risk part of the loan or to confirm that a particular internal control is functioning correctly.
When Does Prefunding QC Occur?
The timing depends on the lender’s procedures. Fannie Mae requires prefunding QC to occur early enough for the lender to complete the review and correct any defects before closing or acquisition. The file must also contain enough documentation for the reviewer to evaluate the selected information.
Some lenders complete the review before issuing the Clear to Close. Others issue the Clear to Close after underwriting conditions are satisfied, but complete another review before signing, funding, or delivering the loan.
If the reviewer finds missing documents, conflicting information, a calculation error, or a material change in the borrower’s circumstances, the file may return to underwriting. The lender may request updated documents or impose additional conditions. This does not automatically mean the mortgage will be denied. The loan may proceed if the issue is documented, corrected, and the borrower continues to meet the applicable requirements.
When Does QC Happen?
A mortgage QC review may occur after most underwriting conditions have been cleared, immediately before the lender issues the Clear to Close, or after the Clear to Close but before signing or funding. The exact timing depends on the lender, loan program, and type of review being performed.
The phrase “QC Review Prior Clear To Close” typically refers to an internal or formal prefunding review conducted before the lender authorizes closing. At this point, the file should contain sufficient documentation for the reviewer to evaluate the underwriting decision and identify any missing, inconsistent, or unsupported information.
Some lenders complete QC earlier in the process, so there is enough time to correct problems before the scheduled closing. Others conduct a final review after the underwriter has cleared the main conditions. If QC identifies an issue, the file may return to underwriting for updated documents, corrected calculations, or additional conditions.
A lender may also complete certain verifications after issuing the Clear to Close, but before the loan closes or funds are disbursed. These may include:
- Final employment verification
- Updated credit or debt monitoring
- Confirmation of funds needed for closing
- Review of revised closing figures
- Updated appraisal, title, insurance, or property documents
- Confirmation that no material information has changed
Receiving a Closing Disclosure does not necessarily mean every QC or final verification has been completed. The Closing Disclosure provides the final loan terms and closing costs, but the lender must still confirm that the borrower and property remain eligible through closing and funding.
Borrowers should respond promptly to document requests and report any changes to employment, income, debts, assets, occupancy, or the purchase contract. Prompt communication gives the lender more time to review and resolve an issue before the closing date.
Can QC Create New Conditions or Delay Closing?
Yes. A QC review can identify an issue that must be resolved before the lender allows the mortgage to close or fund. QC does not normally create new loan-program requirements. Instead, it may uncover missing documents, inconsistent information, calculation errors, or changes that require the underwriter to add or reinstate a condition.
A QC review prior clear to close may result in requests for:
- Updated pay stubs or employment verification
- Documentation explaining a large bank deposit or transfer
- Evidence of sufficient funds for closing and required reserves
- Information about a newly opened account or a monthly debt
- Corrected income, asset, or debt calculations
- Updated appraisal, title, insurance, or property documents
- An explanation of conflicting information in the loan file
- Confirmation of the borrower’s intended occupancy
- Revised purchase contract terms or seller-credit documentation
A new condition does not automatically mean the mortgage will be denied. Many conditions can be cleared by providing the requested document, correcting an error, or offering a satisfactory explanation to the underwriter.
However, QC can delay closing when the lender needs additional documentation, a third-party verification, an appraisal revision, or another underwriting review. The delay may be longer when the borrower’s employment, income, debts, assets, occupancy, or property eligibility has materially changed.
A loan may still be denied after a Clear to Close if new information shows that the borrower or property no longer meets the applicable requirements. Examples include losing qualifying income, taking on debt that raises the debt-to-income ratio beyond an acceptable level, no longer having enough verified funds to close, or changing the intended use of the property.
Borrowers can reduce delays by responding quickly, providing complete documents, and notifying their loan officer before changing jobs, opening credit, moving large amounts of money, making a major purchase, or changing the purchase contract. The sooner the lender is notified of a change, the more time the mortgage team has to determine whether additional documentation or underwriting is required.
How Long Does a Mortgage QC Review Take?
A limited review may be completed quickly, while a full-file review or new conditions can take longer.
After considering each lender’s process and the type of review, review complexity, and additional conditions, a reviewer may take from 24 hours to many days to complete a review.
A limited-component review may take a day. A full-file review, or even a review requiring additional documentation, will take much longer.
Fannie Mae requires lenders to ensure that reviews are conducted early enough to resolve any potential issues before closing, but has not established a uniform review turnaround time.
What Borrowers Should Avoid Before Closing
When you have an approved mortgage, you must keep your financial situation as stable as possible until your mortgage closes.
New Credit
Unless you’re advised otherwise by your loan officer, avoid applying for any new credit. New obligations, like credit cards, loans, new mortgages, etc. A new required monthly payment can increase DTI, while an inquiry or new account may affect credit eligibility or trigger additional review.
Job Changes
A job change does not necessarily mean your mortgage is in jeopardy, but at a minimum, you will have to answer some follow-up questions.
For qualifying employment income, the verbal VOE is generally required within 10 business days before the note date. Business existence for self-employed income generally has a 120-calendar-day window. Permitted alternatives and DU validation messages can modify how the requirement is satisfied.
A change in your employment status will likely mean your lender must reevaluate your qualifying income.
Moving Money
Transfers of your own money are generally not an issue; lenders will ask for the reason for the transfer and the source of the funds.
Be prepared to explain your transfers to the loan officer.
Large Purchases
Buying with cash may reduce the funds available for your mortgage. Additionally, a new purchase can add an unplanned new monthly expense.
To qualify for a mortgage for a given purpose, e.g., as a primary residence, the terms and conditions of a mortgage for a different purpose would need to change. For instance, a mortgage approved for a primary residence would not be acceptable for a second home, a vacation home, or an investment property.
Changing Occupancy Plans
Inform the lender of the new intended property use.
Approval of a loan for the purchase of a primary residence does not permit the borrower to use the property for a second home or as an investment property without the lender’s evaluation. Underwriting and eligibility standards may differ.
What We Have Seen in Actual Mortgage Files
After working with borrowers who had complex income, credit, bankruptcy, and underwriting situations, our team has seen how a final review can uncover issues even after most loan conditions have been cleared. A QC review prior clear to close does not necessarily mean the loan is in trouble. It often means the lender needs to verify that the approved information remains accurate before closing or funding.
The following examples are based on situations we have encountered in mortgage files. Identifying details have been omitted, and every loan outcome depends on the borrower’s documentation, loan program, and lender requirements.
Employment Changed Before Closing
We have seen lenders complete a final employment verification and learn that the borrower recently changed jobs, stopped working, or had a change in hours or compensation.
A job change does not automatically cause a denial. However, the underwriter may require an offer letter, an employment contract, an updated pay stub, written verification of employment, or confirmation of the borrower’s start date. The lender must then determine whether the new income is stable, eligible, and sufficient to support the mortgage payment.
New Debt Appeared During the Final Review
We have also seen borrowers finance a vehicle, open a new credit account, or increase a credit card balance shortly before closing. When the lender discovered the new monthly payment, the file had to return to underwriting so the borrower’s debt-to-income ratio could be recalculated.
The loan could continue if the borrower still met the applicable requirements. If the new debt caused the DTI to exceed the lender’s limit, the borrower might need to reduce or pay off the obligation, restructure the transaction, or qualify for a different loan program.
Money Was Transferred Between Accounts
Transfers between a borrower’s own accounts are common, but they can create questions when the lender cannot see the complete paper trail. We have seen files delayed because funds appeared in the account used for closing without documentation showing their source.
In many cases, the issue was resolved by providing statements from both accounts and proof of the transfer. Problems become more serious when the source cannot be verified or when the funds came from an ineligible source.
Property Information Changed
Final reviews can also uncover property-related issues. We have seen appraisal revisions, repair requirements, insurance changes, title problems, and changes to the purchase contract that require sending a file back for additional review.
A minor correction may have little effect on the approval. A lower appraised value, an unresolved safety issue, a title defect, or a change in property eligibility may require additional conditions or changes to the loan structure.
Information Did Not Match the Loan Application
A lender may find that information in a public record, credit report, bank statement, employment verification, or other document does not match the information provided on the mortgage application.
The borrower should provide an honest explanation and supporting documentation as quickly as possible. A mistake or misunderstanding may be correctable. Undisclosed debt, inaccurate occupancy information, or a material misrepresentation can place the approval at risk.
Our experience has shown that fast communication and complete documentation give the mortgage team the best opportunity to resolve a last-minute issue. Borrowers should inform their loan officer of any changes to their finances, employment, property, or contracts before the lender discovers them during the final review.
Final Thoughts on QC Review Prior to Closing
A QC review prior clear to close does not indicate a problem with the file. It may be a routine review by the lender or part of a prefunding quality-control program.
The review may be for the entire file or for given sections for income, employment, assets, credit, occupancy, or property.
Last-minute issues can be minimized by borrowers through stable employment and finances, avoidance of large new transactions, documentation of large transfers, and notification of the loan officer of all significant changes prior to closing.
The lender’s finalization of the review of the information and satisfaction of the remaining conditions allows the loan to proceed to closing and funding.
Frequently Asked Questions About Mortgage QC Review Prior Clear to Close:
Does a Mortgage QC Review Require Another Credit Pull?
- It can. During a QC review prior clear to close, the lender may refresh the borrower’s credit or check for newly opened accounts, additional balances, or recent inquiries. This does not always involve another hard credit inquiry. The type of credit check depends on the lender’s procedures and the loan program. Borrowers should avoid applying for credit or increasing existing balances until the mortgage has closed and been funded.
Can QC Affect a Locked Mortgage Interest Rate?
- Quality control does not normally change a valid locked interest rate. However, if QC identifies an issue that delays closing beyond the lock expiration date, the borrower may need a rate-lock extension. Depending on the lender and the reason for the delay, an extension could involve a fee. Changes to the loan amount, property use, credit profile, or other qualifying details may also require the lender to review the original pricing.
Can a Borrower Speak Directly With the QC Department?
- Usually, borrowers do not communicate directly with the quality-control reviewer. Questions and document requests typically pass through the loan officer, processor, or underwriter. This structure allows the lender to track conditions and prevents conflicting information from entering the file. Borrowers should respond promptly to their regular loan contact and provide exactly what is requested.
Is Prefunding QC the Same as a Post-Closing Mortgage Audit?
- No. Prefunding QC takes place before the loan closes and funds are disbursed. Its purpose is to confirm that the file meets the lender’s and the loan program’s requirements before the transaction is completed. A post-closing audit is conducted after closing and reviews the completed loan for accuracy, compliance, documentation, and potential defects. A loan may be selected for either review, both reviews, or neither, depending on the lender’s quality-control plan.
Can a Mortgage Close the Same Day QC Is Cleared?
- It may be possible, but QC clearance alone does not guarantee a same-day closing. The lender must also confirm that underwriting conditions are satisfied, required disclosures have been completed on time, closing documents are ready, and funds can be released. The title company, settlement agent, and applicable recording office must also be prepared. Borrowers should confirm the closing schedule with their loan officer before making moving or travel arrangements.
Can QC Be Repeated if the Closing Date Is Postponed?
- Yes. If closing is postponed, the lender may refresh or repeat parts of the review. Credit information, employment verification, bank statements, pay stubs, appraisal documents, and other items can become outdated. The lender may also check for financial or employment changes that occurred after the original review. A repeated check does not necessarily mean there is a problem; it may be required to confirm that the borrower and property still qualify.
This article about “Mortgage QC Review Prior Clear to Close: What to Expect” was updated on September 16th, 2026.
Stuck in QC? Get a Second Opinion Fast
If your loan is delayed before Clear to Close, we’ll review what’s missing and help you respond with the right documentation so you can move forward quickly