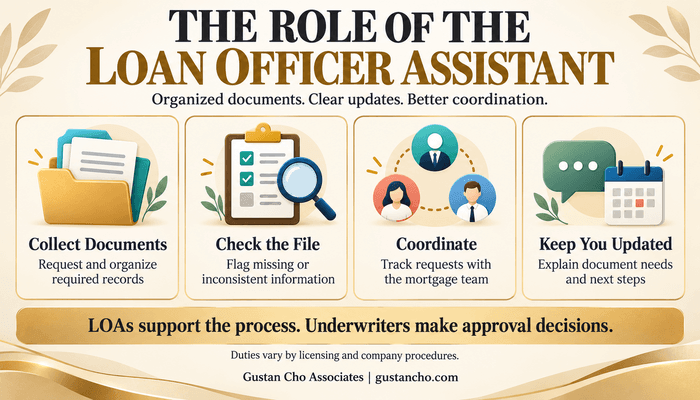
The role of the loan officer assistant is to help organize and manage your mortgage file to ensure a smooth loan process. An LOA may collect documents, check the application for missing information, follow up on outstanding items, and coordinate with the loan officer and processor. Duties depend on company procedures, the assistant’s licensing status, and state requirements. Catching incomplete documents or inconsistent information early can help reduce avoidable delays before underwriting and closing.
What Is a Loan Officer Assistant?
A loan officer assistant, or LOA, works with the loan officer and helps connect you with the team managing your mortgage file.
The role of the Loan Officer Assistant can be different depending on the company. Some LOAs help with your application and prepare your file, then pass it to a processor. Others stay involved through underwriting and closing, working with the processor as your loan moves forward.
Your LOA might be your main contact for regular updates, or the processor could take over that role. Be sure to ask who will answer your questions at each step and if your main contact will change after you submit your application.
Loan Officer Assistant vs. Loan Officer, Processor, and Underwriter
Loan officer: Reviews your financing requirements, explains the loan programs, rates and terms, and helps to structure the mortgage. Handles the origination activities within the scope of their license or registration. Loan Officer Assistant: Provides the assigned support (e.g., chasing document requests, checking application info is complete, communicating routine file updates, etc.). Any queries that require mortgage advice should be referred to the appropriately authorized professional. Mortgage processor: They prepare and manage the underwriting file, arrange the required verifications and third-party documents, and track conditions. They collate the responses for the underwriter to review. Submitting a response doesn’t mean the condition is accepted. Mortgage underwriter: The underwriter evaluates the borrower’s credit, qualifying income, assets, and property information against applicable loan-program and lender requirements. They make the underwriting decision and identify any conditions that must be satisfied for approval. Responsibilities can overlap, and the borrower’s primary contact may change as the file progresses. Company procedures determine how these duties are divided.
How an LOA Prepares Your Mortgage File
Checking the Application Against Supporting Records
The LOA checks the details in your application against the records you provided, such as your job, income, assets, debts, and housing. Dates, amounts, and other information should match. If something does not line up, the assistant may ask you to explain so your application is accurate.
Collecting the Documents That Apply to You
The documents you need to provide depend on your loan program, income, and finances. You might be asked for paystubs, W-2s, bank statements, ID, or tax returns. Sometimes, you may also need to give bankruptcy papers, divorce decrees, or other documents if they apply to you. The LOA keeps track of which documents you have sent and makes sure they are clear and complete.
Flagging Discrepancies for the Appropriate Review
Questions about qualifying income, acceptable funds, or program eligibility need review by the team member responsible for that determination. The LOA flags the issue for the loan officer or processor and helps gather any requested clarification. This allows the mortgage team to address unresolved information before relying on it for the loan.
How an LOA Helps With Underwriting Conditions
Once your mortgage file is reviewed, the underwriter might ask for more documents or clarification. These requests are called underwriting conditions and need to be handled before your loan can be approved. The LOA will let you know what documents are needed and explain the details. After you send your documents, they check if everything matches the request and follow up if anything is missing. Then, they send your response to the processor or another team member using the company’s process. Sending in documents for a condition does not mean it has been accepted or that your loan is approved. Only the underwriter or another authorized reviewer can decide if your response meets the requirement. An LOA can help you collect the needed information, but they cannot guarantee approval or make exceptions on their own.
Ready for a More Organized Mortgage Process?
Complete a quick application or send your scenario. The Gustan Cho Associates team can help guide your file from initial application through underwriting, conditions, and closing.Appraisal, Title, Insurance, and Third-Party Coordination
An LOA may help track third-party items that are needed for the mortgage file. This can include appraisal status, title work, homeowners’ insurance, flood insurance when required, and other transaction documents.
Appraisal Coordination
Depending on the company procedure, the LOA may help initiate or track the appraisal through the lender’s approved appraisal process. The LOA should not select or influence the appraiser or attempt to affect the appraised value.
Title and Insurance Follow-Up
The LOA may also help confirm that title and insurance documents have been received and forwarded to the appropriate team members. The goal is to keep required third-party items from becoming last-minute closing problems.
Does a Loan Officer Assistant Need an MLO License?
 Licensing depends on the assistant’s actual duties, employment arrangement, and applicable state requirements. The LOA job title alone does not determine whether a license is required.
Unlicensed Employees Performing Support Duties
Under the federal SAFE Act framework, qualifying employees who perform only permitted clerical or support duties under the required direction, supervision, and instruction may be exempt from state MLO licensing. Those duties may include collecting requested records, checking documents for completeness, and following up for information needed to process the loan. The exemption does not authorize offering or negotiating mortgage rates or terms or counseling borrowers about those terms. Supervision must involve actual oversight of the employee’s work. CFPB’s Appendix C to Regulation H explains these distinctions.
Independent Contractors
Independent contractors performing loan-processing or underwriting support duties generally must obtain and maintain a state MLO license, even when their work is clerical, unless an applicable exception applies. Working under a licensed loan officer does not automatically exempt an independent contractor.
LOAs With an Active License or Registration
An LOA who holds the appropriate active MLO license or registration may perform origination activities within their authorization and assigned responsibilities. Federal registration applies to qualifying employees of covered financial institutions. It does not replace required state licensing for someone originating loans at a mortgage brokerage.
Licensing Is Only Part of the Review
State requirements must also be considered. In addition, Regulation Z § 1026.36 separately defines loan-originator activities and administrative exclusions. A SAFE Act licensing exemption alone does not resolve every obligation associated with an assistant’s duties.
How Technology Helps With Mortgage Documents
Digital tools make it easier to collect documents and track their status. But just because you upload a file successfully does not mean it is complete, readable, or ready for underwriting. The mortgage team will still review everything you send. Use the company’s secure portal or another approved way to submit your documents. Make sure your copies are clear, in the right format, and include any required dates or supporting records. Keep copies for yourself. If you are not sure what is needed, ask your LOA before sending more documents.
Examples of Problems an LOA Can Catch Early
These examples show how an LOA can spot issues and share them with the right team member for review. They are not based on real borrower cases and do not guarantee any specific results.
Missing Bank Statement Pages
A borrower sends in a six-page bank statement, but pages 3 and 4 are missing. The LOA notices this and asks for the missing pages before sending the statement for review.
Earnings That Differ From the Application
A borrower says they earn $9,000 per month, but their recent pay stubs show fewer hours and lower pay. The LOA points out this difference so the loan officer or processor can review it. The mortgage professional will decide what income counts for qualifying.
Bankruptcy Status That Needs Clarification
A borrower thinks their bankruptcy is finished, but current records show they are still in an active Chapter 13 repayment plan. The LOA highlights this conflict so the mortgage team can check the case status and review what is required for eligibility and documentation.
A Deposit With an Unclear Source
A bank statement shows a recent $12,000 deposit, but the source is not clear. The LOA points this out so the loan officer or processor can decide if more documents are needed. The amount is just an example, and deposit review rules depend on the loan program and transaction.
Common Problems That Delay a Mortgage File—and What Borrowers Can Do
Incomplete documents and unresolved discrepancies can delay a mortgage file. Address these issues with specific follow-up:
- Employment dates do not match: Compare the application with your employment records and confirm the correct dates. Explain any differences to the mortgage team so the application can be corrected accurately.
- You receive another request for a document already submitted: Ask what needs to be corrected, clarified, or updated. Understanding the reason helps you provide a response that addresses the request.
- Insurance costs are still a rough estimate: Obtain a property-specific homeowners insurance quote early. Ask the mortgage team whether flood coverage or other insurance requirements apply, and provide your insurance agent’s contact information.
- Your employment or finances change: Notify the mortgage team promptly of any changes to your job, hours, income, debts, or funds available for closing. Before opening new credit or making a major financial move, ask how it could affect your file.
If you cannot provide a requested item by the deadline, tell your contact early and ask whether another acceptable document is available.
What Borrowers Should Expect From Their LOA
Borrowers should expect clear communication, organized document requests, and honest updates about what is still needed.
An LOA should not leave the borrower guessing whether documents were received or what stage the loan is in.
At the same time, the LOA cannot control every part of the transaction. Underwriting decisions, appraisal results, title problems, insurance requirements, seller delays, and changes in the borrower’s financial situation can all affect timing.
Ask Who Your Main Contact Is
Mortgage teams are structured differently. Borrowers should know whether questions should go to the loan officer, LOA, or processor at each stage of the transaction. That simple clarification can prevent duplicate emails, mixed instructions, and unnecessary confusion.
FAQs About The Role Of The Loan Officer Assistant
Can an LOA Issue a Mortgage Pre-Approval?
Company procedures and applicable licensing rules determine who can authorize a pre-approval. An LOA may help prepare or deliver the letter through an authorized workflow, but their title alone does not authorize them to evaluate eligibility or recommend loan terms. Pre-approval remains subject to its stated conditions.
Can I Speak Directly with the Underwriter?
Borrowers will normally communicate via the loan officer (LO), the LOA, or the processor. If an underwriting request is unclear, your point of contact should obtain clarification from the underwriter through the company’s communication process.
Who do I Contact if my LOA is Unavailable?
Contact the designated backup, loan officer, or processor. If you cannot reach someone about an urgent issue, contact the branch manager or operations team. Include the relevant deadline so they understand when a response is needed.
What Should I do if the Document Upload Portal Doesn’t Work?
Tell your LOA what error you’re getting and what documents you’re attempting to submit. Ask for an approved, secure alternative, then confirm that the mortgage team has received your documents.
What if I Cannot Obtain a Requested Document?
Explain the problem to your LOA or processor as soon as you can. They can then query the appropriate reviewer to see if an acceptable alternative is available. Any alternative must satisfy the relevant documentation requirements.
Final Thoughts on the Role of the Loan Officer Assistant
Knowing who to contact will get you the right answer. Your LOA or processor can handle documentation requests and routine updates; mortgage advice should be provided by an appropriately authorized loan officer. The underwriter will review the file and determine whether the underwriting requirements have been met. If at any point you’re not clear on the request or your responsibility, you should seek clarification. Before you go ahead with a purchase or refinance, get in touch with Gustan Cho Associates to confirm the document checklist for your circumstances and identify your primary and backup contacts. If there are any changes to your employment, any questions regarding available funds, or any difficulty obtaining the documentation, raise them as early as possible so the team can assess what needs further review.
This article about “The Role of the Loan Officer Assistant in the Mortgage Process” was updated on October 15th, 2026.