Quick answer: What is mortgage payment shock?
Mortgage payment shock means your new monthly housing payment is higher than what you currently pay for rent or your mortgage. Even if the increase is big, it does not always mean you will be denied a loan. Each loan program has its own rules. For example, FHA manual underwriting may see a small payment increase as a positive factor. VA loans focus on how much money you have left after paying bills, while USDA Guaranteed and conventional loans have their own guidelines.
How Is Mortgage Payment Shock Calculated?

Compare your verified current housing payment with the proposed total monthly housing expense:
Payment shock percentage = (new housing payment − current housing payment) ÷ current housing payment × 100
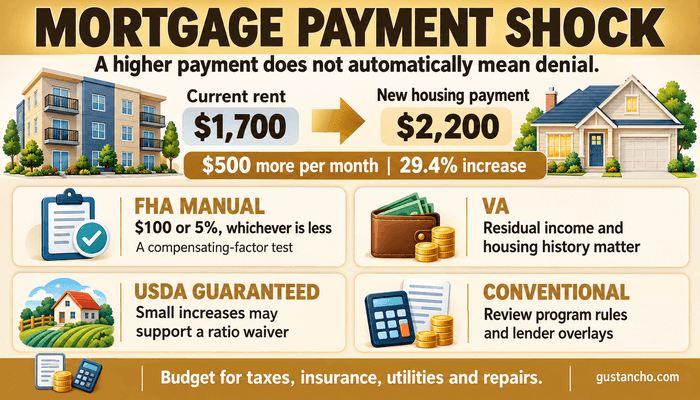
For example, moving from $1,700 in monthly rent to a $2,200 housing payment creates a $500 increase:
$500 ÷ $1,700 × 100 = approximately 29.4%
Include principal, interest, property taxes, homeowners’ insurance, applicable mortgage insurance, required flood insurance, and association dues in the proposed expense.
What This Hypothetical Example Means for FHA Manual Underwriting
For this hypothetical borrower, 5% of the current $1,700 rent is $85. Because FHA uses $100 or 5%, whichever is less, the minimal-increase allowance is $85.
The proposed $500 monthly increase exceeds that allowance, so the underwriter cannot use the minimal increase in housing payment as a compensating factor.
The next step is to verify the borrower’s qualifying ratios. If those ratios require compensating factors, the underwriter must determine whether other permitted factors are documented for the applicable tier. This example establishes which factor is unavailable; it does not establish an approval outcome.
What If You Currently Pay No Rent?
When your current housing payment is zero, the percentage cannot be calculated using this formula. Report the proposed monthly expense in dollars and document your rent-free living arrangement as required by the mortgage program.
Is There a Maximum Percentage of Mortgage Payment Shock?
There is no single percentage limit that applies across FHA, VA, USDA Guaranteed, and conventional mortgages. A lender may have an additional policy regarding increases in housing payments.
If a mortgage professional mentions a 20% or 25% limit, ask which agency guideline or lender policy requires it. Also, ask whether the requirement applies to your loan program and underwriting method, and what documentation is needed to satisfy it.
Identifying the source of the requirement helps determine the appropriate next step.
FHA Payment Shock: Automated and Manual Underwriting
How FHA evaluates a housing-payment increase depends on whether the loan follows automated or manual underwriting requirements.
Automated Underwriting Through FHA TOTAL
FHA TOTAL is a mortgage scorecard accessed through an automated underwriting system, or AUS.
An Accept result follows the TOTAL underwriting requirements in HUD Handbook 4000.1 unless the file requires a manual downgrade. A Refer result requires manual underwriting by an FHA Direct Endorsement underwriter.
The lender must verify the application information and satisfy the applicable FHA requirements. A TOTAL assessment alone cannot determine approval or denial.
The Minimal Increase in Housing Payment Test
For manual underwriting, FHA recognizes a minimal increase in housing payment as a possible compensating factor.
The proposed total monthly mortgage payment cannot exceed the current housing payment by more than $100 or 5%, whichever is less.
For example, if the current rent is $3,000, 5% equals $150. Because FHA uses the smaller amount, the permitted increase for this factor is $100.
This is a compensating-factor test, not a maximum payment increase imposed on every FHA borrower. Exceeding it makes this particular factor unavailable; the underwriter must evaluate the applicable ratio tier and other permitted factors.
How Is Payment Shock Calculated If You Live Rent-Free?
If your current housing payment is $0, the percentage formula cannot be used because it would divide by zero. Report the proposed housing expense in dollars instead.
For example, moving from rent-free housing to a $2,200 total monthly housing payment creates a $2,200 monthly increase. There is no calculable percentage for this comparison.
The lender evaluates the proposed expense under the selected mortgage program’s underwriting requirements.
Housing History Required for This Factor
The borrower must have a documented 12-month housing payment history with no more than one 30-day late payment. For cash-out refinancing, mortgage payments must be made on time for the past 12 months.
The lender must verify the current payment amount and payment history using acceptable records.
A borrower living rent-free cannot use the minimal-increase factor because there is no current housing payment to compare.
FHA Manual Underwriting Ratio Limits
FHA uses two ratios: the first compares the total monthly housing payment with qualifying gross income; the second includes the housing payment plus required monthly debt obligations.
For borrowers with a minimum decision credit score of at least 580:
- 31%/43%: No compensating factor is required to support these ratios.
- 37%/47%: Requires eligible cash reserves, a minimal housing-payment increase, or qualifying residual income.
- 40%/40%: Requires FHA’s no-discretionary-debt conditions.
- 40%/50%: Requires at least two permitted factors: eligible cash reserves, a minimal housing-payment increase, qualifying residual income, or eligible additional income excluded from effective income.
Borrowers qualifying with a score of 500–579 or without a credit score are generally limited to 31%/43%, even with compensating factors. Qualifying energy-efficient homes may permit separate 33%/45% stretch ratios.
Each factor must meet its own requirements and be permitted for the selected tier.
What No Discretionary Debt Requires
For the 40%/40% tier, the housing payment must be the borrower’s only open account carrying a balance that is not paid off monthly.
The borrower must also have established credit accounts in their own name, open for at least six months, with evidence that those other accounts were paid in full each month during the previous six months.
Having no other debts does not establish this factor. Authorized-user accounts do not satisfy the requirement for accounts in the borrower’s own name.
When Additional Income Can Support Higher Ratios
Certain overtime, bonus, part-time, or seasonal income excluded from effective income may support the 40%/50% tier alongside another permitted factor.
The lender must document at least one year of receipt and establish that the income is likely to continue. Including that income must reduce the housing ratio to no more than 37% and the total debt-to-income ratio to no more than 47%.
This income cannot serve as the single factor for the 37%/47% tier. Income from someone who is not obligated on the mortgage cannot be used for this purpose.
VA Mortgage Payment Shock Guidelines
VA does not publish a universal payment-shock percentage limit for purchase loans. Its underwriting review emphasizes residual income—the money remaining for family living expenses after required deductions, debts, and housing costs.
What the 20% Residual-Income Provision Means
VA generally requires closer scrutiny when the debt-to-income ratio exceeds 41%. Residual income at least 20% above the applicable guideline provides an exception to that DTI scrutiny provision.
This concerns the treatment of a higher DTI. It does not establish a payment-shock allowance or guarantee approval. The file must still satisfy the remaining VA underwriting requirements.
Why Comparable Housing Expenses Matter
When residual income is marginal, VA directs the underwriter to consider how the borrower previously handled similar housing expenses.
Rent or mortgage payment records can show whether the borrower consistently managed payments comparable to the proposed expense. The underwriter considers that history alongside the other credit factors.
Fannie Mae and Freddie Mac Payment Shock
Fannie Mae and Freddie Mac do not publish a universal percentage limiting how much a borrower’s housing payment can increase when purchasing a primary residence.
For automated underwriting, the loan is evaluated using the complete borrower and transaction profile rather than a single purchase-payment-shock cutoff.
Fannie Mae’s Desktop Underwriter evaluates multiple risk factors as part of its underwriting recommendation.
Freddie Mac’s Loan Product Advisor calculates and evaluates the borrower’s qualifying ratios from the information submitted. When LPA returns an Accept recommendation, it has determined that the qualifying ratios are acceptable, subject to verification and the remaining mortgage requirements.
Lender Overlays May Still Apply
A lender can have its own internal policy concerning a large increase in housing expenses.
For example, a lender may request additional reserves or a written explanation when the proposed mortgage payment is substantially higher than the borrower’s current rent.
That should be identified as a lender overlay or underwriting policy rather than a universal Fannie Mae or Freddie Mac payment-shock limit.
Denied Because of Mortgage Payment Shock? Get a Second Opinion
Payment shock by itself does not always mean the loan is over. We’ll review your DTI, credit, reserves, housing history, and loan program to see what may still work.USDA Guaranteed Loan Payment Shock Guidelines
USDA Guaranteed does not require a payment shock as a separate eligibility test. Lenders may still compare current housing expenses with the proposed payment when evaluating compensating factors or other positive loan characteristics.
When a Small Payment Increase Can Support a Ratio Waiver
For certain USDA Guaranteed purchase loans that receive GUS Refer, Refer with Caution, or manual underwriting, a small increase in housing payments may support a debt-ratio waiver.
The proposed PITI housing payment cannot exceed the verified current housing expense by more than $100 or 5%, whichever is less.
Required Housing Payment Documentation
To use this factor, verification of rent, verification of mortgage, or applicable credit-report records must establish:
- The actual housing payment is due.
- A payment history covering the 12 months before application.
- No more than one 30-day late payment during that period.
If payments were made to a family member or an interested party, the history must also be supported by 12 months of canceled checks, money order receipts, or electronic payment confirmations. A shorter history does not satisfy this compensating factor.
Other Debt-Ratio Waiver Requirements
A small payment increase does not, by itself, qualify the file for a waiver. Borrowers must also meet the applicable validated credit-score requirements, ratio limits, and other eligibility conditions.
The lender must document the waiver request and obtain approval from the USDA Guaranteed program.
How Verification of Rent Affects Payment Shock
The underwriter needs an accurate current housing payment before comparing it with the proposed mortgage payment.
Depending on the loan program and underwriting method, rent may be documented through:
- Verification of rent from a management company
- Verification from an individual landlord
- Current lease
- Canceled checks
- Bank statements
- Electronic payment records
The exact documentation requirements differ by program.
Conventional Rental Payment Documentation
When conventional underwriting requires rent documentation, possible records include:
- Direct verification from a landlord or property management company.
- Canceled checks, bank statements, or acceptable electronic payment records.
- A current signed lease with supporting payment records.
The required method and length of history depend on the transaction, underwriting findings, and applicable credit rules. Fannie Mae’s cited rental-payment provisions specifically address situations such as non-occupant borrowers and second-home or investment-property transactions. They should not be presented as a standard payment-shock checklist for every conventional purchase.
A lease establishes the agreed rent amount. Supporting payment records establish what was actually paid.
Why the Verified Amount Matters
If the borrower says rent is $1,500, but the documentation shows $1,900, the payment-shock calculation should be based on the verified housing expense.
Accurate housing documentation prevents the underwriter from evaluating the new mortgage payment against the wrong starting point.
What Underwriters Review When Housing Costs Increase
The review addresses several different questions:
- Does the payment fit the qualifying income? The lender calculates the proposed housing expense and required monthly debts against documented income.
- What does the housing history show? Records establish the current payment and, when required, whether payments were made on time.
- How much eligible money remains after closing? Reserves are calculated after accounting for the down payment, closing expenses, and required debt payoffs.
- Does the income meet program requirements? The lender verifies the amount, history, and expected continuation of income used to qualify.
- Does the credit history meet the applicable standards? Recent delinquencies and other credit issues may require additional review or documentation.
These underwriting considerations are distinct from formally recognized compensating factors. When a loan requires compensating factors, each one must meet the selected program’s definition and documentation requirements.
Review Down Payment and Reserves Together
A bigger down payment lowers your mortgage payment but gives you less cash after closing. Calculate both amounts before deciding how much to put down.
Purchase Payment Shock Versus ARM Payment Shock
The term “payment shock” can refer to two different situations.
Payment Shock When Buying a Home
For a purchase loan, payment shock usually refers to the increase from the borrower’s current housing expenses to the proposed mortgage payment.
This is the type of payment shock discussed throughout this article.
Adjustable-Rate Mortgage Payment Shock
With an adjustable-rate mortgage, payment shock can also refer to a future increase when the interest rate adjusts after an introductory period.
Fannie Mae and other mortgage programs address this risk through qualifying-rate requirements that assess whether the borrower can afford the mortgage after an applicable rate adjustment.
These two situations should not be confused.
A borrower purchasing a home with a fixed-rate mortgage can experience a significant purchase payment shock even though the mortgage payment itself is not scheduled to adjust.
Common Payment Shock Problems and How To Address Them
- Rent cannot be verified: If your rent cannot be verified, check with the lender to find out which payment records or other documents they will accept before you submit your rental history.
- Rent differs from the application: If the rent amount on your application is different from your records, make sure your lease, payment records, and application all match. This helps the underwriter use the correct, verified amount.
- Recent housing payments were late: If you have made any late housing payments recently, gather records that show the payment dates and write a short explanation of what happened. Ask the lender how this payment history might affect your loan options.
- Rent-free housing is undocumented: If you live rent-free and do not have documentation, ask the lender what proof they need to confirm your living situation and current housing costs.
- Taxes or insurance remain estimates: If your taxes or insurance are still just estimates, get an insurance quote for the specific property, including flood coverage if needed, and check the property tax estimate. Make sure the updated amounts are used in your payment calculation.
- New debts or changes in income affect DTI: If you have new debts or changes in your income, let the lender know right away. This allows them to update your qualifying ratios and underwriting information as needed.
- Cash remaining after closing is limited: If you will have little cash left after closing, add up the money you will have after paying the down payment, closing costs, and any required payoffs. Check if this amount meets the lender’s reserve requirements.
- A lender cites a payment-shock limit: If your lender mentions a payment-shock limit, ask if this rule is from an agency guideline or the lender’s own policy. Find out which rule applies to your situation.
- Compensating factors lack documentation: If you are using compensating factors, make sure you know which one applies and obtain the necessary proof for the correct ratio tier before relying on it.
Budget Beyond the Qualifying Mortgage Payment
Compare the proposed housing expense with your take-home income and regular household spending. Allow for utilities, maintenance, repairs, groceries, transportation, childcare, and other recurring costs. Consider what will remain available for savings and unexpected expenses.
A fixed-rate mortgage generally keeps the scheduled principal-and-interest payment stable. Property taxes and insurance premiums can still change, increasing the total monthly housing expense even when the interest rate stays the same.
Review Your Proposed Payment Before Making an Offer
Ask Gustan Cho Associates to review your proposed housing expense before you commit to a purchase price. Request a clear explanation of the applicable underwriting method, any lender-specific requirements, and the documents still needed for your file.
FAQs About Mortgage Payment Shock
Can a Large Down Payment Reduce Payment Shock?
Yes. A larger down payment can reduce the loan amount and monthly mortgage payment, which may lower the increase relative to the borrower’s current housing expenses. The effect will depend on the purchase price, interest rate, taxes, insurance, mortgage insurance, and other housing costs.
Does Mortgage Payment Shock Affect First-Time Homebuyers More Often?
It can. First-time buyers often move from lower rent payments or living with family into a full mortgage payment that includes taxes, insurance, and other housing expenses. That does not make first-time buyers less eligible, but the larger increase may receive more attention when other risk factors are present.
Can a Higher Income Offset a Large Housing Payment Increase?
Higher qualifying income can improve the borrower’s overall debt-to-income ratio and ability to support the proposed payment. However, the income must meet the documentation and stability requirements of the mortgage program. A large payment increase is still reviewed as part of the complete loan profile.
Can Seller Credits or a Buydown Reduce Mortgage Payment Shock?
Seller credits can help pay for certain closing costs and let you keep more of your cash, as long as you stay within program limits. A permanent rate buydown, if allowed, can also lower your monthly mortgage payment. A temporary buydown lowers your payments at first, but with Fannie Mae and USDA Guaranteed loans, you still need to qualify for the full payment amount. Make sure you plan for the full housing payment once the temporary savings end.
Does Moving from a Mortgage to Another Mortgage Create Payment Shock?
Yes. Payment shock can apply even when the borrower already owns a home. For example, moving from a $2,000 housing payment to a $3,000 payment represents a meaningful increase that may be reviewed along with income, debts, reserves, and the rest of the loan profile.
Can Child Support or Other New Debts Make Payment Shock More Important?
Yes. New recurring obligations can increase the borrower’s total DTI and reduce the income available to cover the higher housing payment. The underwriter evaluates the housing payment increase alongside all required monthly debts, rather than reviewing payment shock in isolation.
Is Mortgage Payment Shock the Same as an Affordability Test?
No. Payment shock measures the percentage increase in the proposed housing expense relative to the borrower’s current housing payment. Affordability is broader and includes income, debts, reserves, credit, loan terms, and other household financial obligations.
This article about “Mortgage Payment Shock: Can You Qualify With a Higher Payment?” was updated on October 12th, 2026.