Job relocation mortgage guidelines can allow you to buy a home when transferring with your current employer or moving for a new job. Your financing options depend on the loan program, pay structure, employment timeline, and available funds.
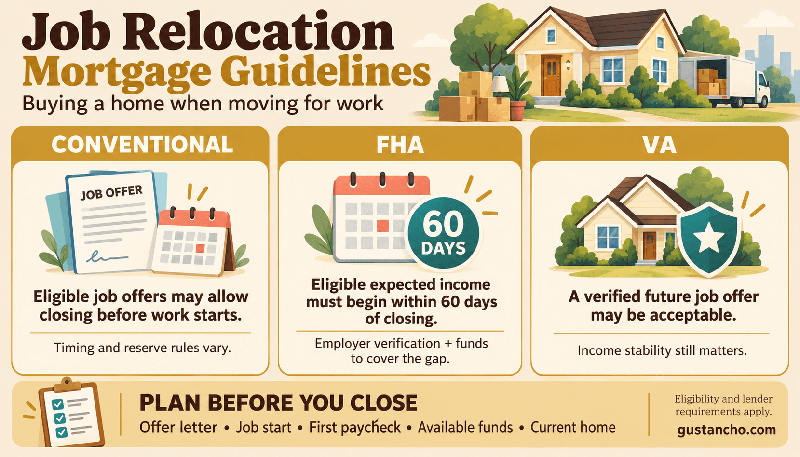
Some conventional and VA loans permit eligible borrowers to close before starting work. FHA also allows certain future employment income under HUD’s Expected Income provisions, including a requirement that income be received within 60 days of closing.
Before making an offer on a home, have your lender review your employment agreement, job start date, first expected paycheck, and planned closing date.
Does the New Job Have to Be in the Same Line of Work?
Not always. A borrower does not automatically become ineligible because the new position is in a different occupation or industry.
The lender reviews the overall employment history and determines whether the income is stable and acceptable under the specific loan program. A shorter employment history may sometimes be acceptable when other factors support the stability of the borrower’s employment and income.
Transferring With the Same Employer vs. Starting With a New Employer
A transfer with the same employer is generally easier to document because the employment relationship is continuing. The lender may verify the new location, position, salary, effective date, and whether any part of the borrower’s compensation will change.
For example, an employee transferring from a company office in Illinois to the same employer’s office in Florida may still have continuous employment, even if the employee is moving to another state.
Starting with a completely new employer requires additional review. The lender may need an executed employment offer or contract showing the borrower’s position, rate of pay, and expected start date.
The biggest issue is not simply whether the employer changed. It is whether the lender can use the new income to qualify the borrower under the applicable mortgage guidelines.
Watch for Changes in Pay Structure
A job change can become more complicated when a borrower moves from:
- Salary to commission
- Full-time employment to part-time employment
- Regular hourly pay to variable hours
- W-2 employment to self-employment
- Base salary to compensation is heavily dependent on bonuses or incentives.
These types of income may require an established earnings history and should not be treated the same as fixed-income.
Can You Close on a Home Before Starting Your New Job?
In some cases, yes.
Certain mortgage programs allow borrowers to qualify using income from a new job that will begin after the mortgage note date. This can help a borrower relocate, purchase a home, and close before reporting to work at the new location.
However, an employment offer by itself does not guarantee approval. The lender must determine that the offer meets the requirements of the applicable loan program.
The start date, type of income, property, occupancy, available assets, and terms of the employment offer can all affect eligibility.
This is why borrowers who plan to close before starting work should tell their loan officer early in the mortgage process. Waiting until underwriting to disclose a future start date can create unnecessary delays.
Fannie Mae Job Relocation and Employment Offer Guidelines
Loan delivery is the process by which the lender transfers your mortgage to Fannie Mae or Freddie Mac after closing.
Both Fannie Mae options require a fully executed employment offer or contract that identifies you, your employer, your position, your pay type, your pay rate, and your start date.
Employment with a family member or an interested party to the transaction is ineligible under either option.
Option 1: Paystub Obtained Before Loan Delivery
The lender must obtain a paystub supporting the qualifying income before delivery and complete the required employment verification.
Option 2: No Paystub Obtained Before Loan Delivery
This option is limited to:
- Purchase transactions.
- One-unit principal residences.
- Borrowers qualifying using only fixed-base employment income.
Employment should not begin earlier than 30 days before the mortgage note date and must not be later than 90 days after that date. The offer must be fully executed and noncontingent, and all employment conditions must be met before closing. Further financial resources are needed in this case.
Fannie Mae Reserve Requirements Without a Paystub Before Delivery
Under Option 2, the lender must document one of the following in addition to other required reserves:
- Six months of PITIA: principal, interest, taxes, insurance, and applicable association dues for the purchased home.
- Resources covering the employment gap: all monthly liabilities included in the debt-to-income ratio, including the new housing payment, for the months between the note date and employment start date, plus one month.
The lender may consider a partial month as a full month. Eligible resources can include reserves and documented current net income expected during that period.
Ready to Buy a Home After an Out-of-State Job Relocation?
Complete a quick application or send your scenario. We’ll review your new employment, current housing, income, DTI, occupancy, and best mortgage options.Hypothetical Example: Calculating Financial Resources
Assume your lender calculates a three-month coverage period, including the additional month required under this option.
- New monthly housing payment: $2,500
- Other qualifying monthly debts: $700
- Total monthly obligations: $3,200
The required financial resources would be $3,200 × 3 = $9,600, before any eligible income adjustment.
That $9,600 is separate from your down payment and closing costs. Any other reserves required for the loan still apply.
Review how much money will remain after closing to determine whether this timeline fits your available funds.
Freddie Mac Guidelines for Income Starting After the Note Date
Freddie Mac permits certain non-fluctuating salary or hourly income to begin after the mortgage note date. Hourly income from a new employer requires a guaranteed minimum number of hours per week.
Option One: Income May Begin After Loan Delivery
Employment or an eligible income increase must begin within 90 days of the note date. This option covers purchases and no-cash-out refinances of one-unit primary residences.
Beyond closing funds and other required reserves, the lender must verify resources sufficient to cover housing expenses and other monthly liabilities until income begins, plus one additional month. Partial months count as full months. Verified income expected during that period may reduce the required amount.
Option Two: Income Must Begin Before Loan Delivery
There is no set number of days required between the note date and the start of employment, but the borrower’s income must begin before the loan is delivered.
The lender must also obtain a pay stub, written employment verification, or a qualifying third-party employment check to support the income used for approval. Simply starting work is not enough to meet this requirement.
Option Two allows a wider range of transactions and property types, including eligible cash-out refinances. It does not require the extra employment-gap funds needed for Option One, but standard closing fund and reserve rules still apply.
FHA Job Relocation Guidelines: Using Income From a New Job
You may be able to close an FHA loan before starting your new job. HUD’s Expected Income provisions allow lenders to consider eligible future employment income when the required documentation and financial support are in place.
Requirements for FHA Expected Income
For income from a new job, the lender must:
- Verify the existence and amount of the expected income with the employer in writing.
- Document that the income is guaranteed to begin within 60 days of mortgage closing.
- Ensure you have enough income or cash reserves to cover the mortgage payment and other obligations until your new income starts.
- Confirm that the expected income will not come from a family-owned business.
The lender must calculate qualifying income in accordance with HUD’s requirements for the specified income type. A job offer alone does not establish that every requirement has been met.
Your Job Start Date and First Paycheck Are Different Dates
Your employment start date is when you begin working. Your income start date is when you begin receiving pay. Those dates may be weeks apart due to the employer’s payroll schedule.
Starting work within 60 days of closing does not, by itself, establish that you will receive income within that window. Ask your employer to confirm the first expected payment date so your lender can review both dates before scheduling the closing.
If You Have Already Started the New Job
The lender can evaluate your current employment in accordance with the applicable FHA income documentation requirements. FHA does not require two years with the same employer, although your employment history and income stability still need to be reviewed.
If a lender requires you to start work or provide a paystub before closing, ask whether that requirement reflects your particular circumstances or an additional lender requirement.
VA Job Relocation Guidelines and Future Employment
VA guidelines can provide more flexibility for eligible Veterans and service members relocating for a new job.
The VA Lender’s Handbook specifically recognizes that a borrower may have a valid employment offer for a job beginning at or after the anticipated closing date. The employment offer must be verifiable, and the lender must consider the borrower’s full circumstances when determining whether the income is acceptable.
A pay stub may not be available when the borrower has not yet started working.
Employment Stability Still Matters
An offer letter does not mean the income will be approved automatically.
The underwriter may consider:
- Previous employment history
- Reason for the job change
- Type of new employment
- Expected income
- Education or training
- The likelihood that the employment will continue
VA guidance gives favorable consideration to job changes made for career advancement in the same or a related field. Frequent job changes or moves into unrelated occupations may require a closer review of income stability.
Individual lenders and investors may also have additional requirements beyond the minimum VA guidelines.
What Happens to Your Current Home When You Relocate?
Buying your next home before selling your current one may be possible. Your lender needs to review the housing obligations that will continue after the purchase.
Provide:
- Current housing payment: Your latest mortgage statement, plus property taxes, insurance, association dues, and any second mortgage or HELOC payments.
- Sale or rental plans: Explain whether you will sell, rent, or keep the property. Include a sales contract or lease if available.
- Expected timing: The anticipated sale closing date or rental start date, including any overlap with your new home purchase.
- Other continuing housing expenses: Temporary rent or other housing obligations you will still pay after closing.
Have your lender confirm how the existing payment will be treated before relying on sale proceeds or rental income to qualify for the new mortgage.
Documents Needed for a Job Relocation Mortgage
Your lender may request:
- Complete employment offer or contract: You must include your name, the name of your employer, the position you have been offered, the start date, the type of compensation, your salary or hourly rate, and the guaranteed hours if they apply; also, provide the required signatures or act of acceptance.
- Employer transfer confirmation: When transferring within the same company, you must record the new location, the effective date, and any changes to your job or salary.
- Income and employment records: For income and employment records, provide recent pay stubs if you’ve already started work, and previous W-2s or other employment records if they are requested.
- Bank and asset statements: When preparing bank and asset statements, list the funds available for the down payment, the closing costs, and the required reserves.
- Employer contact and payroll information: For the lender to check your employment status and when you will start receiving your pay, allow them access to your employer contact and payroll details.
Employment Conditions That Need Verification
If your offer depends on a background check, drug screening, professional license, or another requirement, provide documentation showing whether it has been satisfied. Your lender will confirm which conditions must be cleared before closing under the selected loan program.
How to Coordinate Your Job Start Date and Mortgage Closing
Before agreeing to a closing date, confirm your employment timeline and the lender’s documentation deadlines. Use these steps to address common relocation problems:
- Your job start date has been postponed. Ask your employer for updated confirmation. Then, have your lender review your eligibility and financial resources before you move forward with the original closing date.
- Your employer, salary, or hours change: Send the updated employment details to your loan officer right away. Ask your lender to review your qualifying income before you count on your current approval.
- Employment conditions remain unresolved; provide your lender with any required clearance documents. Check with them to see if any outstanding issues could delay your closing.
- Your employer is slow to verify employment: Find an HR or payroll contact who can respond to your lender. Make sure this person is available before the verification deadline.
- Your first paystub will arrive after closing: Ask the lender to confirm that your approved financing permits this timing and identify any documentation required before loan delivery.
- Your available funds fall below the required amount: Review what must remain after closing before spending money on moving costs, furniture, or other purchases.
- The home’s closing date changes: Have the lender recheck employment timing and reserve calculations before accepting the revised date. Moving closing by a few days can affect a timeline already close to a program’s limit.
Plan Your Mortgage Around Your Relocation
Before you set a closing date, give your loan officer your full employment offer, your confirmed job start date, the date you expect your first paycheck, and your asset statements. Also, let them know what you plan to do with any home you already own.
Ask your lender to confirm which financing option matches your timeline and how much money you need to keep available after closing. This review can help you plan your home purchase, move, and new job with fewer last-minute surprises.
FAQs About Job Relocation Mortgage Guidelines
Can Employer-Paid Relocation Assistance be Used Toward a Home Purchase?
Possibly. If an employer provides relocation funds, the lender will need to determine the purpose of the payment and whether the funds are an acceptable source for the transaction. A reimbursement for moving expenses is treated differently from funds available for the down payment, closing costs, or reserves. Provide the relocation agreement or employer documentation to the lender before relying on these funds.
Will a Probationary Period at My New Job Prevent Mortgage Approval?
Not automatically. Freddie Mac does not treat probation, training, or orientation after employment begins as an employment-offer contingency. Unresolved background checks or licensing requirements may still affect approval. Your lender must verify the offer terms and qualifying income.
Can my spouse stay behind while I relocate for work?
Yes. A temporary living arrangement in which one spouse remains in the current home does not automatically preclude mortgage approval. The lender may ask about the occupancy of the new property and any housing expenses that will continue after closing.
Can I Qualify if My New Job is Remote or Hybrid?
Remote and hybrid employment can be acceptable when the lender can verify the employment and qualifying income. The lender may also confirm that the borrower is permitted to work from the new home, especially when the employer is in another state.
Does a Relocation Bonus Count as Qualifying Income?
A one-time relocation or signing bonus generally should not be treated the same as an ongoing salary. Whether any bonus income can be used for qualification depends on how it is paid, whether it is expected to continue, and the loan program’s requirements. A one-time payment may still be relevant as an asset if it is properly documented and eligible for use.
Can Temporary Housing Expenses Affect My Mortgage Approval?
They can. If the borrower will continue paying rent, corporate housing, or another housing obligation after closing, the lender may need to determine whether that expense must be considered when qualifying the borrower. Temporary expenses that will end before or shortly after the move should be documented when requested.
Should I Get Preapproved Before Accepting a Relocation Package?
It can be helpful to speak with a loan officer before finalizing the timing of a relocation. A mortgage preapproval can identify potential issues with new income, the existing home, available assets, occupancy, or relocation benefits before the borrower commits to a home purchase or a specific closing date.
This article about “Job Relocation Mortgage Guidelines for Out-of-State Homebuyers” was updated on October 1st, 2026.