Quick Answer: Refinancing during Chapter 13 bankruptcy is possible if a repayment plan is active. Your options depend on the loan you have now, whether you want cash out, your plan and mortgage payment histories, and the rules for the new loan. Standard FHA Chapter 13 underwriting generally requires at least 12 months of satisfactory plan payments and written permission from the bankruptcy court. VA may give favorable consideration after 12 months of satisfactory payments with trustee or judge approval. FHA Streamline and VA IRRRL refinances have different underwriting rules, so do not assume every refinance follows the same checklist.
Start With the Mortgage You Have and the Refinance You Need
If you want to lower your payment or change your loan terms, first identify your current mortgage. An FHA Streamline can refinance an existing FHA loan, and a VA Interest Rate Reduction Refinance Loan (IRRRL) can refinance an existing VA loan. Neither is a way to withdraw substantial home equity. If you have a different type of mortgage, want to pay off another lien, or need a cash-out refinance, the lender must review a different refinance program.
An active Chapter 13 case adds another question: Does the proposed mortgage fit your repayment plan, and what permission must be obtained before you incur the new debt? Your bankruptcy attorney can address that question while the lender evaluates the loan. An affordable new payment does not, by itself, satisfy the bankruptcy or mortgage requirements.
FHA Refinancing While Chapter 13 Is Active
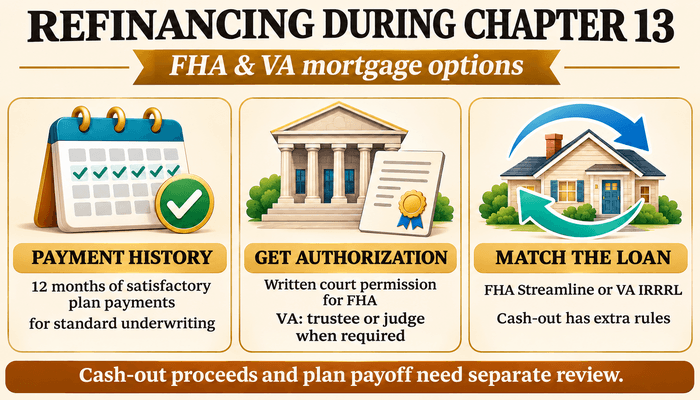
For a standard FHA refinance that requires Chapter 13 credit underwriting, HUD permits consideration only after at least 12 months of the repayment period have elapsed, as indicated by the FHA case number assignment. The lender must determine that required payments in the most recent 12 months were made on time and obtain written permission from the bankruptcy court for the mortgage transaction. The borrower must also meet the requirements of the specific refinance.
An FHA rate-and-term refinance may replace an eligible existing mortgage without a substantial equity withdrawal. The lender reviews the mortgage history, income, debts, property, and bankruptcy records in accordance with applicable FHA rules. Having 12 months of plan payments does not guarantee approval if another requirement is not met.
What if the Current Loan Is Already FHA?
An FHA Streamline may be worth considering if your existing mortgage is FHA-insured and current. It must provide a net tangible benefit under FHA rules, and it cannot be used to take more than $500 in cash from the transaction. FHA offers credit-qualifying and non-credit-qualifying Streamline options. The latter has exemptions from many standard credit, income, asset, and appraisal requirements. The documents you need depend on which option applies to your loan.
The lighter underwriting process does not settle the bankruptcy question. Before assuming a Streamline is possible, have the lender review the active case and have your bankruptcy attorney confirm what authorization is needed for the new mortgage.
What if You Want Cash Out?
An FHA cash-out refinance faces additional requirements. HUD generally limits it to 80% of the property’s adjusted value, requires an eligible owner-occupied principal residence, and reviews the payment history of all the borrower’s mortgages. The lender also needs to assess whether the proposed new debt and use of proceeds can be approved in the Chapter 13 case. Equity alone does not establish eligibility.
If the goal is to pay off the Chapter 13 plan early, ask your bankruptcy attorney to review the confirmed plan and the proposed use of proceeds before relying on a cash-out estimate. Paying the apparent remaining balance does not necessarily resolve every obligation or determine when the case can be completed.
VA Refinancing While Chapter 13 Is Active
VA’s credit guidance permits favorable consideration when a borrower has made at least 12 months of satisfactory Chapter 13 payments, and the trustee or bankruptcy judge approves the new credit. That guidance is relevant when the lender is making a full credit decision. The borrower must also meet the rules for the requested VA refinance.
A VA cash-out refinance involves full credit underwriting and an appraisal. The lender reviews the borrower’s income, credit, residual income, property value, and the proposed transaction.
Any use of cash to pay the Chapter 13 plan must also be addressed through the bankruptcy case; it is not automatically approved because a VA cash-out loan is otherwise available.
A VA IRRRL works differently. It refinances an existing VA loan and cannot be used to take equity out or pay the bankruptcy plan. VA generally does not require full credit underwriting or an appraisal for an IRRRL, although underwriting is required in certain cases, including when the existing loan is at least 30 days past due or the new principal, interest, taxes, and insurance payment rises by 20% or more. VA notes that a borrower with a recent Chapter 13 bankruptcy may need trustee approval for the new loan. Have the lender and bankruptcy attorney check the particular case before applying the 12-month full-underwriting rule to an IRRRL.
Why the Plan Ledger and Mortgage History Both Matter
The lender may well require an up-to-date trustee ledger to establish when the plan payments actually began and whether the required payments were made on time. Mortgage payments are a different matter. Depending on the refinance, recent mortgage lates could well preclude a cash-out or affect how a Streamline or IRRRL is processed, even if the Chapter 13 plan is current.
If a payment is late or irregular, get the ledger and any supporting explanation before you pay for an appraisal. Don’t assume a payment was on time just because the trustee eventually accepted it. The lender has to apply the relevant program rules to the documented history.
How to Prepare for a Refinance During Chapter 13
Gather your current mortgage statement, recent payment history, confirmed Chapter 13 plan, and the latest trustee ledger. Let your lender know if you want a lower payment, new loan terms, or cash out. This helps the lender determine which FHA or VA option to consider and whether you’ll need to provide income documents or get an appraisal. Streamline or IRRRL options usually require less paperwork than a full cash-out refinance.
Next, take the proposed loan terms to your bankruptcy attorney. The attorney can determine the local process for obtaining any required trustee consent or court order and address any proposed use of refinance proceeds.
Authorization under the bankruptcy case and mortgage approval are separate decisions. At Gustan Cho Associates, we review the payment history, current loan, refinance goal, and proposed loan terms together before a borrower commits to an appraisal or relies on an early plan payoff.
Conventional refinancing is usually a later option for someone in an active Chapter 13 plan. For example, Fannie Mae generally requires two years after a Chapter 13 discharge or four years after a dismissal; a documented extenuating-circumstances exception can reduce the dismissal period to two years. Those waiting periods make an FHA or VA review more relevant for many borrowers seeking to refinance while the plan remains active.
FAQs about Refinancing During Chapter 13 Bankruptcy
What if I Make My Mortgage Payments Through the Trustee?
- Tell the lender how the payments are made. The trustee ledger, loan servicer’s records, and bankruptcy documents may be needed to show when plan and mortgage payments were actually made. Ask for those records early if the servicer’s history does not clearly reflect payments made through the plan.
Can I Refinance a Conventional Mortgage Into an FHA Mortgage?
- Potentially. An FHA rate-and-term refinance can be considered for an eligible non-FHA existing mortgage if the borrower meets FHA refinance and Chapter 13 requirements. An FHA Streamline is available only when the mortgage being refinanced is already FHA insured.
Is Verbal Permission from the Trustee Enough?
- Do not rely on a conversation alone. HUD requires written permission from the bankruptcy court for a standard FHA Chapter 13 mortgage transaction. VA guidance refers to trustee or bankruptcy judge approval when new credit is underwritten. Your attorney and lender should agree on the written authorization needed for your specific refinance.
Can a VA IRRRL Pay Off My Second Mortgage?
- No. A VA IRRRL refinances the existing VA loan and allowable loan costs; it cannot be used to pay another lien or withdraw equity. If you have a second mortgage, the lender will need to address its lien position or review a different refinance option.
Should I Keep Making Payments While the Refinance is Pending?
- Yes. Continue making required mortgage and Chapter 13 plan payments unless your bankruptcy attorney or the court gives you different instructions. An application, conditional loan approval, or proposed plan payoff does not change the payments currently due.
Does a Court Order Guarantee the Refinance will Close?
- No. The court’s authorization addresses the bankruptcy case; the lender still has to approve the mortgage. If the rate, loan amount, or cash-out proceeds change materially after the order is issued, ask your attorney whether the order still covers the proposed terms.
How Long does Bankruptcy Authorization Take?
- The timing depends on the court, the local procedure, and whether anyone objects to the proposed transaction. Ask your bankruptcy attorney about the process before setting a closing date. A lender’s initial loan estimate is not a promise that court approval or underwriting will finish by that date.
Final Thoughts on Refinancing During Chapter 13 Bankruptcy
Refinancing is possible in some instances during an active Chapter 13 case; the route depends upon the type of refinance. You need to start by reviewing your current loan, the plan ledger, and your mortgage payment history. Then have the proposed terms looked at by a lender and your bankruptcy attorney. That will give you a real answer about the loan and what approval is required under your bankruptcy case before you spend any money on an appraisal or plan for any cash-out proceeds.
This article about “Refinancing During Chapter 13 Bankruptcy: FHA and VA Options” was updated on November 19th, 2026.