Paying Down Credit Cards During Mortgage Process to Lower DTI
Paying off credit card debt during the mortgage process can be a decisive factor in loan approval or denial due to lender-imposed debt-to-income ratio limits. This scenario occurs more frequently than many borrowers anticipate. Pre-approval is often based on estimated property taxes, insurance, mortgage rates, and minimum credit card payments. However, actual figures may result in a higher housing payment than initially projected.
Paying off credit card debt during the mortgage process can lower your debt‑to‑income ratio. Help you get approved for a loan. Learn the rules timing, required documents and common mistakes to avoid.
A borrower who was near the maximum allowable DTI may unexpectedly exceed the limit. Paying down or paying off credit cards requires careful planning. The borrower should identify which account to target, the appropriate payment amount, how the lender will document the new balance, and whether sufficient verified funds remain for closing costs and reserves. If minimum payments on credit cards are significantly increasing the debt-to-income ratio, paying off or reducing certain accounts may be beneficial.
How Paying Down Credit Cards During the Mortgage Process Can Lower DTI
Mortgage lenders figure out the debt-to-income ratio by using the borrower’s qualifying monthly income and adding the monthly payments required by the mortgage program. Normal credit card minimum payments are considered recurring monthly obligations.
Someone might have a good payment history and enough income but still have a DTI problem because some of their credit accounts have minimum payments of $50, $100, $200, or more.
Getting rid of just one payment could be sufficient to bring the loan back into the allowable range. This doesn’t mean borrowers should just pay off every credit card. The goal in the mortgage approval process is usually to resolve the qualification issue while leaving enough money for the down payment, closing costs, prepaid expenses, required savings, and their needs after closing.
Why DTI Can Change After a Mortgage Pre-Approval
A mortgage pre-approval is based on the information available when the file is checked, and some expenses are estimated until a property is chosen, and the loan moves further in processing. The final amount paid for home insurance may exceed the estimate. Property tax bills could be different. It may be necessary to include an HOA payment. The mortgage rate might change. The final qualifying income could also vary from that of the first calculation.
Self-employed people who borrow money are a good example. The income used to qualify for a mortgage is not just the money deposited into a bank account; lenders must determine qualifying income based on the rules and tax documents.
The DTI can rise quickly if the qualifying income is less than anticipated, but the housing payment is higher. This is why a borrower who was initially found to be comfortably qualified at the start of the transaction may later discover that the file is very near the maximum allowable ratio.
How Credit Card Payments Affect Mortgage Qualification
The amount owed is usually not included directly in the DTI calculation for mortgages; instead, the monthly payment needed to qualify for the account is usually considered.
Borrowers should not make substantial payments solely due to a high DTI. It is advisable to consult the loan officer to determine which accounts to prioritize and the optimal payment amounts.
For example, let us consider a borrower who earns $8,000 per month in qualifying gross income and has a credit card that requires a monthly payment of $150. Getting rid of that $150 obligation would lower the back-end DTI by about 1.88 percentage points. It can be important when the borrower’s loan amount is just one or two percentage points above the level permitted by the underwriting findings. The loan officer should carry out the exact calculation before the borrower makes the payment.
Paying Down a Credit Card Is Different From Paying It Off
This distinction is important.
Paying Down a Credit Card
Paying down entails reducing the remaining balance while keeping a balance on the account. It is possible that a reduced balance could lead to a reduced minimum payment. However, the mortgage lender cannot just assume that the payment will decrease by a specific amount. To qualify, the lender requires acceptable documentation supporting the monthly obligation. Even if the borrower reduces the card balance from $8,000 to $2,000, the mortgage credit report will still reflect the previous monthly payment of $250, and the underwriter might require up-to-date documentation before approving the lower payment.
Paying Off a Credit Card
To pay off the card, you have to bring the balance to zero. In some mortgage programs, a monthly revolving payment can be excluded from the DTI calculation if the balance is properly documented as zero. It can result in a significantly greater and more predictable improvement in the DTI than making a partial payment. The account won’t automatically have to be closed just because the balance has been paid off.
Fannie Mae Guidelines on Paying Off Credit Cards to Qualify
Fannie Mae deals with debts that are paid off at or before closing. Fannie Mae says that if a revolving account is paid off at closing or before, the monthly payment on the remaining balance does not have to be included in the borrower’s long-term debt when calculating their DTI.
Fannie Mae states that the revolving account need not be closed for the payment to be excluded. The lender has to assess the borrower’s overall credit record, especially when debts are being paid off solely to qualify for the mortgage.
It is a significant update from the previous information, which is still being displayed on certain mortgage websites. A person, therefore, ought not to close a credit card account that has been in use for a long time just because it is believed that Fannie Mae requires the account to be closed after the loan has been paid off.
How Fannie Mae Treats Revolving Debt That Is Not Paid Off
Things like credit cards and unsecured lines of credit usually remain part of the borrower’s regular monthly obligations as long as there is a balance.
Usually, Fannie Mae uses the stated required payment for the account; however, if an acceptable required payment is not available, the guidelines provide a method for calculating the payment from the outstanding balance.
In the case of desktop underwriter loan file(s) where no monthly revolving payment has been entered, the desktop underwriter should use the larger of $10 or 5 percent of the outstanding balance when calculating the DTI. That is one reason borrowers should not think that making a large payment will instantly eliminate credit card debt from the mortgage calculation.
FHA Guidelines for Credit Cards and DTI
The FHA also stipulates that revolving credit obligations should be taken into account when assessing the borrower’s monthly liabilities. For revolving accounts, the lender usually uses the payment amount shown on the credit report, but if payment details are missing, FHA rules allow using proper account documents along with a percentage of the balance owed.
FHA also requires lenders to record that the money used to pay off debts before closing came from an acceptable source. On August 12, 2026, HUD issued an updated FHA Single Family Housing Policy Handbook.
It is possible that some of the revisions included in Update 18 may be implemented before their mandatory date of November 10, 2026. FHA files should always be checked against the handbook version used by the mortgagee. The main point is this: it is wrong to think that paying off a mortgage loan works the same way every time FHA is involved. The borrower should let the lender decide what documents are needed before making the payment.
Is it Necessary to Close a Credit Card After Paying Off Your Mortgage?
Usually, a rule does not require a conventional borrower to close a revolving account just to have the payment removed from their DTI. Fannie Mae makes it clear that it is not necessary to close the account when the revolving balance is paid off at or before closing, and that the payment does not count in the DTI.
In some cases, a mortgage loon underwriter or a lender might give additional instructions, but borrowers must not proceed to close the accounts themselves.
If an existing revolving account is closed, the available credit on the borrower’s credit report will go down. This can affect the borrower’s credit use and, in turn, their credit scores. It usually gives only a small benefit to make an unnecessary change to the credit rating during the mortgage approval process.
Should You Pay Off Your Credit Cards Before Applying for a Mortgage?
It is easier, when possible, to handle high credit card balances before the mortgage reaches the approval stage. This allows creditors to naturally report lower balances and might also help reduce credit use before the lender receives the mortgage credit report. The bigger concern is managing cash. You should not pay $15,000 to pay off credit cards only to later find that the same $15,000 was needed for the down payment, closing costs, prepaid expenses, or reserves. The right strategy depends on the whole mortgage file, not just the credit card balances.
Paying Down Credit Cards After Pre-Approval.
Even though a borrower can pay off their credit card balances after getting pre-approval, the loan officer should still be involved before the payment is made. The loan officer can determine how much DTI needs to be reduced and identify which debt provides the greatest qualifying benefit for the least cash spent. Imagine two cards: one needs a $200 payment and has a small balance, while the other needs $95 but has a much bigger balance. If the goal is to lower DTI, paying off the first card yields a greater benefit despite the smaller amount. This shows that paying off the largest balance first is not always the best way to qualify for a mortgage.
How Underwriters Verify a Credit Card Was Paid
Even after the borrower has made a payment, the first mortgage credit report can still show the old balance. Creditors do not update all three credit bureaus at the same time after each transaction.
Depending on what needs to be shown, the lender may request an updated account statement, transaction history, proof of payoff, a credit supplement, or a rapid rescore through its credit-reporting service.
A rapid rescore is not the same as credit repair and does not remove accurate negative information; it is a process used by mortgage professionals to ask for a faster update of verified credit information. The lender decides if a rapid rescore is needed. Will paying off credit cards raise your credit score?
How Credit Utilization Can Hurt Borrowers Applying for a Mortgage
Many credit accounts can benefit from lowering revolving use, as borrowers use a smaller part of their available credit. Mortgage credit scores are affected by many factors, and two borrowers who reduce their credit card debt by the same amount might not see the same changes in their scores. Another reason one should not make major credit decisions during the underwriting process based on an online credit score simulator is that. To both lower the DTI and improve scores, the loan officer should review the accounts that affect mortgage approval and determine whether a rapid rescore is needed.
Do Not Charge the Cards Back Up Before Closing
Paying a credit card down to zero and then using it again before the credit card account is closed can cause another approval problem. Before the mortgage is finalized lenders can obtain updated credit information; new debts or higher balances could affect the debt‑to‑income ratio. Might require the file to be reviewed again. When getting a mortgage people should be especially careful about making purchases, like furniture, appliances, vehicles, home improvements, holidays or similar expenses until the mortgage money is available. Buying the house and furnishing it should be seen as two financial events. Complete the mortgage closing.
Do Not Open New Credit While the Mortgage Is Being Approved
Opening a new account could result in an additional credit check and, more importantly, a new monthly payment. The lender might still need to check recent credit inquiries to see whether additional debt has been added, even if the new account does not yet appear on the credit report. Someone who is already near their maximum DTI has very little room to make extra payments. A monthly payment of $75 might be enough to get approval. Before you finance anything during the mortgage process, you should talk to the loan officer handling your file.
Do Not Borrow Money to Pay Off Credit Cards Without Informing the Lender
Just because debt is moved from one account to another does not mean it will improve your chances of getting a mortgage. The other option is to determine which of the monthly obligations provides the best chance of reducing the ratio. The third of these involves making sure that a sufficient amount of acceptable funds remains for the closing costs, for prepaid expenses, for reserves, and for other requirements. The borrower should make the payment and supply the documentation requested by the lender at that point.
The lender might also have to check where large deposits made to pay off debt or to fund the closing came from. People must never attempt to conceal the money they have just borrowed from the mortgage company.
For example, a personal loan that has not been disclosed could be used to pay off credit card debt, thereby eliminating several revolving payments and establishing a new installment payment. The new debt must be included when the loan program requires it.
Using Cash to Lower DTI Without Becoming Short of Funds
A major mistake we observe among borrowers with a high DTI is focusing solely on the ratio and thereby neglecting the asset portion of the loan. Let us assume that the person who owes money has $30,000 in verified savings.
A down payment of $20,000, along with closing costs, prepaid expenses, and reserves, may be required, but that doesn’t mean the remaining $10,000 should simply be used to pay off credit cards.
There could also be further underwriting conditions, additional appraisal-related expenses, changes to the insurance, or final cash-to-close adjustments. The loan officer must determine how much of the borrower’s cash can safely be applied toward paying off debt before the payment is made.
A Common High-DTI Mortgage Scenario
This is the kind of situation we frequently encounter at Gustan Cho Associates. A person applying for a loan receives pre-approval with a debt-to-income ratio that is valid but near the underwriting limit.
Once the person who borrowed the money has found a house, the cost of homeowners’ insurance exceeds the estimated amount, property taxes are slightly higher, and the final mortgage payment increases as well. The borrower’s DTI has now exceeded the acceptable level.
Rather than immediately deciding that the borrower no longer qualifies, we review each liability separately. If a credit card has a balance of $2,500 and requires a monthly payment of $125, then paying off that account completely might reduce the amount of debt each month enough to bring the file back within the required range. One borrower might have to manage two accounts, while in some instances,, settling the debt may not be the best option because the borrower needs the money for closing costs.
Paying Down Debts to Lower Debt-to-Income Ratios
The strategy is different for every borrower. Before suggesting that a borrower transfer funds, we review the real DTI shortfall, qualifying income, proposed housing payment, minimum credit card payments, remaining verified assets, reserve requirements, loan program, AUS findings, and any lender-specific conditions.
It is more useful to handle each file separately than to ask every high-DTI borrower to pay off all their credit cards. When deciding whether to pay off a car loan or credit cards, the debt to pay off is the one that provides the required qualifying benefit while using an acceptable amount of the borrower’s available funds.
Next, we check whether paying off debt actually resolves the problem. It is not necessary to use $20,000 in cash since a smaller, targeted amount can eliminate $50 or $75 of monthly liabilities. In some cases, paying off the debt is insufficient, and the loan structure must be examined differently. Affirm benefit while using an acceptable amount of the borrower’s available funds.
Struggling with High DTI? Let’s Help You Pay Down Credit Cards and Improve Your Mortgage Approval!
Reach out now to get advice on how paying down debt can improve your mortgage application.Type of Installment Loans Exempt From Debt-to-Income Calculations
An installment loan. For instance, Fannie Mae usually permits some installment debt with 10 or fewer payments remaining to be excluded, even though the payment might still have to be taken into account if it has a significant effect on the borrower’s ability to meet their credit obligations. Since such differences exist, borrowers ought not to select which debts to pay off based solely on the balances.
What If the Credit Report Does Not Show a Minimum Payment?
What if the Credit Report Doesn’t List the Minimum Payment? Based Only on Balances?
This deserves attention. For Fannie Mae, if a revolving account fails to display an acceptable required payment and the relevant documentation is not available, the FHA also provides procedures for revolving accounts when the payment is not properly stated in the credit report. A missed payment ought to be addressed rather than ignored.
A missing payment should therefore be reviewed. It is useful to pay down credit card debt if doing so actually improves your chances of qualifying for a mortgage. Lower credit utilization means higher scores.
A missing payment should be reviewed. Paying down credit card debt is useful only if it improves your chances of qualifying for a mortgage. It is unhelpful if it leaves the borrower without sufficient funds for the final payment, eliminates required reserves, requires additional borrowing, or fails to reduce the qualifying monthly payment enough to fix the DTI problem.
Restructuring the Purchase Price, Loan Program, and Rates to Lower DTI
Sometimes altering the purchase price, loan amount, insurance coverage, loan program, interest rate, or another part of the transaction may yield a better outcome. The aim of underwriting is not just to achieve the lowest DTI but to arrange a mortgage the borrower can qualify for and reasonably carry. The closer a borrower is to the qualifying limit, the more important a sound financial profile becomes.
Small increases in credit card payments, homeowners’ insurance, property taxes, HOA fees, or other monthly payments can make a difference. There is no need to transfer money between accounts unnecessarily.
Avoid opening new credit, using funds to finance a vehicle, making large unexplained deposits, or co-signing new loans. It is an effective way to deal with a high-DTI problem: paying off credit cards while having a mortgage, but the payoff should be planned, not guessed. The first thing to do is to establish precisely how much the borrower’s DTI exceeds the acceptable level.
Alternative Strategies on Making a Mortgage Loan Work
At Gustan Cho Associates, we frequently deal with borrowers who have high debt-to-income ratios, complicated credit histories, or mortgage applications that require detailed underwriting. If another lender has said your DTI is too high, it might be a good idea to review the file before concluding that the mortgage cannot proceed. The mortgage guidelines and the AUS findings depend on the particular loan program and the borrower.
A properly organized file can include options that were not considered when the original pre-approval was granted. You include options that were not considered during the original version pre-approval.
This guide covers paying down credit cards during mortgage process due to high debt-to-income ratios. Debt-to-income ratios are one of the most important factors in the mortgage approval process. Paying down credit cards during mortgage process should be done if possible. High DTI borrowers should pay off all higher credit card balances before starting the mortgage process. There are strict debt-to-income ratio cap requirements.
How the Automated Underwriting System Determines DTI vs Credit Scores
HUD debt‑to‑income ratio limits stand at 46.9 percent for the front‑end and 56.9 percent for the back‑end. These limits generally cover borrowers whose credit scores reach 620 or higher. When a borrower’s credit score falls below 620 the approved debt‑to‑income ratio usually drops. This adjustment gives the borrower a chance to gain approval through the automated underwriting system.
What are Debt-to-Income Ratio Caps on Mortgage Loans
Each loan program sets its debt‑to‑income ratio caps. FHA loan programs demand, via the Automated Underwriting System, a debt‑to‑income ratio of 46.9 percent for the front‑end and 56.9 percent for the back‑end, per HUD lending guidelines. VA loans however impose no debt‑to‑income cap.
The team at Gustan Cho Associates has seen many borrowers on VA loans exceed 60% DTI with strong compensating factors. USDA loans cap DTI at 29% front-end and 41% back end.
In the case of conventional loans, the maximum allowable debt-to-income ratio for an approved/eligible status through the Automated Underwriting System is 50% DTI. Conventional loan programs do not have front-end debt-to-income ratio caps. The subsequent paragraphs will discuss the significance of paying down credit cards during the mortgage process, particularly when faced with high debt-to-income ratios.
Is it Possible to Pay Off the Credit Card Debt While My Mortgage is Being Reviewed?

It is possible for borrowers to pay off their credit card balances at the underwriting stage if appropriate in the circumstances of the loan file. However, you should first consult the loan officer so that the lender can work out the amount of the payoff required, the acceptable means of funding it, and the documentation needed to amend the file.
- How long does it take for a credit card that has been paid off to appear on a mortgage credit report?
- How long does it take for a paid-off credit card to show on a mortgage credit report?
- The normal creditor reporting cycle can take time, and timing differs among card issuers.
- A mortgage lender may be willing to clear all of my credit card debt to help me qualify for a mortgage.
- When appropriate, request a rapid rescore rather than waiting for the next regular reporting cycle.
Will Paying Off All My Credit Cards Help Me Qualify for a Mortgage?
Not necessarily. Paying off revolving debt can reduce monthly obligations and potentially improve revolving utilization, but is it necessary to close a credit card after paying it off if I want to qualify for a mortgage? The loan officer should calculate the benefit before you pay the accounts.
Does a Credit Card Have to be Closed After I Pay it Off to Qualify for a Mortgage?
Not under Fannie Mae’s general rule for revolving debt paid off at or before closing. Fannie Mae states that the account need not be closed for the monthly payment to be excluded.
- Once the lender has verified that my credit card balance is zero, will I be able to use the cards again?
- If the card is used again before the closing date, it could result in a new balance and a monthly payment that might have to be taken into account.
- People who have paid off their debt to qualify should usually avoid making any new purchases before the mortgage is closed, unless the loan officer assures them that this will not affect the transaction.
- The mortgage closes unless the loan officer confirms that they will not affect the transaction.
- When it comes to dealing with DTI, it might be more effective to pay off the account that removes the most monthly debt while requiring the least amount of cash.
- Regarding credit scores, several usage factors can be important.
- The optimal approach will vary depending on whether the primary aim is to reduce the DTI, improve credit scores, or achieve both.
Mortgage guidelines change, individual lender requirements may differ, and every borrower’s financial profile is unique. The specific underwriting findings and loan program should always be reviewed prior to making significant financial changes during the mortgage process.
Borrower Paying Down Credit Cards During Mortgage Process

Here is a case scenario where a borrower is paying down credit cards during mortgage process due to high DTI. If the mortgage loan underwriter deducts part of the borrower’s gross monthly income because they took write-offs on their tax returns, that may boost the debt-to-income ratio threshold above the maximum allowed.
Paying down credit cards during mortgage process can be a solution to lowering the borrower’s debt-to-income ratios. Lowering the mortgage rate to lower the mortgage payments can be done by buying discount points.
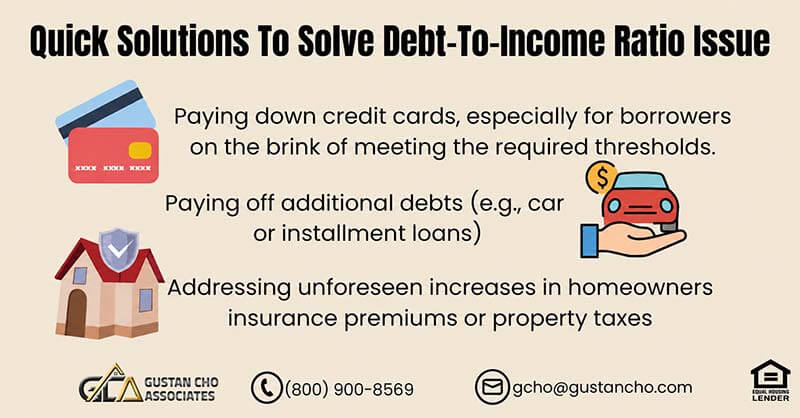
Another solution is paying off debt such as a car or installment loan. If homeowner insurance premium comes in higher than the original estimated amount, that too may exceed the maximum debt-to-income ratio permitted. If the property taxes exceed the amount stated on the original 1003 loan application, that too may exceed the maximum debt-to-income ratios. If the mortgage rates are higher than originally anticipated, that too can overthrow the maximum debt-to-income ratios allowed.
Quick Solution to Solve Debt-To-Income Ratio Issue
Most lenders will allow borrowers to correct the debt-to-income ratio issues during the mortgage process. If the debt-to-income ratio exceeds the maximum debt-to-income ratio allowed during the mortgage approval process, our underwriters do not deny the loan. There are ways to increase credit scores and lower debt-to-income ratios during the mortgage process, explains Dale Elenteny, a senior loan officer at Gustan Cho Associates:
Our underwriters want loan officers to devise solutions to salvage high DTI. Paying down credit cards during mortgage process may be a solution.
Occasionally, borrowers may find their debt-to-income ratio surpassing the maximum required, often because of altered circumstances, such as unexpectedly elevated homeowners insurance premiums, higher-than-anticipated mortgage rates, or unforeseen events. A swift remedy to address challenges associated with a high debt-to-income ratio involves reducing credit card balances during the mortgage application process. Minimum monthly credit card payments can range from $50 to over $200.
Fannie Mae and Freddie Mac Guidelines on Paying Down Credit Cards During Mortgage Process
As mentioned, paying down credit cards during the mortgage process can eliminate the minimum monthly payment to solve a higher-than-anticipated debt-to-income ratio. However, suppose the loan is submitted to a Fannie Mae lender. In that case, Fannie Mae requires borrowers to pay off a credit card to zero balance to eliminate the minimum monthly credit card payment. Fannie Mae is required to close out her credit card account after paying the credit card balance off. Alex Carlucci, a senior loan officer and credit repair expert, explains about lenders making you pay down credit cards during the mortgage process and closing them out at the same time:
Many borrowers do not like the fact that they need to close out their aged credit card accounts. But this is not the mortgage lender’s rule but Fannie Mae’s. Freddie Mac allows borrowers paying down credit cards during mortgage process to a zero balance.
Freddie Mac does not mandate the closure of credit card accounts. Loan officers need to submit mortgage applications to a lender affiliated with Freddie Mac. Fannie Mae and Freddie Mac follow distinct mortgage guidelines, and typically, lenders prefer Fannie Mae over Freddie Mac.
Is There a Way To Avoid Closing Out Credit Card Account After Paying Off Credit Cards
With a higher debt-to-income ratio, borrowers must consider paying off all credit card balances before starting the mortgage process. Paying down credit cards during the mortgage process causes a delay in the loan process. The mortgage processor can do a rapid rescore after the borrower pays down credit card balances to expedite the restoring process so the borrower can increase the credit score to qualify for a mortgage, explains Angie Torres, the national operations manager at Gustan Cho Associates about paying down credit cards during mortgage process as follows:
After paying down credit cards during mortgage process, the lender needs to do a rapid rescore and ensure the borrower’s credit is updated. A rapid rescore updates the borrower’s updated credit through a third-party credit agency in three to five days.
Engaging in a credit supplement or rapid rescore allows the borrower to receive an updated credit report without waiting for the standard 30-day period. Borrowers with higher debt-to-income ratios should settle credit card payments before initiating the mortgage process. Despite the expedited nature of a rapid rescore, it can still lead to a delay of two weeks or more in the mortgage process, potentially impacting the closing of the home loan.
- Related> Solving high debt-to-income ratios
- Related> Mortgage denial due to high debt-to-income ratio
- Related> Maximum debt to income ratios for AUS Approval
- Related> Low credit scores and high debt-to-income ratios
- Paying Down Credit Card Balances To Boost Credit Scores
If you have any questions about paying down credit cards during mortgage process due to high DTI, please contact us at Gustan Cho Associates at 800-900-8569. Text us for a faster response. Or email us at gcho@gustancho.com. The team at Gustan Cho Associates is available 7 days a week, on evenings, weekends, and holidays.
FAQ: Paying Down Credit Cards During Mortgage Process Due To High DTI
Why is it important to pay down credit cards while you are applying for a mortgage?
Reducing credit card debt can change your debt‑to‑income ratio a lot. That ratio is key when a lender decides whether to give you a mortgage. If the ratio is too high lenders might refuse the mortgage. Offer a higher interest rate.
What are debt‑to‑income ratios. Why do they matter?
Debt‑to‑income ratios compare the money you owe each month to the money you earn each month. Lenders look at this number to see if you can handle a debt, such as a mortgage while still paying your other bills.
How can I tell if my debt‑to‑income ratio is too high for a mortgage?
Most lenders set a limit for the debt‑to‑income ratio when they decide on a mortgage. The limit depends on things like your credit score and the type of loan. It usually falls between about 43 % and 57 %. If your ratio goes over that limit your mortgage application can be at risk.
What can happen if my debt‑to‑income ratio is too high during the mortgage process?
A high debt‑to‑income ratio can cause the lender to refuse the mortgage or to approve it with conditions, such as a higher interest rate or a larger down payment. Lenders think a high ratio shows that you are under strain and that they face more risk.
How can paying down credit cards help lower my debt‑to‑income ratio?
When you pay off credit card balances your monthly minimum payments. That lowers your debt‑to‑income ratio. The lower ratio makes you an appealing borrower and can improve your likelihood of getting a mortgage or getting better loan terms.
Are there specific guidelines or rules about paying down credit cards during the mortgage process?
Different lenders can have their rules about paying down credit cards and the rules can change depending on the loan program and underwriting standards. For instance Fannie Mae might require that you pay off a credit card balance completely and close the account so that you have no payment left.
Can Paying Down Credit Cards Cause Delays in Mortgage Process?
Yes, paying down credit cards can potentially cause delays, especially if the lender needs to perform a rapid rescore to update your credit report. This process may take a few days to a couple of weeks, impacting the timeline for closing on your loan.
How can I speed up the process of paying down credit cards while I am applying for a mortgage?
To speed things up talk with your lender and act quickly to fix any problems that affect your debt‑to‑income ratio. You might look at options such as rescoring which updates your credit report fast and helps your mortgage application move along, on time.
Can Paying Off Credit Card Debt Help to Secure a Mortgage That Has Been Rejected Because of a High DTI?
In some cases, when the DTI exceeds the underwriting requirement due to revolving payments, a documented payoff can bring the ratio into an acceptable range. However, it will not address all high-DTI cases, so the loan should be recalculated before any funds are disbursed.
Should I Pay Off My Credit Card Balances to Zero Before I Get Pre-Approved?
Disbursals: It is not automatic. It is a good idea to check the accounts before granting pre-approval, but borrowers should first determine how much cash they will need for the mortgage transaction. In most cases, focusing on reducing debt is more useful than paying off each account completely. In any case, targeted debt reduction is more useful than paying. It doesn’t always mean the mortgage transaction is over when the debt-to-income ratio is high.
This Guide About Paying Down Credit Cards During Mortgage Process Due to High DTI Was Updated on September 22, 2026.