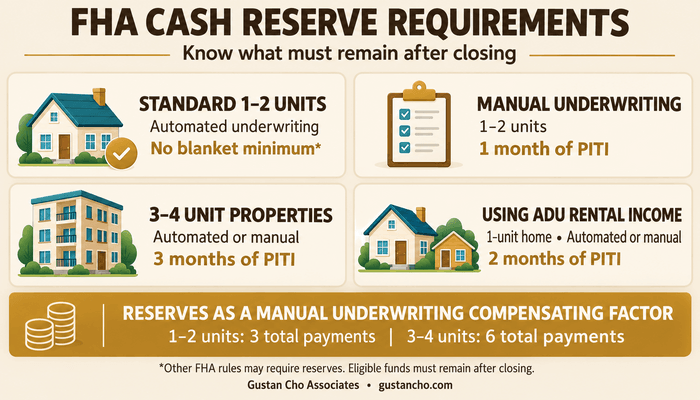
HUD reserve requirements depend on the property type and how the FHA loan is underwritten. A standard one-unit FHA loan with acceptable automated underwriting may not require reserves, while manual underwriting generally requires at least one month of PITI for one- and two-unit properties. FHA requires three months of PITI for three- and four-unit properties and two months of PITI when qualifying with rental income from an ADU on a one-unit home. Additional reserves may also help as a compensating factor on a manually underwritten loan.
FHA Reserve Requirements at a Glance
FHA reserve requirements depend on the property type and underwriting method. Required reserves must consist of eligible, verified assets remaining after the borrower pays the required funds to close.
| Borrower/property situation | Basic FHA reserve requirement |
|---|---|
| Standard one- or two-unit property with acceptable automated underwriting | No blanket minimum under the general reserve provision; other applicable requirements still apply |
| Manually underwritten one- or two-unit property | One month of PITI |
| Three- or four-unit property, automated or manual underwriting | Three months of PITI |
| One-unit property using accessory dwelling unit (ADU) rental income to qualify, automated or manual underwriting | Two months of PITI |
The ADU requirement applies when qualifying ADU rental income is used. For example, a manually underwritten one-unit property using that income requires two months of PITI, rather than the ordinary one-month minimum.
Higher Reserves Used as a Compensating Factor
Meeting the basic reserve requirement does not automatically qualify cash reserves as a compensating factor for manual underwriting. For that purpose, HUD requires at least:
- Three total monthly mortgage payments for one- or two-unit properties.
- Six total monthly mortgage payments for three- or four-unit properties.
These are total reserve thresholds, not additional months added to the basic minimum. For example, the six-payment threshold for a manually underwritten four-unit property means six total monthly payments in eligible reserves after closing—not nine.
What Are FHA Cash Reserves?
FHA cash reserves are eligible funds the borrower has left after paying the required down payment, closing costs, prepaid expenses, and other cash needed to close. Reserves are not additional money paid to the lender. They remain available to the borrower after closing.
How FHA Measures Reserves Against Your Housing Payment
FHA reserve requirements are expressed as a multiple of monthly housing payments. PITI stands for principal, interest, taxes, and insurance, but borrowers should account for all applicable charges included in FHA’s qualifying mortgage payment. These costs include:
- Principal and interest: The monthly payment toward the mortgage balance and interest.
- Property taxes: The monthly amount allocated for real estate taxes.
- Homeowners insurance: The monthly cost of coverage protecting the property.
- FHA mortgage insurance premium (MIP): The monthly mortgage insurance charge, which is separate from homeowners insurance.
- Flood insurance: The monthly insurance cost when applicable.
- HOA or condominium fees: Required association dues or expenses.
- Other applicable obligations: Ground rent, special assessments, payments on acceptable secondary financing, and other required escrow payments.
A charge may count toward FHA’s qualifying housing payment even when the borrower pays it separately from the mortgage servicer.
Minimum Reserves and Compensating-Factor Reserves
HUD describes basic minimum reserve requirements in months of PITI. Its separate cash-reserve compensating-factor requirements use total monthly mortgage payments. For a manually underwritten loan, using reserves as a compensating factor requires at least:
- Three total monthly mortgage payments for a one- or two-unit property.
- Six total monthly mortgage payments for a three- or four-unit property.
These labels should not be interpreted as permission to leave applicable mortgage insurance or association charges out of the lender’s required payment calculation.
When Does FHA Require Reserves?
FHA does not require every borrower to have a fixed number of months of reserves. HUD reserve requirements depend primarily on whether the mortgage is automatically or manually underwritten and the type of property being financed. Reserves are specifically important for:
- Manually underwritten FHA loans.
- Three- and four-unit properties.
- One-unit properties where ADU rental income is used to qualify.
- Manual files where cash reserves are being used as a compensating factor.
A standard one-unit FHA purchase with acceptable automated underwriting does not automatically require one or more months of reserves simply because it is an FHA loan. FHA does not impose one universal reserve requirement. Use the table below to identify the basic requirement for your property and underwriting method. Required reserves must remain in eligible, verified assets after accounting for the funds needed to close. When ADU rental income is used to qualify, the two-month requirement replaces the ordinary one-unit minimum. Having an ADU alone does not trigger that requirement.
HUD Minimums and Additional Lender Requirements
 HUD sets FHA’s minimum reserve requirements. Individual lenders are free to impose more stringent requirements (so-called ‘lender overlays’), such as requiring more reserves than the FHA minimum. You need to find out whether the reserve requirement is derived from FHA guidelines, the applicable automated underwriting, or the lender’s own policy. Gustan Cho Associates’ “no lender overlays” approach does not waive the FHA requirements. The borrower is still subject to the applicable reserve rules, asset documentation requirements, and all other FHA eligibility and underwriting requirements. The absence of lender overlays does not guarantee loan approval.
Reserves for One- and Two-Unit Properties
The reserve requirement for one- and two-unit FHA properties depends on how the loan is underwritten.
Automated Underwriting
A standard one-unit FHA loan with acceptable automated underwriting generally does not have a separate minimum reserve requirement unless another FHA rule applies, such as using qualifying ADU rental income. A typical two-unit property also does not automatically fall under FHA’s three-month reserve rule that applies to three- and four-unit properties.
Manual Underwriting
For a manually underwritten one- or two-unit FHA loan, the borrower generally needs at least one month of PITI in reserves after closing. If reserves are also being used as a compensating factor, the borrower must meet the higher reserve threshold applicable to that purpose.
Need to Document Reserves for an FHA Loan?
FHA reserve requirements can depend on the property, loan scenario, and underwriting findings. Review your assets and mortgage options with Gustan Cho Associates.Reserves for Three- and Four-Unit Properties
FHA requires more reserves when the property has three or four units. For these properties, the borrower must have at least three months of PITI in verified reserves after closing. This requirement applies under the FHA’s TOTAL and manual underwriting rules.
Higher Reserves May Be Needed for Manual Underwriting
Three months of PITI satisfy the basic FHA reserve requirement. However, if cash reserves are being used as a compensating factor on a manually underwritten three- or four-unit loan, HUD requires a higher amount.
Using FHA Reserves as a Compensating Factor
Meeting the basic reserve requirement does not automatically qualify reserves as a compensating factor for manual underwriting. To use verified cash reserves for that purpose, HUD requires at least:
- Three total monthly mortgage payments for a one- or two-unit property.
- Six total monthly mortgage payments for a three- or four-unit property.
Sufficient reserves may support a manually underwritten application, but they do not replace the other FHA eligibility and underwriting requirements.
What Assets Can Be Used for FHA Reserves?
FHA reserves must come from eligible, verified assets that remain available after the borrower pays the required funds to close. Common examples include:
- Checking accounts.
- Savings accounts.
- Certificates of deposit.
- Eligible stocks and bonds.
- Brokerage and investment accounts.
- Eligible retirement accounts.
Retirement Accounts Can Count
FHA generally permits the lender to count up to 60% of the value of an eligible retirement account, minus existing loans, unless documentation proves that a larger amount would actually be available after taxes and withdrawal penalties. Examples can include:
- 401(k) accounts.
- IRAs.
- Thrift Savings Plans.
- Keogh accounts.
Only the portion not needed for closing can be counted toward reserves. The lender must also verify the account and confirm that the borrower has access to the funds under the plan’s withdrawal terms.
Assets That Cannot Be Counted as FHA Reserves
Not every asset available to the borrower qualifies as an FHA reserve. Under FHA manual underwriting, reserves do not include:
- Cash received from a cash-out refinance at settlement.
- Incidental cash received at closing.
- Gift funds.
- Equity in another property.
- Borrowed funds from any source.
HUD defines manual-underwriting reserves as the borrower’s verified and documented liquid assets remaining after deducting the required funds to close.
Gift Funds and Manual Underwriting
Gift funds can be an acceptable source for certain FHA closing requirements, but HUD specifically excludes gift funds when calculating reserves for a manually underwritten loan. That distinction matters when a borrower has enough gift money to close but still needs separate eligible assets to satisfy a reserve condition.
Equity Is Not the Same as Cash Reserves
Owning another property with substantial equity does not, by itself, create FHA reserves. Reserves need to be eligible, verified assets available to the borrower. HUD specifically excludes equity in another property from the reserve calculation.
How FHA Calculates Reserves After Closing
The basic FHA reserve calculation is: Verified eligible assets − required funds to close = available reserves
Funds Must Be Verified
The lender must verify the assets being used in the calculation. Having money available is not enough if the lender cannot document the account, ownership, value, and the borrower’s access to the funds when required. HUD’s current Handbook 4000.1 remains the controlling source for FHA reserve and asset documentation requirements.
Example: Enough Money to Close, but Insufficient Reserves
This hypothetical example illustrates FHA reserve calculations. It does not describe an actual Gustan Cho Associates borrower. Assume a borrower is purchasing a one-unit home with a manually underwritten FHA loan. No ADU rental income is being used. The lender verifies:
- $20,000 in eligible borrower-owned funds.
- $18,000 needed to close.
- $2,500 as the applicable monthly housing payment, including the required housing charges.
- No other eligible reserve assets.
After accounting for closing funds, the borrower has: $20,000 − $18,000 = $2,000 in eligible reserves. Although the borrower can cover the closing costs and down payment, the remaining funds fall short of the basic reserve requirement.
| Reserve purpose | Required reserves | Shortfall with $2,000 remaining |
|---|---|---|
| Basic manual-underwriting minimum: one month of PITI | $2,500 | $500 |
| Cash reserves used as a compensating factor: three total monthly mortgage payments | $7,500 | $5,500 |
These thresholds reflect separate FHA reserve provisions for manually underwritten one-unit properties. If eligible reserves increase to $2,500, the borrower satisfies the basic reserve condition. Reaching $7,500 satisfies the cash-reserve threshold for that compensating factor. The $7,500 is the total required for that purpose; it is not added to the basic minimum. The practical lesson is to calculate cash to close and eligible reserves together before committing funds. Having enough money for the closing transaction does not necessarily satisfy the reserve condition or establish overall loan eligibility.
What to Prepare for an FHA Reserve Review
Gather these items before your lender reviews your reserves:
- Account statements: Recent complete checking, savings, and investment statements showing ownership and balances.
- Retirement documentation: The latest account statement and withdrawal terms, including restrictions affecting access to the funds.
- Outstanding account loans: Current balances for loans against retirement accounts or other assets being considered.
- Estimated cash to close: An updated breakdown of the down payment, closing costs, prepaid expenses, and other required payments, accounting for applicable deposits and credits.
- Funds by source: Identify your own funds, gifts, and borrowed money so the lender can determine which amounts qualify as reserves.
Retirement funds require particular attention because the lender must document withdrawal eligibility, applicable terms, and existing account loans. Ask your Gustan Cho Associates loan officer to confirm the eligible amount remaining after closing before you move funds or request a retirement withdrawal.
Find Out How Much You Need in FHA Reserves
Before moving money or withdrawing retirement funds, ask your lender to confirm the applicable reserve requirement, the monthly payment used to calculate it, and which assets qualify. Have your recent account statements, estimated cash-to-close, and any retirement account withdrawal terms available. Contact Gustan Cho Associates to discuss how your property type, underwriting method, and available assets affect your FHA reserve needs.
FAQs About HUD Reserve Requirements
Do I Need a Separate Bank Account for FHA Reserves?
No special account labeled “reserves” is required. Your lender must verify that sufficient eligible assets remain after accounting for the funds required to close. Those assets may be held in qualifying bank, investment, or retirement accounts.
Must I Withdraw Retirement Funds for Them to Count as Reserves?
Not necessarily. Eligible retirement funds used only as reserves generally do not require liquidation. Your lender must verify the account balance, outstanding account loans, withdrawal eligibility, and withdrawal terms. If retirement funds are needed to close, evidence of liquidation must be provided.
Can Seller Credits Help Me Meet an FHA Reserve Requirement?
Seller credits do not count as reserve assets. However, an allowable seller credit may reduce the closing costs you must pay, leaving more of your own eligible funds available after closing. Your lender must verify that the remaining funds qualify as reserves.
This article about “HUD Reserve Requirements for FHA Loans” was updated on October 27th, 2026.