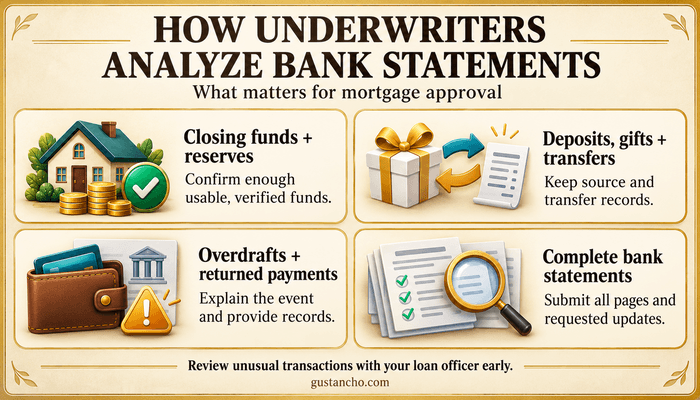
How underwriters analyze bank statements comes down to one main question: are the funds in the account acceptable, documented, and available for the mortgage transaction? Underwriters review account ownership, available balances, deposits, transfers, gift funds, overdrafts, and any activity that may need an explanation. They also confirm that the borrower has enough verified funds for the down payment, closing costs, and any required reserves. The exact documentation can vary by loan program, transaction type, and underwriting findings. This article focuses on verifying assets for closing and required reserves. For mortgages that use bank statements to calculate qualifying income, see our guide to bank statement loans for self-employed borrowers.
Funds Needed for Closing and Reserves
Closing funds cover the down payment, closing costs, prepaid expenses, and all other amounts due at settlement. Required reserves are the eligible assets remaining after closing (typically measured in months of housing payments). The reserve requirement will vary depending on the loan program, the property, and the underwriting findings.
How Much Bank Statement History Do Lenders Require?
The required history depends on the loan program, transaction type, and method used to verify assets. Two months of bank statements is not a universal requirement. For Fannie Mae loans using statement-based verification, the standard requirements are:
- Purchases: The most recent full two months of account activity.
- Refinances: The most recent full month of account activity.
For accounts reported quarterly, the most recent quarterly statement can satisfy the applicable statement-period requirement. For FHA alternative documentation, when a verification of deposit is not obtained, the lender requires a statement for the most recent month showing the previous month’s ending balance. If that prior balance is missing, statements covering the most recent two months are required.
Electronic Asset Verification and DU Findings
With the borrower’s authorization, lenders may use an approved third-party service to verify account information electronically. This can reduce the need to upload bank statements. Fannie Mae’s Desktop Underwriter (DU) findings and asset-validation messages can specify documentation that differs from the standard statement requirements. The lender must follow the applicable messages and obtain additional records when information is missing or a transaction needs clarification.
How Underwriters Review Deposits
Regular deposits like payroll, Social Security, and pensions are easy to identify since their sources match your documents. If you have a deposit that is unfamiliar or much larger than usual, you may need to provide extra records. The documents you need depend on where the money came from. If the deposit is from a sale, you may need to show proof of ownership and sale. For transfers, you might need records from the original account. If it is a gift, it must meet the program’s gift rules. The FHA, Fannie Mae, and Freddie Mac sections below explain when deposits require documentation. For Fannie Mae, clearly identified deposits generally require no additional sourcing unless the lender has questions about whether the funds were borrowed.
Transfers Between Bank Accounts
Moving money between accounts is common and does not automatically create an underwriting problem. The underwriter may need to verify the transfer when funds are moved from one account to another shortly before closing. For example, if money is transferred from savings into checking and the checking account is being used for closing, the lender may request documentation showing the funds leaving one account and entering the other.
Transfers Between Accounts Owned by the Borrower
Transfers are generally easier to document when both accounts are held by the borrower. Providing statements or transaction histories from both accounts can establish the movement of the funds without creating an unexplained deposit.
Avoid Moving Money Without a Reason
Borrowers should avoid moving large amounts between accounts simply to reorganize their finances before closing. Every additional transfer can create another transaction that may need to be documented. Keeping funds in established accounts whenever practical can make the asset-verification process easier.
Cash Deposits and Cash on Hand
Cash on hand is money held outside a financial institution. Depositing that money does not automatically make it acceptable for mortgage qualification. FHA and Fannie Mae HomeReady have specific provisions for documenting and using these funds.
FHA Cash-on-Hand Requirements
FHA permits properly documented cash on hand. The borrower must explain how the money accumulated and how long it took to save. The lender evaluates whether the savings are reasonable based on the borrower’s income, spending habits, documented expenses, and history of using financial institutions. Funds should be placed in a financial institution or kept with an escrow/title company.
Fannie Mae HomeReady Cash-on-Hand Requirements
For eligible one-unit HomeReady purchases, cash on hand may cover the down payment, closing costs, and prepaid expenses. It cannot satisfy required reserves. The lender must verify that:
- The borrower normally pays expenses in cash, and the savings fit their established payment practices.
- Credit and other records indicate limited or no credit use and limited or no banking relationship.
- A written borrower statement identifies the source and confirms the money was not borrowed.
- The funds must be placed in a financial institution or an acceptable escrow account either at the time of application or at least 30 days before closing.
Discuss cash savings with your loan officer before depositing them. Waiting a set number of days does not replace the applicable documentation requirements.
Gift Funds for Down Payment and Closing Costs
Monetary gifts must originate from a qualified donor and meet the criteria outlined by the loan program. Speak to your loan officer to confirm what documentation is required prior to the transfer of funds.
Documents to Gather for Gift Funds
Prepare the following:
- Gift letter: Complete the required form to identify the donor and the relationship, state the amount of the gift and confirm that repayment is not expected. Get the required signatures.
- Evidence of available funds (where required): A donor bank statement or some other appropriate record demonstrating that the required funds are available for the gift.
- Transfer documentation: Retain the approved electronic transfer records, the check and deposit records or the payment documentation and hand them directly to the closing agent.
For Fannie Mae loans acceptable evidence would be an electronic transfer from the donor’s account to the borrower or the closing agent or specified check and deposit records. Your loan officer will confirm what documentation is required for your program and your method of transfer.
Earnest Money Deposits
If you have already paid earnest money for your purchase, you need to provide proof of payment and ensure it matches the amount still required at closing. Your lender might also ask for evidence showing where the money came from and who received it.
Proving the Source and Receipt
- Source of Funds: To show the source of your funds, provide bank records that show the withdrawal. If needed, also provide documents that prove the money came from an acceptable source. If your earnest money was a gift, make sure it meets the gift rules.
- Proof of Funds: To prove you paid the earnest money, give a canceled check or a confirmation from the escrow company or whoever is holding the deposit. For Fannie Mae loans, you can show a canceled check or get a written statement from the deposit holder.
Applying the Deposit Toward Closing
For example, if you owe $25,000 before applying your earnest money and you have already paid $4,000, you would still need to pay $21,000, as long as there are no other changes. Make sure the credit for your earnest money matches your bank records and the final closing numbers. Remember, the $4,000 you already paid is no longer in your bank account and cannot be counted again.
Ready to Get Your Bank Statements Underwriting-Ready?
Complete a quick application or send your scenario. We’ll review your deposits, balances, transfers, reserves, and cash-to-close before underwriting.
How Underwriters Evaluate Overdrafts and NSF Activity
An overdraft or a failed payment doesn’t necessarily result in the rejection of your mortgage application. Each loan program and lender has different requirements. For instance, Fannie Mae’s nontraditional-credit guidance looks at overdrafts as part of your overall credit risk.
How to Respond to an Overdraft Condition
- Identify the event: Start by identifying the event. Write down the date, amount, and the transaction that led to the overdraft or returned payment.
- Explain accurately: If you are asked, explain clearly what happened, how you fixed the issue, and what you have done to make sure it does not happen again.
- Provide supporting records: Include any bank notices, transaction records, or other documents that help support your explanation.
- Confirm available funds: Share the updated records your lender requests to show you have sufficient verified funds for closing and any required reserves.
A letter of explanation can help clarify the situation. The underwriter will review your letter, supporting documents, account activity, and the loan requirements.
Withdrawals, Recurring Payments, and Undisclosed Debts
Bank statements can sometimes reveal financial obligations that do not appear elsewhere in the loan file.
Recurring payments to another lender, finance company, individual, or service may lead the underwriter to ask whether the borrower has an undisclosed debt.
A single withdrawal is not automatically a problem, but repeated withdrawals may require further review.
Large Withdrawals
Large withdrawals may also be reviewed if they affect the funds needed for closing or required reserves. The underwriter may need to confirm that sufficient verified funds remain in the account after the withdrawal. The focus is not on normal spending. The concern is whether the activity affects the borrower’s ability to meet the mortgage’s financial requirements.
FHA Bank Statement Guidelines
FHA lenders must verify the funds being used for the mortgage transaction and document the source of funds when required. Bank statements, deposit verification, and approved third-party asset verification may be used, depending on how the lender documents the file. FHA also requires lenders to investigate large unexplained increases in account balances and, when necessary, verify the source.
FHA Large Deposits
For FHA loans, lenders must document individual bank deposits that exceed 50% of the total monthly Effective Income. This requirement applies to both loans evaluated through the FHA TOTAL Mortgage Scorecard and manually underwritten loans. Effective Income is the verified income accepted for mortgage qualification, rather than simply the amount deposited from a paycheck. For example, if total monthly Effective Income is $6,000, the threshold is $3,000. An individual deposit of $3,500 exceeds that threshold and requires documentation showing its source. The underwriter must also verify that deposits are consistent with the borrower’s income and savings history and that no debt was incurred to fund the borrower’s minimum required investment, generally the required FHA down payment.
Conventional Bank Statement Guidelines
Conventional loans follow Fannie Mae or Freddie Mac requirements, along with the findings returned by the automated underwriting system. Both agencies require lenders to verify assets used for the down payment, closing costs, and reserves. The exact documentation can depend on the transaction and how the assets are verified.
Fannie Mae Large Deposits
Fannie Mae defines a large deposit as a single deposit that exceeds 50% of the loan’s total monthly qualifying income. For purchases: When a large deposit is needed for the down payment, closing costs, or required reserves, the lender must establish an acceptable source under Fannie Mae’s documentation provisions. If the source cannot be established, the unsupported amount must be excluded from verified assets. Enough verified funds must remain to meet the transaction’s requirements. For refinances: Fannie Mae does not require documentation or an explanation solely because a deposit is large. The lender must still account for any borrowed funds and related debt obligations. For partially documented deposits, only the unsupported portion is compared against the 50% threshold. For example, with $6,000 in monthly qualifying income, the threshold is $3,000. If a $4,000 deposit includes $2,500 from a documented source, only the remaining $1,500 is tested. That portion falls below the threshold and does not require exclusion under the large-deposit rule.
Freddie Mac Large Deposits
Freddie Mac also generally uses a 50% qualifying-income test for identifying large deposits on purchase transactions, with additional considerations when asset-derived income is used. If the deposit is needed for the transaction, its source must generally be documented. When not needed, the unverified amount may be excluded from the qualifying assets.
Illustrative Mortgage Underwriting Examples
Understanding how underwriters analyze bank statements is easier when looking at actual types of transactions borrowers encounter.
Vehicle Sale Before Closing
A borrower sells a vehicle and deposits $9,000 into a checking account. If those funds are needed for closing, the underwriter may request documentation supporting the sale and deposit, such as a bill of sale, ownership documentation, and evidence that the funds entered the account.
Savings Transferred to Checking
A borrower moves $15,000 from savings to checking shortly before closing. If both accounts belong to the borrower, the transfer can usually be documented by showing the withdrawal from savings and the corresponding deposit into checking.
Gift Funds Deposited Before Closing
A borrower receives an approved gift from an eligible donor. The lender may require a gift letter and evidence showing the transfer in accordance with the applicable loan program.
Unsourced Deposit When Enough Funds Remain
Consider a Fannie Mae purchase with these figures:
- Total monthly qualifying income: $8,000
- Account balance, including an unsupported $5,000 deposit: $30,000
- Cash needed to close: $20,000
- Required reserves: $3,000
The large-deposit threshold is $8,000 × 50% = $4,000. The unsupported $5,000 deposit exceeds that threshold. If its acceptable source cannot be established, the lender subtracts it from the account balance: $30,000 − $5,000 = $25,000 in verified assets. The borrower needs $23,000 total: $20,000 for closing plus $3,000 in reserves. The remaining $25,000 covers both requirements, leaving a $2,000 cushion. In this example, excluding the unsupported deposit allows the borrower to meet the asset requirement using the remaining verified funds.
Common Bank Statement Problems That Delay Mortgage Approval
When the lender identifies a problem, respond with records that address the specific condition:
- Missing pages: Download and submit the full bank-issued statement (including the pages that contain only disclosures).
- Unexplained transfer: Unexplained transfer: produce the records showing where the funds came from and how they moved between accounts. Match the amounts and dates of the transfer.
- Account ownership discrepancy: Obtain the bank’s records to confirm the account holder and any necessary evidence of access to the funds.
- Insufficient verified funds: Please ask your loan officer to review the acceptable additional funding sources and the amount still required for closing and reserves.
- Outdated documents: Please provide the requested updated statement, transaction history, or approved asset verification for the required period.
If the condition is unclear, ask what information or document will resolve it before submitting any further paperwork.
Tips for Preparing Bank Statements and Preventing Delays
Before you send in your asset documents:
- Check with your loan officer to find out which accounts, statement dates, and supporting documents are needed.
- Sort your documents by account, and make sure you know which transactions each supporting document relates to.
- Send your records using the secure method your mortgage team gives you.
- Talk to your loan officer about any large withdrawals, account changes, transfers, or new loans before you move forward.
- Hold on to your original records until your mortgage is finalized.
FAQs About Mortgage Bank Statements
Can I Use a Joint Bank Account for Mortgage Qualification?
Yes, when program requirements are met. The lender must verify ownership and access to the funds. An account shared with a non-borrower may require additional documentation.
Can I Use Money from a Business Bank Account?
Possibly. The lender may need to verify your ownership and assess whether withdrawing funds could harm the business, particularly when its income is used to qualify.
Can Cryptocurrency be Used for a Mortgage Down Payment?
For Fannie Mae loans, eligible proceeds must be exchanged into U.S. dollars, held at a U.S. or state-regulated financial institution, and verified before closing. Document the exchange and origin of the funds. Cryptocurrency itself cannot be used as earnest money.
Can Retirement Account Funds be Used for Closing?
Yes, subject to program requirements. Provide account statements and withdrawal terms; additional documentation may be needed to use funds for closing. Fannie Mae does not require eligible retirement funds used solely as reserves to be withdrawn.
Does the Underwriter Look at My Debit Card Purchases?
Transactions may be reviewed for undisclosed debts, reduced closing funds, or other underwriting concerns. Ordinary personal purchases are generally not the focus.
Can I Change Banks or Close an Account During the Mortgage Process?
Discuss the change with your loan officer first. The lender may need records from both accounts to trace the funds and verify the updated balance.
Can My Closing Funds Come from Multiple Bank Accounts?
Yes. The lender must verify the accounts and funds being used and confirm that the combined eligible assets cover closing and any required reserves.
This article about “How Underwriters Analyze Bank Statements for Mortgage Approval” was updated October 13th, 2026.
Bank Statements Can Make or Break Mortgage Approval
Underwriters review deposits, balances, overdrafts, transfers, large transactions, and available funds to confirm your cash-to-close and financial stability.