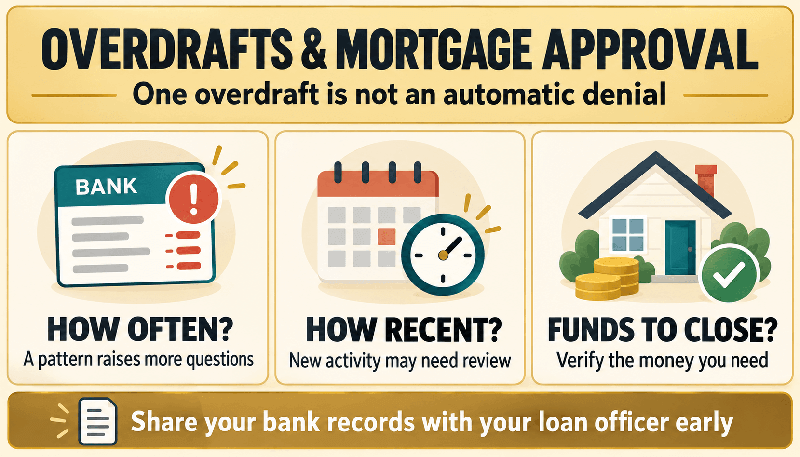
Overdrafts in bank statements can raise questions during mortgage underwriting, but one overdraft does not automatically mean your loan will be denied. Underwriters usually look at how recent the overdraft was, whether it happened more than once, how much money remains in the account, and whether you have enough verified funds for closing. If an overdraft requires an explanation, the lender may request a short letter and additional bank documentation.
How Mortgage Underwriters View Overdrafts in Bank Statements
Mortgage underwriters do not view overdrafts in a vacuum. Instead, they analyze overdrafts as part of the borrower’s more complex financial history. Individual overdrafts can happen. However, several overdrafts indicate a borrower is not in control of their finances and may overlook payments to cover other expenses. Underwriters may view the borrower’s account differently based on whether the account is being used for the down payment, closing costs, and/or reserves. The account’s transactions may prompt the underwriters to request additional documents.
What Counts as an Overdraft?
An overdraft occurs when there is not enough money in your account for a transaction, but the bank still covers the payment. This usually results in a negative balance and an overdraft fee.
A returned payment, sometimes called a nonsufficient funds (NSF) item, is different. The bank does not pay the transaction because the funds are unavailable. You may see a returned-item fee, and the company expecting payment may also charge a fee.
Mortgage underwriters may ask about either event, particularly if it happened recently or more than once. Check the transaction details on your statement before describing it to your loan officer so your explanation matches what the bank recorded.
Can an Overdraft Cause a Mortgage Denial?
An individual overdraft does not mandate a mortgage denial. However, recent overdrafts relative to the mortgage application may indicate the borrower has difficulty meeting regular obligations and may result in a mortgage denial. An underwriter may require additional documentation before making a determination on whether to approve the loan. The loan application must still meet lending standards, and the borrower’s credit, income, and assets must meet program standards.
Make Sure Your Funds to Close Are Still Strong
Overdrafts can matter more when the same account is being used for down payment, closing costs, or reserves. Get your assets reviewed before underwriting starts..What Mortgage Underwriters Look for When Bank Statements Show Overdrafts
Underwriters look at the account activity surrounding an overdraft, not just the fee or negative balance. They may consider:
- How often has it happened. One resolved overdraft may raise fewer questions than a pattern of negative balances or returned payments.
- When it happened. A recent overdraft, especially one during the mortgage process, may prompt a request for updated records.
- Whether funds are still available. If the account is being used for the down payment, closing costs, or required reserves, the lender must verify that enough eligible funds remain.
The lender may ask what caused the overdraft, whether the balance was restored, and whether the issue has happened again. You may be asked for a brief explanation, additional bank records, or updated proof of funds. The lender will assess that information alongside the rest of your application; an explanation alone does not guarantee approval.
Bank Statements and Transaction Histories for Mortgage Underwriting
The lender will choose which documents meet the requirements for your loan program and your application. Depending on the type of loan, they might use your bank statements, a verification of deposit, an approved electronic asset report, or other allowed records. A transaction history can be used only if the lender confirms it has all the needed information. If you need to provide bank statements, make sure they show the name of your bank and account holder, account details, the dates covered, all deposits and withdrawals, and the ending balance. If there is an overdraft, the lender might ask you to explain it or provide more records. It’s best to ask your loan officer what to submit instead of picking a shorter statement to leave out certain transactions.
How to Explain an Overdraft to a Mortgage Underwriter
If an underwriter asks about an overdraft, the explanation should be short and factual. A useful explanation should state the following:
- Event
- Date
- Reason
- Corrective Action
- Follow-Up
An example may be an automatic payment made before a deposit is cleared. If it was a one-time event and the account has not been in the negative since, that should be the extent of the explanation. Stories should be brief and align with bank records. These explanations will be reviewed. Note that they may not guarantee approval.
Common Overdraft Situations During Mortgage Underwriting
 Different things cause different types of overdrafts. The story often varies depending on the activity surrounding the account.
Automatic Payment Hit Earlier Than Expected
The mortgage applicant may have accurate monthly cash flow information and believe he or she has enough cash to cover automatic payment requests. However, an automatic payment may clear before the applicant expects the debit request to be processed.
Several Overdrafts Occur Before Payday
When an account consistently goes negative before payday, it can raise concerns about the applicant’s ability to manage cash flow.
Money Was Transferred Between Accounts
If an overdraft occurs during the transfer of funds between accounts, the mortgage lender may request a statement for each account, along with the transaction record, to confirm the transfer.
An Overdraft Happens During the Mortgage Process
Once an applicant is preapproved, it is important to continue good account management to avoid overdrafts. An overdraft after preapproval may lead the lender to request updated account records or an explanation. Depending on what those records show, it could result in additional conditions, a delay, or a change in the lending decision.
What to Do Before a Mortgage Application
If an applicant has overdrafts on their account statements, be sure to review the account history before submitting the mortgage application.
Ensure the funds needed for the transaction can be documented, and avoid moving funds between accounts to maintain empty accounts.
Tell your loan officer about any large or unusual deposits and keep records showing where the money came from. If you plan to transfer funds between accounts, keep records for both accounts so the lender can trace the transfer. Consult with your loan officer to resolve any overdrafts prior to starting the underwriting process. They will be able to address what, if any, additional documentation you may need based on your specific situation and your loan program.
Final Thoughts on Overdrafts in Bank Statements
Having had one overdraft does not in itself decide whether or not you are eligible for a mortgage; the underwriter will take into account when it occurred, whether it occurred again, and whether you have sufficient documented funds for the closing and for any required reserves. If your statements show recent or repeated overdrafts, tell your loan officer early. The lender may ask for an explanation or updated account records before making a decision.
Frequently Asked Questions About Overdrafts in Bank Statements
How far Back do Mortgage Lenders Look at Bank Statements?
It depends on the loan and how the lender verifies your assets. For a conventional home purchase underwritten through Fannie Mae’s Desktop Underwriter, the standard bank-statement requirement is generally two consecutive months. The lender may use an eligible alternative verification method or request more records when needed. A two-month requirement does not mean older activity can never come up.
Do Overdraft Fees Count Toward My Debt-to-Income Ratio?
A one-time overdraft fee generally is not a recurring monthly debt payment used to calculate your debt-to-income ratio. It can still reduce your account balance. If overdraft protection draws on a line of credit, tell your loan officer the amount borrowed and any required payment.
Does an Overdraft Lower My Credit Score?
An ordinary checking-account overdraft typically does not appear on a traditional credit report. An unpaid negative balance can cause other problems, particularly if the bank closes the account and reports it to a specialty checking-account reporting company. That report is different from your traditional credit report.
Can I Switch Banks After an Overdraft and Still Apply for a Mortgage?
Yes, but switching banks does not eliminate the need to document funds you plan to use for the loan. If you transfer money to a new account, keep records from both banks showing where it came from and where it went. Ask your loan officer which records the lender needs before closing the old account.
Will Overdraft Protection Prevent a Mortgage Underwriter from Asking Questions?
It may prevent a returned payment or cover a shortfall, but the resulting transfer can still appear in your account activity. Check how your protection works: money drawn from linked savings is different from money borrowed through a line of credit. Give your loan officer the details if the lender asks about the transaction.
Can Overdrafts in My Business Bank Account Affect My Mortgage Application?
They may matter if you are self-employed and the lender reviews that account for income or funds needed to close. For a Fannie Mae loan using business assets for the down payment, closing costs, or reserves, the lender must assess whether withdrawing those funds would harm the business. The lender may request additional business records to make that determination.
This article about “Overdrafts in Bank Statements: Can You Still Get a Mortgage?” was updated on September 25th, 2026.