Quick Answer: FHA guidelines on credit scores versus DTI separate financing eligibility from underwriting ratio requirements. For a standard purchase, a qualifying score of 580 or higher may permit 3.5% down; scores of 500–579 generally require 10% down. Automated underwriting evaluates the complete application, while manual underwriting uses HUD’s ratio matrix and documented compensating factors. A 620 score does not guarantee approval at a particular DTI, and a score below 620 does not automatically limit every borrower to 43%.
FHA Credit Score Requirements for Maximum Financing
For standard FHA purchase financing with traditional credit, the minimum decision credit score affects the maximum loan-to-value ratio or LTV:
| Minimum decision credit score | Standard financing treatment |
|---|---|
| 580 or higher | Eligible for maximum financing, generally up to 96.5% of adjusted value |
| 500–579 | Limited to 90% LTV |
| Below 500 | Ineligible under the standard credit-score requirement |
These limits generally translate to minimum down payments of 3.5% and 10%, respectively. FHA’s adjusted-value rules and any other applicable LTV restrictions still apply. A low appraisal or another transaction restriction can increase the cash needed. Maximum financing describes the permitted loan structure. It does not mean automatic approval or maximum DTI flexibility. The borrower must also meet applicable income, credit history, asset, property, and underwriting requirements. The policy appears in HUD Handbook 4000.1, Section II.A.2.b. Borrowers without a score have a separate nontraditional credit path, as discussed in the FAQs below.
Which Credit Score Does FHA Use?
Under the current methodology, the lender determines a minimum decision credit score, or MDCS, for each borrower. With three reported scores, the middle score is used; with two differing scores, the lower score is used. If only one is reported, that score is used. For multiple borrowers with scores, the lowest borrower MDCS applies to the transaction.
This means a co-borrower’s lower score can affect financing eligibility even when that person’s income improves the combined DTI. The lender must review both effects.
Change effective January 1, 2027: Mortgagee Letter 2026-11 updates the methodology for FHA case numbers assigned on or after that date to accommodate alternative score models. When multiple model types are submitted, the revised process selects a score within each model, determines each borrower’s score using the lowest selected result, and then uses the lowest borrower-level score for the transaction. The letter retains the existing minimum credit-score thresholds. The lender must use the methodology applicable to the FHA case number assignment date.
How FHA Calculates Front-End and Back-End DTI
FHA compares qualifying monthly obligations with the borrower’s effective income—the income the lender can document and use under FHA rules.
- Front-end ratio: Total qualifying monthly housing payment divided by monthly effective income.
- Back-end ratio: The housing payment plus other counted monthly obligations divided by monthly effective income.
The housing payment includes principal, interest, property taxes, required insurance, FHA mortgage insurance, and applicable association charges. Other obligations may include auto loans, credit card payments, student loans, and required support payments. The score is not part of either formula. For a broader explanation of the relationship between credit, payments, and qualification, see how credit scores impact DTI and mortgage approval.
FHA TOTAL Findings Versus Manual Underwriting
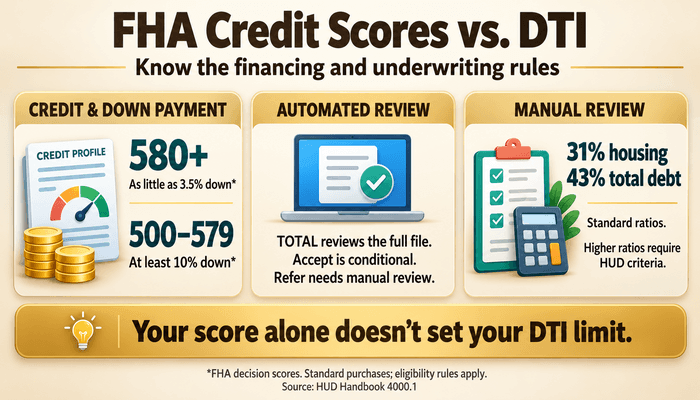
FHA’s TOTAL Mortgage Scorecard looks at your credit history and your application. The lender will access TOTAL via an automated underwriting system (AUS), and TOTAL is not an AUS. HUD describes two processing classifications:
- Accept: The application can proceed under FHA’s TOTAL underwriting without a standard manual review, unless a mandatory downgrade is in force.
- Refer: An FHA Direct Endorsement underwriter must perform the underwriting using the manual underwriting requirements.
An Accept is conditional on correct information and compliance with FHA requirements. The lender has to check the application and the property. A Refer is a referral for manual review and is not in itself a final denial. HUD also states that lenders may not approve or deny an FHA-insured mortgage solely on TOTAL’s assessment. See HUD’s TOTAL Scorecard overview and our explanation of a manual downgrade from AUS approval.
Does a 620 Score Allow a Higher FHA DTI?
There is no universal FHA rule that automatically assigns a 43% maximum DTI to every borrower below 620 and a higher limit to every borrower above it. An acceptable automated finding depends on the submitted application and applicable requirements. A manual file is provided below. Crossing 620 alone does not establish either approval or the permissible ratios. Similarly, the commonly quoted 46.9% housing and 56.9% total-debt figures should not be treated as guaranteed FHA approval levels or substituted for the manual underwriting matrix. Ask which underwriting path applies and what the verified findings actually permit.
FHA Manual Underwriting DTI Limits
HUD’s manual underwriting matrix connects the minimum decision credit score, both qualifying ratios, and specified compensating factors.
| Minimum decision credit score | Maximum front-end ratio | Maximum back-end ratio | Required support |
|---|---|---|---|
| 500–579, or no credit score | 31% | 43% | Higher ratios generally unavailable; limited Energy Efficient Home exception below |
| 580 or higher | 31% | 43% | No compensating factors required for these ratios |
| 580 or higher | 37% | 47% | One qualifying factor: reserves, minimal housing-payment increase, or residual income |
| 580 or higher | 40% | 40% | HUD’s no-discretionary-debt criteria |
| 580 or higher | 40% | 50% | Two of: reserves, minimal payment increase, qualifying additional income, or residual income |
Both ratios must fit the applicable row. A 49% back-end ratio does not qualify under the 40%/50% row if the front-end ratio is 42%. HUD permits baseline stretch ratios of 33%/45% for qualifying Energy Efficient Homes. The property must meet HUD’s criteria; ordinary energy-saving features do not automatically establish eligibility. These are manual underwriting parameters, not approval promises. The lender must also find that the credit history, income, assets, and other eligibility requirements are acceptable.
What Counts as a Compensating Factor?
Each factor has documentation requirements under Section II.A.5.d.ix of the handbook:
- Cash reserves: To use reserves as a compensating factor, eligible funds remaining after closing must equal at least three total monthly mortgage payments for a one- or two-unit property, or six payments for a three- or four-unit property. These amounts are distinct from the ordinary minimum reserve requirements.
- Minimal housing-payment increase: The new housing payment cannot exceed the current payment by more than $100 or 5%, whichever is less. A documented 12-month housing history with no more than one 30-day late payment is required; cash-out transactions have stricter payment-history requirements. This factor is unavailable without a current housing payment.
- Residual income: The lender must perform HUD’s calculation and document sufficient remaining income using the applicable household size and regional thresholds from VA’s residual income tables.
- Additional income not included in effective income: Certain overtime, bonus, part-time, or seasonal earnings may qualify when received for at least one year and likely to continue. Including that income hypothetically must reduce the ratios to no more than 37%/47%. This factor can only be used with another qualifying factor for ratios above 37%/47% and within 40%/50%.
- No discretionary debt: The 40%/40% option requires established credit lines in the borrower’s name for at least 6 months and documentation that non-housing accounts have been paid in full each month for at least 6 months. Merely having no credit history does not satisfy this test.
A stable job, larger down payment, or higher score alone is not a substitute for the listed requirements. Compensating factors also cannot be used to excuse credit history that fails FHA’s separate standards.
How Adding a Co-Borrower Can Change the Result
When you add a co-borrower, the application changes in a few ways. Qualifying income, counted debts, credit history, and the decision score for the transaction all need to be reviewed. Here’s an example with two applicants who will both live in the home, using the current single-model score method:
- John alone: $6,000 in monthly effective income, a $2,400 qualifying housing payment, and $900 in other counted monthly debts. His ratios are 40% front-end and 55% back-end. His decision score is 750.
- Mary’s contribution: $2,500 in additional eligible monthly income and $500 in additional counted monthly debts. Her decision score is 600.
- Combined application: $8,500 in income, the same $2,400 housing payment, and $1,400 in other debts. The ratios become approximately 28.2% front-end and 44.7% back-end. The transaction’s decision score becomes 600.
John’s 55% back-end ratio exceeds the standard manual matrix despite his 750 score. The combined 28.2%/44.7% ratios could fit the 37%/47% row with one qualifying compensating factor. A 600 decision score does not automatically impose a 43% ceiling. Both applicants’ credit histories and all other FHA requirements still matter; the example does not establish approval. Non-occupying co-borrowers have additional restrictions. Also, removing a spouse from an application does not necessarily remove debts FHA requires the lender to consider under community-property rules.
What to Review if Your FHA Application Does Not Qualify
Firstly, identify the real problem. A score below the financing threshold, very high manual ratios, a poor payment history, and inadequate reserves all require different approaches. Ask the loan officer to confirm:
- The underwriting path: is the application getting Accept findings, a Refer, or a manual downgrade?
- The qualifying figures: which levels of income, housing costs, and debt payments gave rise to the ratios?
- The specific rule is: is it an FHA requirement or a lender overlay?
- The available adjustment: Would a documented debt payoff, lower housing payment, eligible co-borrower, or qualifying compensating factor address the problem?
A lender may require a higher score, lower DTI, or decline to offer manual underwriting. Another lender may have different options, but it must still satisfy FHA requirements. Before using savings to pay off accounts, compare the effect on closing funds and reserves. Borrowers considering another program can review credit and DTI guidelines on conventional loans. Conventional underwriting follows separate requirements.
Frequently Asked Questions About FHA Guidelines On Credit Scores Versus DTI
Can I Get an FHA Loan Without a Credit Score?
Potentially. A missing score is different from a reported score below 500. FHA permits certain borrowers with nontraditional or insufficient credit to qualify through manual underwriting and potentially receive maximum financing. The lender must document acceptable credit references and follow the applicable ratio and income restrictions.
Can Gift Money Count Toward Manual Underwriting Reserves?
No. HUD excludes surplus gift funds from cash reserves under manual underwriting. Eligible gifts may help with the down payment or closing costs, but remaining gift money cannot be treated as the borrower’s qualifying reserve funds. Reserve calculations must also exclude other ineligible sources.
Can Authorized-User Accounts Establish No Discretionary Debt?
They cannot meet the established credit line requirement for this compensating factor. HUD requires qualifying credit lines in the borrower’s own name. An authorized-user history alone does not establish eligibility for the 40%/40% option.
Does FHA Charge Less Mortgage Insurance for a Higher Credit Score?
FHA mortgage insurance premiums are not priced by credit score in the way conventional private mortgage insurance may be. FHA’s applicable premium schedule depends on loan characteristics. An increase in score alone does not reduce the FHA premium, although other loan changes can affect the payment.
Do These Rules Apply the Same Way to an FHA Streamline Refinance?
No. This guide focuses on standard purchase qualification. Non-credit-qualifying FHA Streamline Refinances have specific exemptions from ordinary credit-score, income, and ratio requirements. Credit-qualifying Streamlines follow different requirements. The lender must determine which Streamline path applies and whether its own additional requirements affect eligibility.
This article about “Understanding FHA Guidelines On Credit Scores Versus DTI” was updated on October 29th, 2026.