
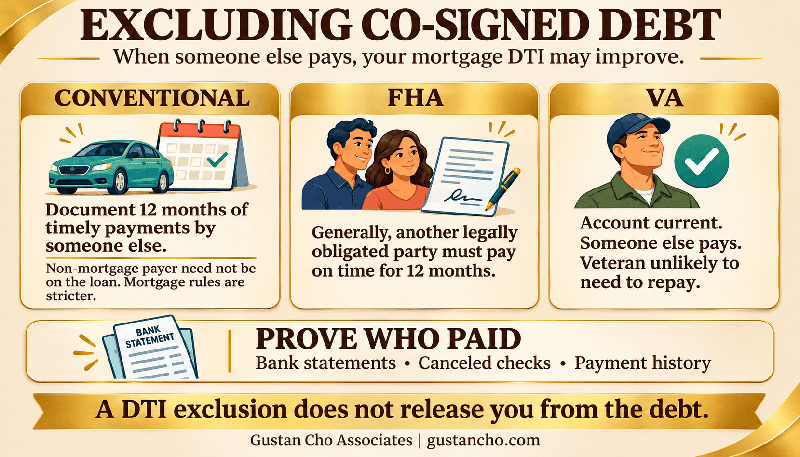
Quick Answer: Excluding debts from co-signed loans can help you qualify for a mortgage where someone else is making the payments and the loan program permits the exclusion. Fannie Mae and Freddie Mac will generally require documentation of the most recent 12 months of timely payments for their debts-paid-by-others provisions. For qualifying non-mortgage debts, the payer need not be on the account. Mortgage payments are of course subject to different rules. FHA will generally require that the payments be made by another party who is legally obligated to make them, whereas VA will look at whether you are likely to have to pay the obligation. Court-assigned debts have their own rules. An exclusion will alter your mortgage debt-to-income calculation; it will not release you from the loan.
How Co-Signed Debt Affects Mortgage Qualification
When you co-sign a loan, you take on repayment responsibility. Even if the other borrower makes all payments, the obligation can still affect your mortgage application.
Your debt-to-income ratio, or DTI, compares your qualifying monthly debt payments, including the proposed housing payment, with your gross qualifying monthly income. A co-signed payment generally counts unless the lender documents an applicable exclusion.
A co-signed debt is also different from a loan in your name alone that someone else pays. That distinction matters because some mortgage programs allow more flexibility than others. Excluding a payment from DTI does not remove the account from your credit report or end your responsibility to the creditor. Late payments on an account for which you remain responsible can still affect your credit.
Conventional Loan Rules for Debts Paid by Others
Fannie Mae and Freddie Mac allow certain debts paid by another person to be excluded from the DTI calculation. Auto loans, student loans, personal installment loans, revolving accounts, and leases may qualify under the applicable requirements.
Fannie Mae Requirements
Fannie Mae’s Selling Guide B3-6-05 allows qualifying non-mortgage payments to be excluded when another person has made the payments for the most recent 12 months without delinquencies. The payer does not have to be legally obligated on the debt and cannot be an interested party to the home purchase, such as the seller or real estate agent. The lender must obtain the other person’s canceled checks or bank statements documenting the required payment history. Mortgage debt has additional conditions. The person making the payments must also be obligated on the mortgage, and the borrower cannot use rental income from that property to qualify under this exclusion. The potential exclusion covers the full monthly housing expense, including applicable principal, interest, taxes, insurance, and association dues. The most recent 12 months of payments must be documented without delinquencies. An excluded mortgage may still count toward Fannie Mae’s limits on financed properties when those limits apply.
Freddie Mac Requirements
Freddie Mac’s Guide Section 5401.2 permits qualifying installment, revolving, and lease payments to be excluded when the file documents that someone else made timely payments for the most recent 12 months. The payer need not be legally obligated on these non-mortgage debts and cannot be an interested party in the transaction. When excluding a mortgage payment, the person making the payments must be obligated on the note. Freddie Mac allows the exclusion of qualifying property expenses, such as taxes, insurance, and homeowners association dues, if there is documented proof that another eligible party paid these expenses on time for the last 12 months. The requirement to be obligated on the note applies when the mortgage payment itself is being excluded. The lender must also evaluate whether the payment arrangement is credible and adequately supported. Meeting a payment-history requirement does not remove the need to review the circumstances.
FHA Co-Signed Debt Guidelines
 HUD Handbook 4000.1 treats qualifying co-signed obligations as contingent liabilities. These are obligations you may have to repay if another legally obligated party defaults.
FHA typically requires the monthly payment to be included unless the lender confirms that another party has made 12 months of on-time payments or provides proof that the creditor cannot hold you responsible if that party defaults.
For example, if your parent pays an auto loan that is only in your name, that arrangement does not meet FHA’s ordinary co-signed-liability exclusion simply because your parent has paid for a year. When a contingent liability arises from a divorce decree or another court order, FHA does not require the same evidence of 12 months of timely payments by the other legally obligated party. The lender must obtain the applicable court documents.
VA Co-Signed Debt Guidelines
VA’s Lenders Handbook, Chapter 4, allows a co-signed obligation to be excluded when there is evidence that someone else is making the payments, the account is current, and there is no reason to believe the Veteran will have to participate in repayment. VA does not impose a universal 12-month payment-history requirement under this provision. The lender must still document the arrangement and explain why the payment is unlikely to become the Veteran’s responsibility. A VA application also involves residual-income analysis. Excluding one obligation does not by itself establish eligibility.
Debts Assigned to an Ex-Spouse by Court Order
A debt assigned through a divorce decree or another court order is subject to different rules than an ordinary debt paid by someone else.
Fannie Mae permits a qualifying court-assigned obligation to be excluded even when the creditor has not released the borrower. The lender does not have to evaluate payment history after the assignment’s effective date, but it cannot disregard the borrower’s payment history before that date.
Freddie Mac also allows qualifying court-assigned debts, including mortgages, to be excluded upon documentation of the order. FHA requires the applicable divorce decree or court order and provides the payment-history exception described above. VA states that debts assigned to an ex-spouse by a divorce decree are generally not charged against the borrower, including those that are currently delinquent. A private agreement between former spouses should not be assumed to meet these provisions. The lender needs to review the actual legal documents. A DTI exclusion also does not mean the creditor has released you from liability.
Example: How Excluding a Car Payment Changes DTI
Imagine a hypothetical borrower with $6,000 of gross qualifying monthly income and $3,000 of monthly obligations (including the proposed housing payment). Their DTI is 50%. Those obligations include a $600 auto payment on a loan co-signed by an adult child. If the child has made the required payments and the lender has documented an eligible exclusion, then the obligations used in the calculation are $2,400. DTI is 40%. The lender would need records showing the child’s payments and would apply the requirements of the selected mortgage program. A lower DTI can help, but income, credit, assets, property eligibility, and the rest of the application still require review.
Documents Needed to Support a Debt Exclusion
The documents should show which account was paid, who paid, and whether the payment history meets the program’s rules.
If someone else paid a conventional debt, you can use their bank statements or canceled checks to show the payments came from their funds. Account statements can match withdrawals to the right debt and confirm the payment history. For a mortgage exclusion, you may also need documents showing the payer is responsible for the loan, if required.
For court-assigned debts, you need to provide the relevant decree or order. A letter stating that someone else pays the account is usually not enough to prove where the money came from or the payment history. Make sure the debt and all supporting records are checked before relying on a lower DTI for pre-approval. If statements are missing, transfers are not explained, or there are late payments, you might not qualify for an exclusion.
FAQs About Excluding Debts From Co-Signed Loans
What If the Loan Is Less Than 12 Months Old?
An account with fewer than 12 months of payments generally cannot yet satisfy the ordinary Fannie Mae or Freddie Mac debts-paid-by-others requirement. VA’s provision and separate exceptions, such as qualifying court-assigned debts, need their own review. A shorter history does not automatically mean you cannot qualify for the payment to be included.
Can Payments From a Joint Bank Account Qualify?
A joint account may require additional documentation to identify who actually funded the payments. Having the other person’s name on the bank account does not, by itself, establish that the mortgage applicant was not paying the debt. The lender must evaluate the records and the applicable program.
What If Someone Gives Me Cash or Reimburses Me?
Cash and reimbursements can make it harder to establish the payment source, particularly when the creditor receives payment from your account. Provide the full payment trail for review. Do not assume that a family member’s statement or a transfer receipt alone meets the documentation requirements.
Does a Deferred Student Loan Automatically Qualify for Exclusion?
No. A period when no payment was required does not establish that another person made the required payments. Deferred student loans have separate qualifying payment rules that the lender must review if a debts-paid-by-others exclusion is unavailable.
Can I Exclude a Debt Paid by My Own Business?
Business-paid obligations have separate requirements. The lender may need to verify a history of payments from business funds and determine how the expense was treated in the business income analysis. A business bank account alone does not establish eligibility for exclusion.
Will Excluding the Payment Improve My Credit Score?
The DTI exclusion itself does not change your credit score. It changes the monthly obligations used to evaluate your mortgage application. Credit scores and DTI are separate parts of the approval process.
Final Thoughts on Excluding Debts From Co-Signed Loans
Excluding debts from co-signed loans can make a meaningful difference when a payment is limiting your mortgage options. The outcome depends on the loan program, the type of obligation, the payment source, and the supporting records. Before relying on an exclusion, have the account and documentation reviewed. Contact Gustan Cho Associates to discuss the debt, identify which mortgage guidelines apply, and determine what records are needed for your application.
This article about “Excluding Debts From Co-Signed Loans: FHA, VA, and Conventional Guidelines” was updated on November 16th, 2026.