We will discuss qualifying for FHA loans in Utah with a FICO score under 620, including those with outstanding collections and charged-off accounts. There is a huge market for borrowers in Utah who need to be approved for FHA loans with a FICO score under 620. One thing borrowers do not realize is that not all lenders have the same FHA loan requirements. One lender may require a 640 credit score, while another may require a 580 credit score.
The team at Gustan Cho Associates gets so many phone calls daily that the first question borrowers ask me is ” Can I Qualify For FHA Loans With Under 620 FICO in Utah?”
Gustan Cho Associates has no overlays on government and conventional loans. Gustan Cho Associates are experts in originating and funding FHA loans for Utah borrowers with FICO scores under 620.
FHA Loans with Under 620 FICO in Utah: Collections, Credit, and Approval Guidelines
You could still be eligible for FHA financing even if your FHA loan application was rejected, since your credit score is under 620. This difference is important. The FHA has not established 620 as the minimum credit score required to obtain a standard loan. Under HUD guidelines borrowers who have a credit score of 580 or higher can qualify for the FHA loan amount. People with scores between 500 and 579 may still be eligible. I want to share that the FHA usually limits the loan to ninety percent of the loan-to-value ratio.
People with a credit score of six hundred, five hundred eighty, five hundred fifty or even five hundred should not think that FHA financing is, out of reach. It is important to know that options exist regardless of the number on the credit report. Each case is different. Many people find ways to qualify even when their credit score is lower, than ideal.
The final decision may be affected by collections, charge-offs, debt-to-income ratios, the applicant’s recent payment history, the amount of available assets, the applicant’s housing history, the results of the Automated Underwriting System, and any lender-specific overlays. This guide will help you understand how FHA loans work for Utah borrowers with credit scores under 620 and what you should know before you apply.
Is it possible for a person in Utah to obtain an FHA loan when the credit score is below 620?
I have seen people in Utah and I know that a credit score below 620 does not automatically exclude a person from getting an FHA loan. According to FHA guidelines a loan-to-value ratio of 96.5 percent is usually applied when the credit score is 580 or higher because 580 is considered the credit score to qualify for the maximum FHA loan amount.
If the credit score falls between 500 and 579 the FHA loan will normally be limited to a 90 percent loan-, to-value ratio. FHA-insured financing generally will not be available to anyone with a score below 500.
The documents that give the guidelines for the FHA program do not guarantee that your loan will be approved. The lender must assess the borrower’s income, employment, debts, assets, credit record, the appropriateness of the property, and the overall level of risk. In addition, the required documentation will depend on the outcome of automated underwriting or manual underwriting requirements. A lender may also specify a higher minimum credit score than the FHA requires; this additional requirement is usually referred to as a lender overlay.
FHA Does Not Require a 620 Credit Score
There is a widespread and ongoing misconception that people need a credit score of 620 to qualify for FHA financing. The FHA minimum is not that. A 620 requirement is typically established by an individual bank, a mortgage company, an investor, or a loan program.
Rather than by the state of Utah, which is why people in Utah with similar credit profiles can get very different replies from different mortgage companies.
One lender might require a credit score of 620 or 640, while another could evaluate the loan in line with FHA’s basic guidelines. If your application was turned down because your score was below 620, you should investigate whether the reason for the rejection was based on an actual FHA requirement or whether it was instead due to the lender’s overlay. This question can help you avoid giving up when there may still be options left.
FHA Credit Score Requirements for Utah Homebuyers
HUD credit guidelines on FHA loans are guidelines established by the federal government, and Utah has not set its own minimum credit score for FHA loans simply because the property is in Utah. The location of the property does affect FHA county loan limits and property requirements, but the basic credit score rules are the same across the country.
FHA Loans With a 580 to 619 Credit Score
A person who has a credit score, between 580 and 619 can buy a home by using the FHA minimum down payment of 3.5 percent. For example a homebuyer in Utah who wants to buy a $400,000 home would typically need least $14,000. This amount includes closing costs, prepaid expenses, permitted gift funds, down payment assistance and any seller-paid costs.
One factor considered in the underwriting decision is your credit score. That doesn’t mean that your application will be approved simply because your score is 580 or above.
Someone with a credit score of 590, a regular income, manageable debts, verifiable funds, and a satisfactory history of housing payments will have a risk level that is considerably different from another person who has the same credit score and who has a number of recent late payments along with a rising level of delinquent debt.
FHA Loans With a 500 to 579 Credit Score
Even though HUD mortgage guidelines allow borrowers with a credit score between 500 and 579 to get FHA loans the loan-to-value ratio is usually capped at 90%. This means that borrowers with these credit scores must make a payment of at least 10%. The lower credit score limits the amount that can be borrowed relative to the home’s value. Lenders may also have their stricter standards even if the FHA allows it. So having a credit score, in this range can make getting a loan more difficult. When someone makes a purchase, it usually means the borrower must put down at least 10%.
Before a buyer submits an offer on a property, the loans within this credit range should be carefully reviewed, and lower scores can affect more than just the down payment.
Today’s credit ratings, debt ratios, reserves, housing history, payment patterns, and the need for manual underwriting could all become rather important. It is better to have your entire file reviewed rather than rely solely on your credit score.
What We Look at When a Utah FHA Borrower Has a Score Below 620
In actual mortgage applications, the credit score by itself rarely gives the full picture. We would like to understand the reason for the score and what has recently occurred in the case of an FHA borrower with a lower credit rating. The main difference is that in one case, the person’s low credit rating is due to having used a lot of their credit card, while in the other, the person continually makes late payments.
We look in detail at the applicant’s most recent payment record, their housing history, their use of revolving credit, their installment debts, the collections, the charge-offs, their available funds, their reserves, the consistency of their income, their employment situation, their debt-to-income ratio, and the outcomes given by the underwriting system.
We also identify issues that can be addressed before the loan reaches the underwriting stage. Instead of trying to influence your credit score or disputing each negative item, you should not make any unnecessary changes to your credit record either at the time or just before you apply for a mortgage, since this could lead to additional problems. First, gain a clear understanding of your current situation, then determine the best approach to moving forward.
Can you get an FHA Loan in Utah When You Have Overdue Collections?
It is in fact the case that having collection accounts does not automatically disqualify you from getting FHA financing. The key issues concern the kinds and quantities of the collections and the way in which they must be handled when assessing the borrower’s ability to repay the mortgage.
Low Credit Score? FHA Financing May Still Be Possible
Utah homebuyers with lower FICO scores, collections, charge-offs, or past credit issues may still qualify depending on the full loan file and lender requirements.FHA Treatment of Non-Medical Collections
The FHA has a high threshold when it comes to collection accounts. No threshold, traditionally, if the total amount of outstanding collections reaches or goes above $2,000 the lender has to consider collection debt when doing the borrower’s capacity analysis.
Depending on the Circumstances, the Lender May:
- Ensure that the payment for the collection has been made in full, either before or at the time of closing, with funds that are acceptable.
- Make a payment agreement with the creditor who has properly documented it and include the monthly payment required by that agreement in the borrower’s debt-to-income ratio.
- If there is no documented agreement regarding a payment, then calculate a monthly amount equal to 5 percent of the current collection balance and include this amount in the debt-to-income ratio.
That is why you shouldn’t automatically pay off your collections just because you are applying for a mortgage. It doesn’t mean that clearing a collection is always the best use of your money, and you should first consider the effect it will have on your assets, your qualifications, and the whole mortgage file.
Example of FHA Collection Debt Treatment
Suppose that a person who is borrowing in Utah has $6,000 in unpaid collection accounts which are relevant and has no written payment agreement.
Using the 5% Method
The Lender Would Calculate a $300 Monthly Obligation:
- $6,000 × 5% = $300
- The $300 amount could be included when working out the borrower’s debt-to-income ratio.
- Even if the balance on the collection does not stop the loan, the monthly obligation might affect the transaction.
- A smaller monthly payment, properly arranged in writing, could result in a different DTI figure, provided the FHA documentation requirements are met.
What About Medical Collections?
The guidelines set out by the FHA address medical collections differently. It is not necessary for medical debts to be paid or settled in order to obtain FHA financing, and they are therefore excluded from the standard calculation of collection-account capacity mentioned above. That doesn’t mean the whole credit record is ignored; the underwriter still looks at the borrower’s general credit position and other significant credit matters. What you need to bear in mind is that you need not assume that a medical bill must be paid before the closing occurs. When applying for an FHA loan, is it necessary to pay the balance on accounts that have been charged off? The answer is NO. Borrowers do not have to satisfy outstanding collections and charge-off accounts to qualify and get approved for an FHA loan.
A Charge-Off and a Collection are Not Identical
The current FEDS state that charge-off accounts need not be included in the borrower’s liabilities or monthly debt, even if the balance remains. The account could still appear on the credit report and adversely affect the borrower. This point is important since some people are advised to pay off each old collection and charge-off before applying for a mortgage. The manner in which the FHA deals with each derogatory account is not the issue. Before you spend any money rooting out old debts, you should take a look at your whole credit report.
Why Recent Credit History Can Matter More Than an Old Collection
The story which the fact that a collection is five years old tells an underwriter is different from the story of having missed a payment last month. The underwriters would like to determine whether the financial difficulty occurred in the past or is still ongoing. You might have a stronger claim than your credit score indicates if you went through a difficult period a few years back but have been paying your rent, car loans, credit card bills, and all other bills on time since then.
Late Payments in Recent Times Should Receive Special Attention
Even if a borrower meets FHA’s minimum credit requirement, problems such as late mortgage payments, difficulties making rental payments, frequent delinquencies on revolving credit, the opening of new collections, or having several accounts now delinquent can still make the FHA file very difficult to handle. Which is why, when we look at a difficult credit file, we concentrate on the borrower’s financial behavior over the past 12 months.
FHA Automated Underwriting With a Credit Score Below 620
The majority of FHA cases start with an Automated Underwriting System. The FHA TOTAL Mortgage Scorecard works with the lender’s AUS to assess various aspects of the application, and the outcome may prompt the lender to choose an automated underwriting process or require manual underwriting.
The system takes into account a great deal more than just factors such as income, debt, loan-to-value ratio, assets, credit history, payment patterns, and other risk characteristics that may affect the results.
You shouldn’t assume there is a single DTI limit just because your credit score is below 620 when it is 600. This is one of the areas where the older version of this article needed work. There is no single FHA rule that states that all borrowers with a score below 620 are restricted to a 43% back-end DTI, whereas all those with a score above 620 can automatically have a 56.9%. Automated underwriting takes into account more than just your credit score.
FHA Manual Underwriting with Low Credit Scores
When an FHA loan needs manual underwriting, HUD gives specific rules for qualifying ratios. For people with a Minimum Decision Credit Score between 500 and 579, the standard maximum ratios used in manual underwriting are generally 31% for housing expenses relative to income and 43% for total debt relative to income. However, FHA’s manual underwriting guidelines do not include the same compensating-factor higher ratios for this score range.
For borrowers with qualifying scores of 580 or higher, manually underwritten FHA loans start with the standard 31%/43% framework, yet may permit higher ratios when HUD-defined compensating factors are present
In each case, the factors that serve as compensation might include verified cash reserves, a minor payment shock, qualifying residual income, or other factors specifically recognized by FHA. Avoiding a bad credit history is not the only reason for carrying out manual underwriting. It is a distinct method of underwriting with its own set of documentation, payment history, ratios, and requirements regarding compensating factors.
Lender Overlays Can Be the Real Reason for an FHA Denial
The fact that a loan meets the minimum program requirements does not mean every FHA lender must approve it. Mortgage companies can use lending rules that are stricter than the FHA’s minimum requirements.
A Lender Might Require:
- A score of at least 620 or 640.
- A reduced debt-to-income ratio.
- Additional reserves.
- Having a stronger record of renting or owning a home.
- Adding more seasoning after a major derogatory credit event.
- Manual underwriting is subject to certain limitations.
- There are further requirements that apply to borrowers who have made recent late payments.
- The requirements concern lender risk management, but they are not the same as FHA’s minimum guidelines.
- When a lender says that ‘FHA requires a 620 score’, you should investigate whether 620 actually is a requirement set by FHA or whether it is a requirement of the lender’s own making.
- It is necessary to know the correct answer.
Should a Low Credit Score Make You Wait Before Buying?
Not always.In some cases it is wise to wait. In other cases waiting may not help at all. Take the example of a borrower who has a credit score of 575. That score is low because the borrower has credit cards that are close to their credit limits. When a borrower has credit cards near their limit it shows a level of debt usage, which hurts the credit score.
If the borrower pays down those credit card balances the credit profile may improve significantly. That improvement could push the borrower’s score above 580. Once the score goes above 580 the borrower becomes eligible for a down payment. For instance the required down payment might drop from 10 percent to 3.5 percent. That change can make homeownership more affordable. So, in this case waiting to pay off some debt might be the move. It might have an effect on the transaction.
Another borrower could have a 605 credit score, along with older derogatory accounts, a good recent payment history, adequate income, and sufficient assets to qualify. It would do very little to wait several months to reach an arbitrary score of 620. You must take your overall mortgage situation into account when making your decision, not merely your credit score objective.
Be Careful With Credit Repair During the Mortgage Process
You might encounter unexpected difficulties if you try to improve your credit score before examining your mortgage file. Don’t proceed at once with challenging every collection; rather, before carrying out any of the actions listed below—such as opening new credit cards, closing existing accounts, moving large sums of money, or paying off old debts—you should talk it over with the loan adviser who is looking after your mortgage.
Even though making a payment could reduce the amount of cash needed for the down payment or the closing costs, it may not reach the result the borrower had hoped for.
It’s a good idea to review your credit card utilization, but the goal should be guided by your actual credit report and mortgage plan. No one can responsibly guarantee that a specific action will raise your FICO score by a certain number of points.
FHA Loans With Lower Credit Scores
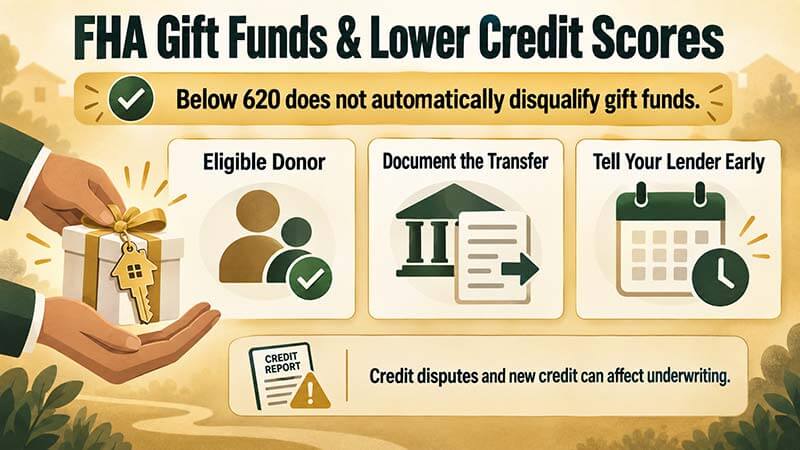 HUD will permit the use of the gift funds provided that the requirements of the program are met. Depending on the transaction, gift funds could, in principle, be used toward the borrower’s required investment, closing costs, or other allowed expenses.
Credit disputes can affect the underwriting process. Opening new credit may lead to a higher number of inquiries and result in additional responsibilities.
If your credit score is under 620, you will not be able to get an FHA loan using gift funds. In accordance with FHA guidelines, the lender is required to record information about the donor, the transfer of funds, and any other required information. You should let your lender know about the gift funds as early as possible, rather than waiting until the day before the closing.
FHA Loan Limits in Utah
FHA loan limits depend on where the property’s located and they can be different from one county to another. For example a buyer buying a home, in Salt Lake County might have a FHA loan limit compared to someone buying in another part of Utah. To find out the FHA loan limit you need to look at the county where the property is located and also the year the loan is being issued. When calculating the amount of FHA financing you can get, do not use earlier blog entries or last year’s loan limits. Before making an offer, those who are buying more expensive houses in Utah should look at the current county limit.
A Better Way to Prepare for an FHA Loan Below 620
Before you try to get an FHA loan in Utah with a credit score of less than 620, be certain that you have gathered all the information needed to review your full FHA review will only be regarded as productive if it includes your current tri-merge mortgage credit report, your most recent income proof, details of your monthly debts, your record of housing payments, your bank or asset statements, an estimate of the purchase price, the amount of the expected down payment, the balance on any collections or charge-offs, and explanations for any major recent credit problems. All we are trying to achieve is that you should not seem perfect. The aim is to determine which issues are important under FHA guidelines, which are part of lender overlays, and which must be fixed before the borrower enters into a purchase contract. This method will allow you to bypass unnecessary credit repair, stop you from paying off collections that aren’t required, and prevent yourself from experiencing unexpected surprises.
What We Commonly See in Lower-Credit FHA Files
Those who contact Gustan Cho Associates after their mortgage application is rejected usually think their credit score is the only problem. Often, it did not. We often meet situations where the principal issue is the result of a number of factors, including high revolving balances, an error in the calculation of the collection payment, recent delinquency, a high DTI, inadequate funds to carry out the transaction, the existence of a lender overlay, or a loan that had not been properly structured before the borrower signed the purchase contract. It is therefore necessary to examine the actual findings and the documentation.
A Loan Officer Should Specify Precisely What is Preventing Your Application From Being Approved Rather Than Just Saying That Your Credit is Too Low:
- At times, the best course of action is to enhance the score.
- One way to deal with the situation is to lower the DTI.
- In some cases, it is necessary to carry out underwriting manually.
- It may be that the borrower already meets the FHA requirements, but the lender will still refuse to approve the loan.
- All of these problems are different, and each one requires its own solution.
Important FHA Credit-Score Changes Coming in 2027
In September 2026, FHA announced its intention to include FICO Score 10T and VantageScore 4.0 as eligible credit score models, alongside the existing Classic FICO scoring. The HUD specified that 1 January 2027 would be the date on which applicable FHA Title II forward mortgage cases with case numbers assigned on or after that date would be implemented.
Lenders should still adhere to the current FHA credit policies when dealing with borrowers applying before the change takes effect.
This is a major update for those who are going to borrow in the future, even though it makes no difference to the present FHA eligibility rules. The mortgage credit scoring system is changing nowadays, so if you look at this guide later on, you should check which scoring model is being used at the time of your application.
Under 620 FICO in Utah After Another Lender Says No
The fact that a mortgage company has refused your application doesn’t mean that you can’t get a loan from another FHA lender. If you are making applications you should find out the specific reason why your first one was rejected. What is the Minimum Credit Score Required by the Lender? Is This an AUS Refer Finding Regarding the Score?
- Is this an AUS Refer result?
- Manual underwriting restrictions?
- Debt-to-income ratio?
- Recent late payments?
- Insufficient funds?
- Collections?
Is There a Problem with the Property in Relation to FHA or the Income?
An FHA Knowing what the actual reason is enables the next mortgage professional to decide if there is a feasible solution. It usually doesn’t help to send your file to multiple lenders without first identifying the real problem. The real problem usually doesn’t help.
Is There a Difference Between FHA Guidelines?
The FHA does not originate; mortgage insurance is provided by the FHA on loans approved and originated by approved lenders. The lenders are still responsible for underwriting the mortgage and may impose additional requirements. It is here that a great many borrowers become confused.
A lender has the right to decline a loan that falls within the basic program parameters set by the FHA. The lender is not therefore wrong, and it does not indicate that FHA has altered its rules.
It only shows that the lender is either unwilling or unable to grant that specific loan in accordance with its own lending criteria is advisable to consult a loan professional if your credit score is low, since such a professional will be familiar with both FHA’s rules and the extra requirements which can differ from one lender to another. Lender overlays on FHA loans can vary among different lenders.
Frequently Asked Questions-FHA Loans with Under 620 FICO
Here are answers to some questions about FHA loans. In Utah a 600 credit score is above the FHA minimum of 580 so you may qualify for the loan amount. Approval depends on a review of your finances including income debts assets credit history and the property. With a 550 credit score you can still buy a home under FHA rules but you will need at least a 10 percent down payment because the loan covers, up to 90 percent of the homes value. You must also meet all FHA and lender requirements.
Many People Also Ask if They Need to Pay Off Collections Before Applying for an FHA Loan.
You do not always need to pay off collection accounts to get an FHA loan. FHA rules do not require every collection to be paid. For nonmedical collections of $2,000 or more, you can pay them off, set up a written payment plan, or your lender can count 5 percent of the balance as a monthly payment when figuring out your debt-to-income ratio.
Does the Presence of a Medical Collection Prevent FHA Loan Approval?
Medical collections do not automatically lead to an FHA loan denial. FHA rules treat medical collections differently, and you usually do not have to pay them to get approved.
Is it Necessary to Pay Charge-Off Accounts Before Closing on an FHA Loan?
Charge-off accounts are not always counted as debts just because you owe money. However, lenders will still review your overall credit history and eligibility.
Should my bank not accept a credit score of 620 when the FHA permits that score?
Banks and lenders sometimes add rules called lender overlays that can be stricter than the FHA minimum requirements.
Is there a minimum credit score requirement for FHA loans in Utah?
The FHA does not set a minimum credit score, for Utah. Credit eligibility follows national rules, but loan limits and some property rules can vary by location.
Is it Advisable to Pay Off Collection Accounts Before Applying for an FHA Mortgage?
You do not have to pay off all collection accounts before applying for an FHA mortgage. Check your mortgage credit report first. While paying some collections may not be required, it can help your debt-to-income ratio or improve your chances of getting approved.
Final Thoughts on FHA Loans With Under 620 FICO in Utah
If your credit score is, below 620 it does not mean you will be turned down. Instead, your application will get a closer review. Many people are surprised by how flexible FHA rules can be. If your credit score is 580 or higher, you may qualify for the highest FHA loan amount.
Scores between 500 and 579 are still considered, but you will need a larger down payment. You do not have to pay off all collection accounts, and charge-offs are handled separately. Remember some lenders set their minimum score of 620 even though FHA does not require it. Paying attention to details can make a difference. Paying attention to details can make a big difference.
Before you pay off debts dispute accounts, new credit or try to fix your credit have your entire FHA application reviewed first. If you have been denied in Utah because of low credit, collections, charge-offs, a high debt-to-income ratio, or extra lender requirements, Gustan Cho Associates can review your situation and help you find out what is affecting your approval. If you want to discuss your FHA loan situation, call 800-900-8569 or email gcho@gustancho.com. Mortgage approval depends on a full review of your credit, income, assets, property, and program rules. FHA guidelines and lender requirements can change, and results may vary by person. Gustan Cho Associates is available 7 days a week, on evenings, weekends, and holidays.