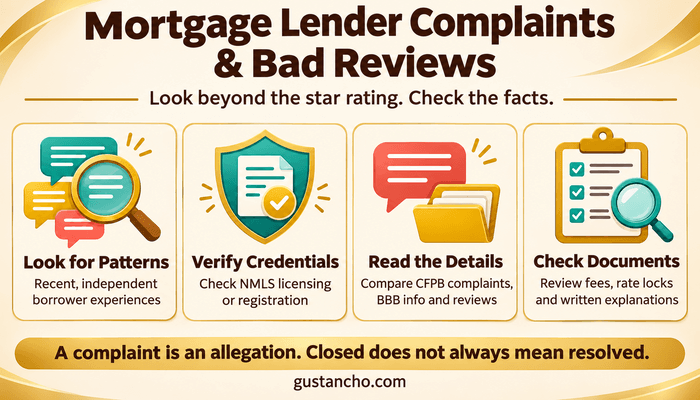
Quick Answer: Lender complaints and bad reviews can be red flags, but neither the star rating nor the number of complaints will, in itself, tell you whether a company is good. You need to look at independent, recent accounts of similar problems. You need to check the company and the loan officer; differentiate between loan origination and servicing issues; and review the written explanations and disclosures. A negative review is an allegation. A closed complaint doesn’t mean the borrower was happy. You need to look into the serious issues before you put any money down or go any further. Publisher disclosure: Gustan Cho Associates is a mortgage broker. This is an educational guide to researching complaints. It is not in any way an independent ranking of mortgage companies.
What One Bad Review Can and Cannot Tell You
A review shares one person’s experience. It might point out a problem to look into, but it doesn’t tell the whole story or prove that anything illegal happened.
Focus on what the complaint is really about. Ask what happened, when it happened, and who was involved. A review that explains issues like an unexpected charge, a missed deadline, or unanswered messages is more helpful than just a star rating with no details.
Think about how serious the complaint is and whether there’s a pattern. A vague complaint might not tell you much. But even one clear claim about things like false documents or missing money should be taken seriously, even if it’s the only one.
Look for Independent Experiences, Not Repeated Posts
Sometimes, one person posts the same complaint on Google, BBB, and other sites. That’s still just one person’s story, not three separate experiences. Check the dates, wording, and details before you decide that several posts show a pattern. Recent reviews usually show what’s happening now with staff, systems, and business relationships. Still, older serious complaints can matter too, especially if it’s not clear what has changed since then.
Verify the Mortgage Company and Loan Officer
Use the NMLS Consumer Access tool to check the company and the individual handling your application. Match up the records you find there with your disclosures, your email correspondence, and the company’s website. Check the legal company name (as well as any DBA or trade name), the individual loan officer’s name and NMLS ID, the current employer, and the relevant license or registration status. An NMLS number by itself does not establish current authority to originate your loan.
State Licensing and Federal Registration Are Different
Loan originators at state-licensed mortgage companies generally need the appropriate state license. Originators employed by banks, credit unions, and certain other depository institutions generally follow federal registration requirements instead. NMLS Consumer Access includes state-licensed mortgage professionals and federally registered originators. Review available regulatory or disciplinary information, but do not assume NMLS contains every historical action. The NMLS Consumer Access FAQs explain its records and their limitations. Contact the appropriate regulator if a status or company relationship is unclear.
How to Interpret CFPB Mortgage Complaints
The CFPB Consumer Complaint Database lets you examine complaints by company, product, issue, date, and other fields. Read the underlying issue and available response information rather than comparing company totals alone.
The CFPB cautions that its database is not a representative sample of customer experiences. Company size and market share also affect complaint volume. A larger company may receive more complaints because it serves more customers. In contrast, a small complaint count does not establish an absence of harm.
The database does not capture every complaint received by every regulator. Consequently, its totals should not be converted into a customer complaint rate without appropriate, comparable data.
A Closed Complaint May Remain Disputed
The CFPB’s description of published complaint data explains fields such as company response and whether the response was timely. Eligible complaints are made public after the company responds or after 15 days, whichever happens first. “Closed with explanation” means the company supplied an explanation under that response category. It does not, by itself, establish that the borrower agreed, received compensation, or considered the issue resolved. Likewise, a timely response does not establish that every disputed fact was addressed. Treat a complaint as a reported concern to investigate, not an automatic finding of wrongdoing.
Separate Origination Complaints From Servicing Problems
 Origination complaints concern the mortgage process: applications, preapproval, underwriting, rates, fees, appraisals, and closing. Servicing complaints concern managing the loan afterward, including payment processing, escrow accounts, late charges, and assistance when payments become difficult. The company collecting payments may differ from the company that arranged or funded the loan. Identify which business handled the stage involved in the complaint. In Figure 28 of its 2025 Consumer Response Annual Report, the CFPB reports that, among mortgage complaints closed with explanation or relief, 52% involved trouble during the payment process, 10% involved applying for a mortgage or refinancing, and 8% involved closing on a mortgage. Those figures describe a particular group of complaints, not the percentage of mortgage customers experiencing each problem. For a new application, look especially closely at complaints involving the company’s origination team.
Evaluate Google Reviews, BBB Information, and Possible Manipulation
Read both good and bad reviews. Pay attention to transaction details, clear explanations, and any updates after complaints. Make sure to distinguish reviews from borrowers from those from employees, recruiters, or business partners. See how the company responds to each review. Does the reply address the problem and explain what will happen next? Generic answers are less helpful. If the company’s public reply is brief, try reaching out privately if the issue could affect your own loan.
BBB Grades and Customer Reviews Measure Different Things
A BBB letter grade is separate from its customer-review score. According to BBB’s explanation of its ratings, customer reviews are not used in calculating the letter grade, and the grade does not guarantee reliability or performance. Read the complaint history, response, and outcome rather than relying only on an A+ grade or a low review score. Neither substitutes for checking licensing and transaction documents.
Unusual Review Patterns Are Reasons to Investigate
Repeated wording or sudden clusters of reviews might be worth a look, but that alone doesn’t prove the reviews are fake. You need to look across the various platforms and examine the details. The FTC’s Consumer Reviews and Testimonials Rule (effective October 21, 2024) covers a range of practices, including fake reviews, incentives contingent on positive or negative sentiment, undisclosed “insider” reviews, and certain forms of review suppression. It does not ban all incentive arrangements; disclosure obligations and platform rules may also be in play. For the borrower, the practical lesson is to look at the source and any declared relationships rather than assume that the positive reviews are genuine and the negative ones are all faked.
Evaluate Common Complaints Against the Available Evidence
Loan Denials After Preapproval
Preapproval depends on meeting all underwriting requirements and conditions. If your credit, income, assets, debts, or the property change, your loan could still be denied. A denial by itself does not mean anyone did anything wrong. But if you received inaccurate promises or unclear explanations, it’s important to look into them. Ask what changed, when the problem was found, and if it could have been noticed sooner. Check if the explanation matches what you were originally told and what’s in your documents. For more information about the responsibilities of the people handling your file, see “Working with a loan officer.“
Rate Changes and Unexpected Fees
Compare the complaint with the Loan Estimate, any revised disclosures, the written rate-lock confirmation, and the Closing Disclosure when available. Ask which charge changed, why it changed, and what documentation supports the explanation. For transactions covered by the TRID rule, a Loan Estimate generally must be delivered or mailed within three business days after submission of six application items: name, income, Social Security number to obtain credit, property address, estimated property value, and requested loan amount. The CFPB explains that verifying documents cannot be required first. If a rate changed, establish whether it was locked, whether the lock expired, and whether the loan information or terms changed. An advertised rate or an informal quote is not enough to resolve a rate-lock dispute.
Communication Problems and Closing Delays
A delayed closing may involve underwriting, appraisal, title, insurance, repairs, or missing information. Establish the cause and which party controlled the outstanding task. Repeated unanswered messages, conflicting instructions, and missed deadlines without explanation are useful warning signs to investigate. Ask who owns each remaining condition, when it was requested, and when the company expects a decision to be made. For broader advice on selecting a loan officer, see choosing a loan officer.
Warning Signs That Deserve Immediate Attention
Take any request to fake income, hide debt, misrepresent occupancy, sign false documents or make a payment via some unexplained payment arrangement very seriously. The same applies to any request that the company is not what it appears to be, or that the company is not properly licensed. Request the company, the person and the payment instructions to be clarified and independently verify them. Keep all relevant messages and documentation. For reported regulatory actions, read the action. Don’t just look at the outcome and assume that’s it. You need to be able to tell the difference between allegations, findings, settlements and current restrictions. Don’t treat every record as the same type of outcome.
Hypothetical Example: Three Reviews, Different Next Steps
These situations are examples and do not describe real borrowers or mortgage companies. One vague complaint: A borrower leaves a one-star review because the lender requested additional bank statements. Without more details, it’s hard to know if the request was reasonable. Ask your loan officer which documents are still needed and why. Several independent accounts: Some recent borrowers report unexplained origination charges and difficulty obtaining written answers. This gives you a stronger reason to review the company’s disclosures, ask for an explanation of the fee, and look up any related regulations. One account on several platforms: The same wording and transaction details show up on three different websites. Treat this as a single reported experience and look into its details. Just because it appears multiple times does not mean it is confirmed by others. Your next step should depend on the specific concern and the evidence you find, not just the number of stars or search results.
What to Do if You Have a Mortgage Complaint
Document the Problem and Request a Written Response
Create a short timeline with dates, names, disputed amounts, and the outcome you are requesting. Keep relevant Loan Estimates, Closing Disclosures, rate-lock confirmations, statements, emails, and messages. Contact the company through a verified channel and ask for its complaint department or an appropriate manager. State the issue clearly and request a written explanation. If a closing deadline is approaching, identify it prominently and ask who is responsible for the response.
Find the Appropriate Complaint Channel
You can submit a mortgage complaint to the CFPB. Its portal explains what information to include and how complaints are sent to companies or referred to another agency when that agency is better suited to assist. You can also locate the applicable state mortgage or banking regulator through NMLS state and federal agency contacts. The appropriate authority depends on the company and issue. Keep public reviews separate from document submissions. Do not post Social Security numbers, full account numbers, unredacted loan documents, or other sensitive financial information in a public review.
Frequently Asked Questions
How Do I Research Complaints When the Company Uses a DBA?
Start with the legal company name and NMLS number on your disclosures, then look for any DBA or trade name in public records. Search both of those. Make sure that you’re not confusing a similarly named company or a former employer with the business that’s actually processing your loan.
Does Finding No CFPB Complaints Mean a Company Is Safe?
No, the database has coverage issues, and not every unhappy customer will make a complaint. Keep checking the licensing/registration, the available regulatory information, other people’s experiences as a borrower, and the actual written terms of your transaction.
Are Anonymous or Redacted Complaints Automatically Less Credible?
No. Evaluate the specific facts and available supporting information. The CFPB removes information that directly identifies consumers from its public database. A missing public name does not, by itself, establish that an account is false.
Should I Check a Mortgage Broker Differently From a Lender?
Verify both the broker and the lender involved, then determine which party handled the disputed activity. A broker generally arranges financing with third-party lenders. For more about these roles, see types of mortgage lenders and mortgage brokers.
Can a Company Remove a Negative Review Simply Because It Disagrees?
A company can dispute a review or report it in accordance with the platform’s policies. Disagreement alone does not establish that the review is false or violates those policies. Keep your review factual, describe your own experience, and retain supporting records.
Should I Switch Lenders After Discovering Bad Reviews?
First, determine whether the reviews describe problems relevant to your own transaction. Request answers about any matching concerns, then consider the effect of switching on your closing date, costs, appraisal, and rate lock. Read about changing lenders during underwriting before making that decision.
Final Thoughts
Mortgage lender complaints and negative reviews are most helpful when you link specific concerns to solid records and clear explanations. Personal experiences, the seriousness of the issue, and how the company responds give you more insight than a rating alone. Make sure you know who is involved, check the documents, and get clear answers before moving forward. If the issue affects your loan, keep any evidence and file a complaint properly.
This article about “Mortgage Lender Complaints and Bad Reviews: What Borrowers Should Check” was updated on November 5th, 2026.