
Quick Answer: Are subprime loans still available? Subprime loans are mortgage loans designed for borrowers with higher credit risk or who do not meet traditional prime mortgage qualification standards. Although the mortgage industry changed significantly following the 2008 housing crisis, borrowers with poor credit, recent bankruptcies, foreclosures, or other financial challenges may still have alternative mortgage options.
Today’s non-QM mortgage market also serves borrowers who cannot qualify through traditional income documentation, including self-employed business owners, real estate investors, and retirees with substantial assets.
However, subprime loans and non-QM mortgages are not interchangeable. Subprime-style financing generally addresses higher credit risk, while non-QM loans can accommodate alternative methods of documenting income, assets, or repayment ability. Interest rates, down payments, reserves, and eligibility requirements vary by loan program and lender.
What Are Subprime Mortgage Loans?
Subprime mortgages are home loans intended for borrowers who present a higher credit or repayment risk than borrowers who qualify for traditional prime mortgage financing. These borrowers may have lower credit scores, recent late payments, high debt-to-income ratios, limited credit histories, or major derogatory credit events. A borrower who recently experienced a bankruptcy, foreclosure, deed in lieu of foreclosure, or short sale may have difficulty qualifying for a conventional or government-backed mortgage due to applicable waiting periods and other underwriting requirements. Traditional mortgage programs do not necessarily reject every borrower with a history of credit problems. FHA, VA, USDA, and conventional loans each have their own credit and eligibility requirements. However, borrowers who cannot meet those requirements may need to explore alternative financing. Subprime-style mortgage programs evaluate risk differently from traditional prime mortgage programs. Depending on the lender, underwriting may place greater emphasis on the borrower’s credit history, available equity, down payment, cash reserves, property characteristics, and documented ability to repay. These loans generally cost more than comparable prime mortgage products because lenders and investors are accepting additional risk. Borrowers should carefully review the interest rate, fees, repayment terms, and total cost before choosing this type of financing.
Are Subprime Mortgages Still Available Today?
Yes, alternative mortgage financing is still available. However, the market is substantially different from the subprime lending environment that existed before the 2008 financial crisis. Before the housing crash, some mortgage lenders originated loans with limited income verification, risky adjustable-rate structures, and payment terms that borrowers could not realistically sustain.
When home values declined and adjustable payments increased, many homeowners could no longer afford their mortgages or refinance. The resulting defaults and foreclosures contributed to a broader financial crisis.
Today’s mortgage market operates under significantly different regulatory and underwriting requirements. The Ability-to-Repay rule requires lenders to assess, in good faith, whether a borrower can repay a residential mortgage. Non-QM financing does not mean that lenders can ignore repayment ability or approve loans without appropriate underwriting. The term subprime is also used less consistently in today’s mortgage industry. Borrowers seeking alternative financing may encounter terms such as non-prime, non-QM, portfolio lending, and alternative documentation mortgages. Although these products can serve borrowers who fall outside traditional mortgage guidelines, they are not all designed for the same type of borrower.
Subprime Loans vs. Non-QM Mortgages: What’s the Difference?
Subprime and non-QM mortgages are related because both can serve borrowers who do not fit traditional prime mortgage requirements. However, the terms describe different aspects of mortgage lending. A subprime or non-prime mortgage generally refers to financing for borrowers who present elevated credit or repayment risk. This includes borrowers with low credit scores, recent late payments, significant derogatory credit events, or other financial issues that hinder traditional mortgage approval. A non-QM mortgage is a loan that does not meet the applicable definition of a Qualified Mortgage. Non-QM loans may use alternative underwriting methods to evaluate income, assets, and repayment ability. A borrower does not necessarily have bad credit to qualify for a non-QM mortgage. For example, a self-employed business owner may have excellent credit, substantial bank deposits, and strong financial reserves but report relatively low taxable income because of legitimate business deductions. A traditional mortgage may not recognize the borrower’s actual cash flow as favorably as a bank statement program. Likewise, a real estate investor may qualify through a debt service coverage ratio (DSCR) program that evaluates the rental property’s income relative to its debt obligations. The important distinction is that non-QM does not automatically mean subprime. Some non-QM borrowers have excellent credit and substantial assets. Their challenge is often documentation rather than creditworthiness.
How Today’s Non-QM Mortgage Market Works
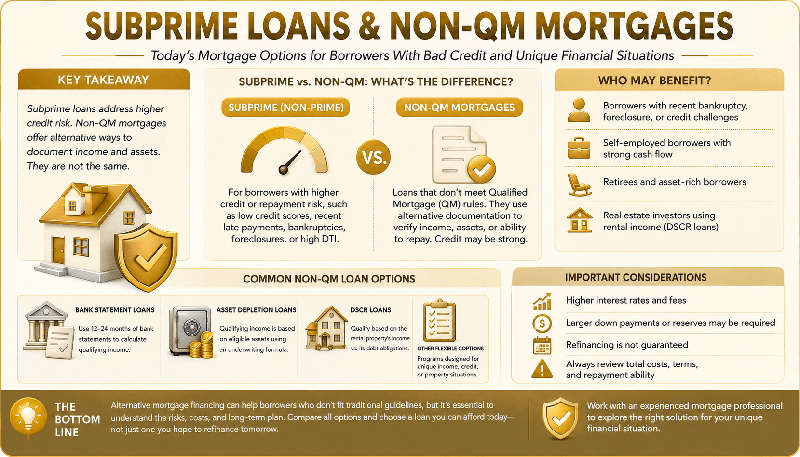
Non-QM mortgages provide lenders with additional flexibility in evaluating borrowers who cannot meet conventional Qualified Mortgage standards. The specific documentation and underwriting requirements depend on the product, investor, and lender.
Common non-QM programs include:
Bank statement mortgages: These may allow an eligible self-employed borrower to use their personal or business bank statements to document income, rather than relying solely on the traditional tax return calculation. The lender will review the deposits, business expenses, account ownership, and other documentation to determine the level of qualifying income.
Asset depletion mortgages: These consider eligible financial assets and may determine qualifying income using an underwriting formula. Can be of use to retirees and asset-rich borrowers who have substantial savings or investments but perhaps very little in the way of traditional employment income.
DSCR mortgages: DSCR mortgages (Debt Service Coverage Ratio) are a common type of loan used by RE investors. Instead of focusing on the borrower’s personal income, the lender will evaluate the property’s income to see if it can cover the mortgage payment and related expenses.
Other non-QM programs: It will depend on the lender, but could include interest-only mortgages, certain ARMs, and financing for people with unusual income or credit. Alternative documentation doesn’t eliminate underwriting. The lender still reviews the borrower’s financials and the property’s suitability under the relevant program.
Bad credit doesn’t automatically mean you cannot qualify for a mortgage
Explore how subprime loans work and discover mortgage financing options through Gustan Cho Associates.Who May Qualify for Subprime or Non-QM Financing?
Not every borrower who gets turned down for a conventional mortgage needs a subprime or non-QM loan. The reason for the denial matters because different mortgage programs address different qualification problems.
Borrowers With Recent Bankruptcy or Foreclosure
Borrowers who have experienced Chapter 7 or Chapter 13 bankruptcy, foreclosure, a deed in lieu of foreclosure, or a short sale may need to wait before obtaining a mortgage. These waiting periods differ between FHA, VA, USDA, and conventional financing. The applicable date also depends on the type of credit event and the circumstances surrounding it. Some alternative mortgage programs may consider borrowers who have not completed the waiting period for a traditional mortgage. However, eligibility is not automatic. Credit history since the event, income, assets, equity, down payment, reserves, and lender requirements can all affect the decision. Borrowers should compare the cost of alternative financing with the benefits of waiting until they qualify for a lower-cost mortgage.
Borrowers With Poor Credit or Recent Late Payments
Borrowers with lower credit scores, recent late payments on their mortgages, collections, charge-offs, or other derogatory credit may have difficulty meeting traditional mortgage requirements. The appropriate solution depends on the entire credit profile. A low credit score alone does not tell the whole story. Underwriters may also examine the severity and recency of late payments, outstanding debt, housing payment history, and the circumstances behind previous financial difficulties. Some borrowers may qualify for FHA, VA, or other traditional financing after addressing specific credit issues. Others may need additional time or an alternative program.
Self-Employed Borrowers With Strong Cash Flow
Self-employed borrowers sometimes report lower qualifying income on their tax returns due to legitimate business expenses and deductions. This does not necessarily mean the business is unprofitable or that the borrower cannot make mortgage payments. A bank statement mortgage may provide an alternative method of documenting qualifying income. Depending on the program, lenders may review 12 or 24 months of eligible deposits and apply an expense factor or other calculation to determine qualifying income. The lender must establish that the deposits represent eligible income and that the borrower can support the proposed mortgage payment.
Retirees and Asset-Rich Borrowers
Some retirees have substantial savings, retirement accounts, brokerage accounts, or other eligible assets but receive limited monthly employment income. An asset depletion mortgage may allow qualifying assets to be converted into an income figure using the lender’s applicable underwriting formula. Eligibility depends on the type of assets, ownership, liquidity, withdrawal restrictions, and the specific program’s calculation method.
Real Estate Investors
Real estate investors may have multiple rental properties, substantial equity, and strong cash flow but complicated personal income documentation. A DSCR mortgage may allow an investor to qualify based on the rental property’s income rather than relying exclusively on personal tax returns or employment income. These programs have their own requirements concerning property type, occupancy, rental income, reserves, credit, and loan-to-value ratio.
Subprime Mortgage Qualification Requirements
There is no universal set of qualification requirements for all subprime or non-QM mortgages. Each lender establishes its own eligibility standards based on the loan program and the risks associated with the transaction. Common underwriting considerations include:
- Credit score and overall credit history.
- Recent late payments, bankruptcies, foreclosures, and other derogatory events.
- Debt-to-income ratio or applicable alternative income calculation.
- Employment, self-employment, and income documentation.
- Down payment and loan-to-value ratio.
- Verified assets and required cash reserves.
- Property type, occupancy, and condition.
- Loan amount and transaction purpose.
- Ability to repay the proposed mortgage.
Some programs require larger down payments or substantial reserves. Others may offer different loan-to-value limits depending on the borrower’s credit profile and property characteristics. There is no universal requirement for a 10% or 20% down payment, and there is no single credit score that guarantees eligibility. Borrowers should also understand that some non-QM investment property loans may include prepayment penalties. Adjustable-rate mortgages may have future payment increases, and loan terms can differ significantly between investors. Reviewing the actual program guidelines and loan disclosures is essential before proceeding.
Interest Rates, Down Payments, and Costs of Subprime Loans
Subprime-style and non-QM mortgages often carry higher interest rates than comparable FHA, VA, USDA, or conventional loans. The additional cost generally reflects the lender’s assessment of credit risk, documentation complexity, loan-to-value ratio, occupancy, property type, and other factors. A borrower with recent credit problems may receive different pricing from a borrower with strong credit who needs alternative income documentation.
Down payment requirements also vary. A larger down payment may reduce the lender’s exposure and improve eligibility under certain programs, but borrowers should never assume that every non-QM loan requires the same amount of money down.
Before choosing a mortgage, compare more than the interest rate. Review the monthly principal and interest payment, property taxes, homeowners insurance, mortgage insurance if applicable, lender fees, discount points, closing costs, and any prepayment penalty. An apparently attractive monthly payment may not represent the lowest total borrowing cost.
Risks of Subprime and Non-QM Mortgages
Alternative mortgage financing can solve a specific qualification problem, but borrowers should understand the financial risks before signing a mortgage agreement.
Higher borrowing costs: A higher interest rate can substantially increase the total interest paid over the life of a mortgage. Origination fees, discount points, and other charges may also increase the cost of financing.
Refinancing uncertainty: Some borrowers intend to refinance into FHA, VA, or conventional financing after improving their credit or income documentation. Refinancing is never guaranteed. Future approval depends on the borrower’s financial profile, home equity, market conditions, interest rates, and applicable guidelines.
Adjustable-rate payment changes: Some alternative mortgage products have adjustable interest rates. Borrowers should understand the initial fixed period, the adjustment schedule, the rate caps, and the maximum potential payment.
Prepayment penalties: Certain non-QM investment property loans may include prepayment penalties. Review the loan documents and applicable state and federal requirements before accepting those terms.
Equity and foreclosure risk: Any mortgage creates a financial obligation secured by the property. If a borrower cannot make the required payments, the consequences can include late fees, credit damage, default, and ultimately foreclosure. The best mortgage is not necessarily the one that provides the fastest approval. It is the one whose payments and terms are sustainable for the borrower.
Can You Use a Non-QM Mortgage as a Bridge to Conventional Financing?
Some borrowers use alternative mortgage financing as a temporary bridge while rebuilding credit, completing mortgage waiting periods, or improving income documentation. For example, a borrower who recently experienced a bankruptcy may consider an alternative mortgage if waiting for traditional financing is not practical and the available program offers affordable terms.
A self-employed business owner may use a bank statement mortgage while continuing to build a stronger documented income history. A real estate investor may use DSCR financing while expanding a rental portfolio.
The future refinancing strategy should be considered before closing. Borrowers should understand what must change to qualify for a lower-cost mortgage. This could involve improving credit, establishing a longer record of on-time payments, reducing outstanding debt, documenting additional income, or building equity. However, there is no guarantee that refinancing will be possible after 12 or 24 months. Interest rates, property values, underwriting requirements, and the borrower’s financial circumstances can change. A bridge strategy should be considered only when the existing loan is affordable without relying on a future refinance.
How Gustan Cho Associates Reviews Alternative Mortgage Options
Gustan Cho Associates reviews mortgage scenarios involving borrowers who may not fit traditional lending guidelines. The objective is to identify the reason a borrower cannot qualify through conventional or government-backed financing and determine whether another mortgage program may be appropriate. The review begins with the borrower’s credit profile, income documentation, employment or business history, assets, liabilities, property details, and transaction goals. When appropriate, traditional FHA, VA, USDA, or conventional financing should be considered before moving to a higher-cost alternative. If those options are not available, non-QM or other specialized mortgage programs may be evaluated. For example, a borrower with a recent bankruptcy may need a different solution from a self-employed business owner whose tax returns do not reflect eligible cash flow. A real estate investor using rental income may need a DSCR program rather than a personal-income-based mortgage. The purpose of reviewing multiple options is to identify a mortgage structure that fits the borrower’s actual financial circumstances, not to recommend a more expensive loan simply because it is available.
Frequently Asked Questions About Subprime Loans
Are Subprime Loans Still Available in 2026?
Yes. Alternative mortgage financing remains available to certain borrowers who cannot meet traditional prime mortgage requirements. However, today’s market includes different non-prime and non-QM products, and eligibility depends on the specific lender and loan program.
What Credit Score is Considered Subprime for a Mortgage?
There is no single credit score threshold that applies to all subprime mortgages. The term is commonly associated with borrowers whose credit scores fall below traditional prime lending thresholds, but lenders set their own credit requirements. A mortgage credit score alone does not determine eligibility.
Is a Non-QM Loan a Subprime Mortgage?
No. Non-QM and subprime are not interchangeable terms. Non-QM describes a mortgage that does not meet the applicable Qualified Mortgage definition. Subprime generally refers to borrowers with elevated credit or repayment risk. A borrower with excellent credit may qualify for non-QM financing because of alternative income documentation.
Can I Get a Mortgage After Bankruptcy?
It’s possible. FHA, VA, USDA, and conventional loans each have their own waiting periods and rules after bankruptcy. Some alternative programs might consider you sooner, but lenders will still look at your credit, income, equity, down payment, and other requirements.
Can Self-Employed Borrowers Get Non-QM Mortgages?
Yes. Certain non-QM programs permit self-employed individuals to utilize bank statements to confirm their income rather than relying solely on tax returns. Lenders will look at your deposits, business expenses, and other financial records to figure out your qualifying income.
Can I Refinance a Subprime Mortgage Later?
Yes, you may be able to refinance if you qualify for a new mortgage program. Better credit, enough equity, steady income, and good market conditions can help. Still, refinancing isn’t guaranteed, so it’s important to pick a mortgage you can afford even if refinancing takes longer than you hope.
Final Thoughts on Subprime Loans and Non-QM Mortgages
Subprime loans and non-QM mortgages offer alternative financing options for borrowers who cannot qualify for traditional mortgage programs. However, borrowers should understand the difference between credit-related lending challenges and alternative income documentation.
A borrower recovering from bankruptcy may need a different mortgage solution from a business owner with strong cash flow or a real estate investor qualifying through rental income. Identifying the actual qualification issue is the first step toward finding an appropriate loan program.
Before accepting a higher-cost mortgage, compare available FHA, VA, USDA, conventional, and non-QM options. Review the full payment, interest rate, closing costs, down payment, reserves, and any prepayment provisions. If the mortgage is intended as a temporary bridge, establish a realistic refinancing strategy without assuming future approval. The right financing decision should account for both the borrower’s current circumstances and the long-term financial responsibility of owning the home.
This article about “Subprime Loans: Today’s Non-QM Mortgage Options for Borrowers With Bad Credit” was updated on November 10th, 2026.