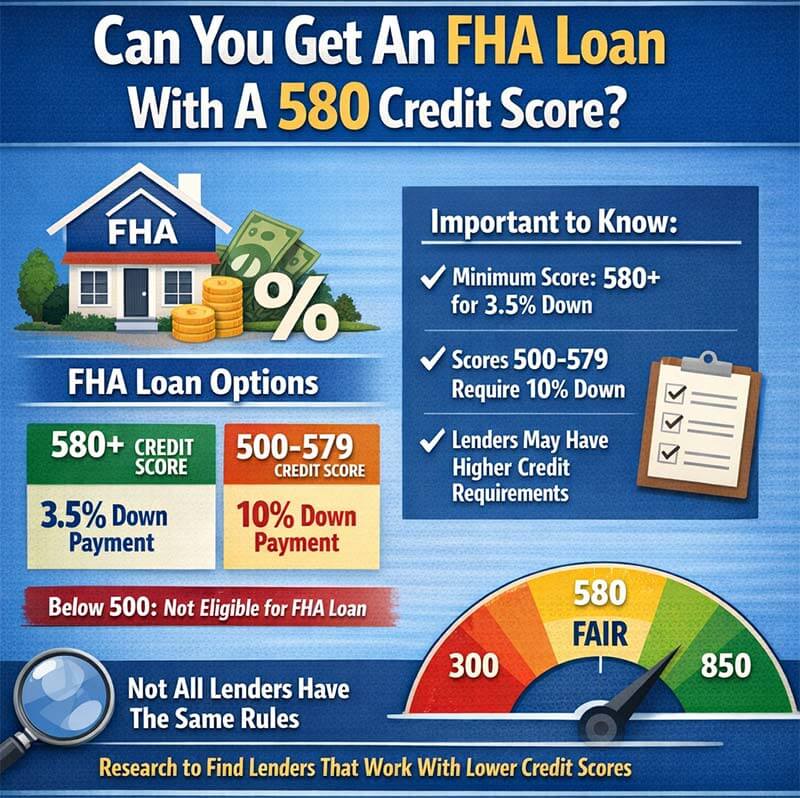
Quick answer: An FHA loan with low credit score may be available if your score is 500 or above. For a standard purchase, a score of 500-579 generally requires at least 10% down payment; a score of 580 or above allows a 3.5% down payment. Those are the FHA eligibility thresholds; lenders can require higher scores. Approval will also depend on income, debt, payment history, available funds, the property, and underwriting.
FHA Credit Score and Down Payment Requirements
Your qualifying mortgage credit score helps determine how much FHA financing may be available to you. The main dividing line for a standard FHA home purchase is 580.
| Qualifying credit score | Maximum base loan-to-value ratio | Minimum down payment |
|---|---|---|
| 580 or higher | Up to 96.5% | As little as 3.5% |
| 500–579 | Up to 90% | Generally at least 10% |
| Below 500 | Not eligible under FHA’s minimum score requirement | A larger down payment does not remove the score requirement |
These score thresholds determine eligibility for financing; they do not guarantee approval. The percentages show FHA’FHA’sified value. This value is usually the lower amount between the purchase price and the appraised value. Special transaction restrictions can require more money down. The base loan figures exclude any financed upfront mortgage insurance premium. A 550 credit scoFHA’slls within FHA’s eligible score range, but it comes with a lower financing limit. Having the required down payment is one part of qualifying; the remaining application must also meet FHA and lender requirements.
What 10% Down Versus 3.5% Down Means in Dollars
Consider a $250,000 home purchase with an appraisal at or above the purchase price and no special financing restrictions.
| Example qualifying score | Minimum down payment percentage | Down payment amount |
|---|---|---|
| 550 | 10% | $25,000 |
| 585 | 3.5% | $8,750 |
The difference is $16,250. That illustrates why the qualifying score can substantially change the cash needed for the same home. These amounts only include the down payment. You’ll need to review closing costs, prepaid expenses, escrow deposits, and any required reserves separately. If the appraisal comes in lower than the purchase price, you may need to bring more cash to closing. If you’re deciding whether to buy now or wait, ask for two full estimates: one using your current qualifying score, and another showing what might happen if you qualify for different financing later. Keep in mind that future scores, rates, or approvals aren’t guaranteed.
Why a Lender May Require More Than FHA’s Minimum Score
FHA sets the eligibility criteria for the mortgages it insures. Individual lenders are free to impose additional requirements (so-called ‘lender overlays’). For instance, a lender might require a 620 even though the FHA will only lend on a max score of 580. One lender may be prepared to consider lower scores but may have different requirements regarding debt service ratios, reserves, and/or manual underwriting. A denial therefore needs a specific explanation. Ask whether the obstacle is:
- An FHA eligibility requirement.
- The lender’s minimum credit score or some other overlay.
- An underwriting result or a problem with income, debts, credit history, or funds.
This helps you to determine what you need to do next. A different lender’s policy may address the overlay, whereas an FHA eligibility issue will still need to be resolved. A different application is not a substitute for resolving the original issue.
How Low Scores Affect Automated and Manual Underwriting
An automated underwriting system evaluates information about the application using FHA’s TOTAL Mortgage Scorecard. Its findings help determine the required underwriting review. An automated result does not replace the lender’s responsibility to verify the file and satisfy FHA requirements. Some applications require manual underwriting, including files that receive a referral or must be downgraded under FHA rules. Manual underwriting involves a documented assessment by an underwriter and has its own standards. It does not bypass a minimum score requirement.
Credit Scores Matter to Manual Underwriting Debt Limits
For manually underwritten loans with scores of 500–579, FHA generally limits the housing payment to 31% of qualifying income and total monthly debt payments to 43%. Specific energy-efficient-home provisions can allow different ratios. At 580 or higher, certain higher manual underwriting ratios may be available when the required compensating factors are documented. Extra savings alone do not make every higher ratio acceptable. The housing payment includes applicable taxes, insurance, and mortgage insurance. Total debt includes that housing payment plus other qualifying monthly obligations. Ask your loan officer to calculate both ratios using verified qualifying income.
What Must Support an Application With a Low Credit Score
Two borrowers with the same score can receive different decisions because their finances differ. A useful review connects the credit score to these parts of the application:
| Application factor | What to review with your loan officer |
|---|---|
| Qualifying income | How much documented income can be used and whether it supports the proposed payment. |
| Monthly obligations | Which debts count and how much room remains for housing costs. |
| Payment history | Whether recent credit and housing payments meet the applicable underwriting standards. |
| Available funds | Whether acceptable, documented funds cover the down payment, closing costs, and any required reserves. |
A score summarizes credit information, but it does not establish that every item on the credit report is acceptable. A higher score also does not erase a separate eligibility problem. If bankruptcy is part of your history, review the chapter, case status, and applicable eligibility timing in our guide to FHA mortgage after bankruptcy. For missed payments following a bankruptcy, use our separate guide to FHA guidelines on late payments after bankruptcy.
How a Low Credit Score Can Affect Loan Costs
Credit scores can affect both mortgage pricing and eligibility. The rate and fees available to you also depend on the lender, loan details, and market conditions. There is no single FHA interest rate that applies to all borrowers with low scores.
Compare written Loan Estimates for the same loan type, term, down payment, and approach to points or lender credits. Check whether the rates are locked and whether the estimates were prepared at similar times.
Review the total monthly payment, mortgage insurance, upfront loan costs, and cash-to-close. A lower advertised rate may require more points to be paid upfront. Consider how those costs fit your budget and how long you expect to keep the loan.
Get a Review Based on Your Current Score
Before you make an offer, have your loan officer confirm the qualifying mortgage score, the required down payment, the estimated amount of cash you’ll need, and the underwriting route that will be available. Provide your income and asset docs so the review isn’t just a score conversation. You should leave that discussion with a clear understanding of the payment range your finances can support, as well as any issues that need to be ironed out before moving forward. If you’ve already been turned down, you should bring the reason for the rejection so the next review can focus on the actual problem. If the review shows that credit preparation is the next step, follow our guide to re-establishing credit so you can qualify for an FHA loan. Discuss account changes with your loan officer before using funds that may be needed for closing.
Frequently Asked Questions About FHA Loan With Low Credit Scores
Why Is My Mortgage Credit Score Different From the Score in My App?
Credit scores can differ due to the scoring model, credit bureau data, and the date of calculation. A consumer app may show a score different from the one used for an FHA mortgage. Ask which score is being used to evaluate your application before estimating your down payment from an app’s number.
Can a Co-Borrower With Better Credit Replace My Low Score?
Adding a co-borrower does not simply let you substitute that person’s higher score for your own. FHA has rules for determining the qualifying score when multiple borrowers apply. Eligible co-borrower income may help the application, but debts and other requirements also apply. Have the proposed borrower combination reviewed before relying on it.
Is Having No Credit Score the Same as Having a Score Below 500?
No. A borrower without a usable credit score may be evaluated under FHA’s nontraditional or insufficient-credit provisions, subject to documentation and underwriting requirements. A reported qualifying score below 500 fails FHA’s minimum score requirement. A no-score file cannot be assumed eligible simply because FHA permits some nontraditional credit reviews.
Can Gift Funds Help With a 10% Down Payment?
Eligible gift funds may help meet the down payment requirement when the donor, source, and transfer satisfy FHA and lender requirements. The gift must not require repayment. Have the funds reviewed before they move so the required documentation is available; an informal promise of help does not establish acceptable closing funds.
Can a Credit Score Change Before Closing Affect My Loan?
Yes. A change in credit information or qualifying score can affect eligibility, financing, pricing, or the underwriting review. Report new accounts, new debt, and other financial changes to your loan officer promptly. A preapproval should not be treated as a guarantee that later changes will have no effect.
Final Thoughts on Qualifying for an FHA Loan With Low Credit Score
The main things to consider are your qualifying mortgage score, the financing available for that score, and whether your full application supports the payment you want. Knowing these details helps you set a realistic budget and decide whether to apply now or wait and prepare more.
Discuss Your FHA Loan Options
Reach out to Gustan Cho Associates for a review of your credit score, down payment, income, and FHA loan options. You can call 800-900-8569 or email gcho@gustancho.com to talk about your situation.
This article about “FHA Loan With Low Credit Scores: 500–579 vs. 580 and Above” was updated on November 3rd, 2026.