
There’s no one waiting period after mortgage forbearance that applies to all new loans. It all depends on whether your forbearance has actually ended, how the missed payments were handled, what payments you’ve made since then, and whether you’re buying or refinancing. A payment deferral is very different from a loan modification, and an FHA cash-out refinance has more stringent payment history requirements than some other transactions.
Before you start counting months, you need to get your servicer’s written statement as to when the plan ended and what happened to the missed payments.
When Does the Waiting Period After Mortgage Forbearance Start?
Start with the date your mortgage servicer says the forbearance plan was completed or terminated. Then identify the first payment due under your regular mortgage terms or the arrangement that followed forbearance. The date of your last skipped payment may not be the date an underwriter uses.
For example, your servicer might end forbearance and put the skipped payments into a payment deferral. You would resume your regular monthly payments, and the deferred amount would be due later, per the deferral agreement. An underwriter needs to review the agreement and your payment history to verify when you resumed payments and whether you made each payment on time.
A mortgage statement with your current balance is useful, but it does not show your full payment history. Hold on to your forbearance agreement, the notice that forbearance ended, and any paperwork that explains how you handled the missed payments.
How You Left Forbearance Affects the Answer
If you kept making every payment required by your original mortgage note, your payment history may be treated differently from that of someone who paused payments. If you paid all skipped amounts and fully reinstated the loan, there may be no ongoing repayment arrangement to review. Neither situation guarantees approval for a new mortgage.
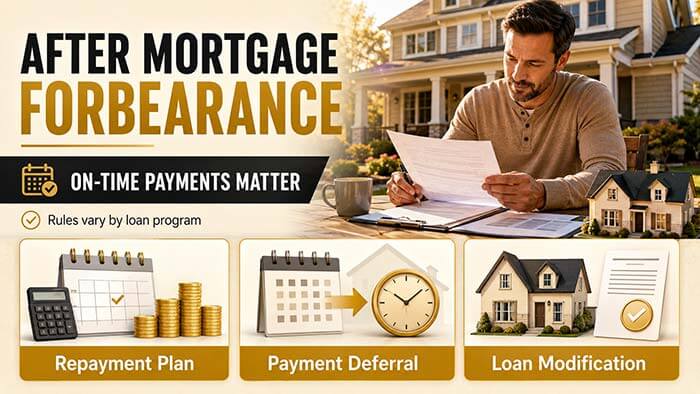
If you entered a repayment plan, the underwriter will check whether you are making both the regular payment and the agreed catch-up amount. With a payment deferral, the underwriter will check when regular payments resumed and how the deferred balance will be handled if the property is sold or refinanced.
A loan modification changes the mortgage terms. It needs its own review, including the effective date and payments made under the modified terms. Do not assume that a payment deferral and a modification have the same requirements.
Why Three Payments Is Not a Universal Rule
You may have heard that you can get a new mortgage after making three payments following forbearance. That was a prominent rule in COVID-era conventional loan guidance, but it is not a dependable answer for every loan application today.
For FHA purchases and no-cash-out refinances, fewer than three consecutive monthly housing payments after completing forbearance can require a downgrade to manual underwriting. A downgrade means an underwriter must review the file under manual guidelines; it is not, by itself, a three-month ban or an automatic denial.
Other programs and transaction types must be checked under their applicable guidelines. The mortgage you already have and the new mortgage you want may also be different types of loans. Ask for a review of the new loan program and your documented payment history before relying on a number of months.
FHA Cash-Out Refinances Have a Longer Payment Requirement
If you want an FHA cash-out refinance on the property that was in forbearance, FHA requires the forbearance plan to be completed and at least 12 consecutive mortgage payments to have been made within the month due after it ended. This is a specific cash-out requirement. It should not be applied automatically to an FHA home purchase or every other refinance.
A borrower seeking cash out should check the payment dates before ordering an appraisal or setting an expected closing date. Recent mortgage delinquencies and other cash-out requirements must also be reviewed.
What Can Delay Approval After Forbearance?
The number of months since forbearance ended is only part of the review. A loan may still show an active plan, an outstanding balance, or late payments outside the agreed-upon forbearance terms. A repayment plan may require a higher monthly payment than the original mortgage. If you keep that home, it may impact your borrowing qualifications for another property.
Documents can cause delays, too. The credit report, mortgage statement, and servicer’s records may describe the account differently. Obtain a written payment history and an explanation from the servicer if those records do not agree.
What to Gather Before You Apply
Ask your servicer for the forbearance agreement, its completion or termination date, and a payment history covering the months before, during, and after the plan. If the skipped payments went into a repayment plan, deferral, partial claim, or modification, obtain that agreement as well. A current statement helps show what you owe today.
Give those records to your loan officer along with the type of transaction you want: a purchase, a refinance without cash out, or a cash-out refinance. That gives Gustan Cho Associates enough information to identify the applicable rule and tell you which payment dates still matter.
FAQs About the Waiting Period After Mortgage Forbearance
Can I Apply Before the Required Payments are Complete?
- You can discuss your options and have your records reviewed early. Whether a loan can be approved or closed before a particular payment is made depends on the program and transaction. Do not set a closing date from a general three-month estimate.
Does the Clock Start When I Make a Lump-Sum Payment?
- A lump-sum payment can reinstate a mortgage, but it does not replace the need to confirm when forbearance ended and whether the loan is current. The new loan’s rules determine whether any further payment history is required.
Do Payments Made During Forbearance Count?
- That depends on the terms of the plan and the rule being applied. Provide the written agreement and proof of what you paid. The underwriter should distinguish payments made as agreed during forbearance from payments required after its completion.
What if My Servicer Marks the Loan as Current, but My Credit Report Shows Late Payments?
- Request a detailed payment history and ask the servicer to explain the difference in writing. An underwriter needs to know which payments were covered by the agreement and whether any late payments occurred outside it.
Is a Payment Deferral the Same as a Loan Modification?
- No. A deferral generally sets aside missed payments for a later payoff while regular payments resume. A modification changes the loan’s terms. Provide the actual agreement so the new mortgage can be reviewed under the right rules.
Does Forbearance Create the Same Waiting Period as Foreclosure?
- No. Forbearance and foreclosure are different events. If the mortgage ultimately went through foreclosure, the rules for that event must be reviewed separately.
Final Thoughts on the Waiting Period After Mortgage Forbearance
The useful question is not simply, “Has it been three months?” It is, “When did my forbearance end, how were the missed payments handled, and what does my new loan require?” Get those answers from the servicer’s records before assuming you must wait—or that you can close immediately. Gustan Cho Associates can review the documents and help establish a realistic application and closing timeline.
This article about “Waiting Period After Mortgage Forbearance: When Can You Qualify?” was updated on November 17th, 2026.
Need a Simple Yes or No on Your Waiting Period After CARES Act Forbearance?
Skip the guessing and get a clear answer from experts who do this every day