FHA loans with child support payments are possible whether you receive child support or pay it.
If you receive child support, FHA may allow the income to be used for qualification when it is properly documented, received consistently, and expected to continue long enough under HUD guidelines.
If you pay child support, the required monthly payment is generally counted as a recurring debt when calculating your debt-to-income ratio. The lender will review the court order, payment amount, and any wage garnishment or past-due support that may affect the loan. The key is whether the child support is being counted as income or as a monthly obligation.
How FHA Treats Child Support You Receive
If you want to use child support as qualifying income, your lender must verify the payment agreement and the support you actually receive. The documentation and payment history requirements differ between court-ordered and voluntary support.
Do You Have to Use Child Support Income to Qualify?
You do not have to disclose child support income if you do not want the lender to consider it when qualifying you. If your employment income or other qualifying income is sufficient, you may choose to apply without relying on child support. Regulation B protects this choice. This choice applies to the support you receive. You must still disclose child support payments you are required to make so the lender can account for that monthly obligation.
Court-Ordered Child Support
Provide a fully executed divorce decree, legal separation agreement, or court order establishing the support payments. The lender also needs proof of receipt for the most recent 3 months, such as bank deposits, canceled checks, or child support agency records. When payments have been consistent during those three months, the lender may use the current payment amount, provided the income meets FHA’s remaining requirements.
Voluntary Child Support: Twelve Months of Records and Six Months of Consistency
Support paid under a voluntary agreement may also qualify. The lender must document the agreement and obtain twelve months of payment evidence, such as canceled checks or deposit slips. The six-month rule addresses how the lender calculates qualifying income. When voluntary payments have been consistent during the most recent six months, the lender may use the current payment amount. Six months of consistent payments do not, by themselves, satisfy the twelve-month documentation requirement. The lender needs the longer payment record, even if the most recent 6 months show a steady amount. For example, a borrower with twelve months of documented voluntary support and consistent $800 monthly payments during the most recent six months may have that current amount taken into account. A borrower with only six months of payment records has not met the twelve-month documentation requirement.
How FHA Calculates Child Support Income When Payments Are Inconsistent
The lender cannot automatically use the amount shown in a court order when the borrower has not consistently been receiving that amount. For court-ordered support, if payments have not been consistent during the most recent three months, FHA requires the lender to average the income actually received over the previous two years. For voluntary support, the same averaging requirement applies when payments have not been consistent during the most recent six months.
What if the Borrower Has Received Child Support for Less Than Two Years?
The borrower does not automatically need a full two-year receipt history. If child support has been received for less than two years, FHA allows the lender to average the payments over the actual period of receipt. For FHA loans with child support payments, this distinction can matter when the amount ordered differs from the amount actually received.
How Long Must Child Support Income Continue?
FHA requires documentation showing that the child support used as qualifying income will continue for at least three years. The lender reviews the agreement’s payment amounts, scheduled reductions, and termination conditions.
When Support Covers More Than One Child
Lenders need to determine how much support will still be paid once each child’s payments stop. Just because one child is younger does not mean the full current payment counts as eligible income. For example, if an order requires 1,200eachmonth—500 for one child whose support ends in a year and $700 for another whose support continues for five years—the lender can count the $700 portion if it meets other income rules. If the order shows only a single combined payment and does not explain any future reductions, the lender should seek clarification on how much will continue. Do not assume the payment can be split evenly between the children.
Can FHA Gross Up Child Support Income?
Yes. Qualifying child support is nontaxable income and may be subject to a gross-up adjustment. This increases the income used in the mortgage calculation; it does not increase the payments you receive. FHA limits the adjustment to the greater of:
- 15%, or
- The appropriate tax rate for that income amount, based on your prior-year tax rate.
If you were not required to file a federal tax return for the previous tax reporting period, the lender may use a 15% adjustment. The lender must document the income being grossed up and support the tax rate used.
FHA Child Support Gross-Up Example
Assume the lender has verified that your $1,000 monthly child support qualifies and applies a 15% gross-up:
- Child support received: $1,000
- Gross-up adjustment: $150
- Income used for qualification: $1,150
Why Might the Lender Request Tax Returns?
A tax return may help the lender establish the tax rate used for the gross-up or verify other income. Child support received is not taxable income and should not be reported as such, even if only to document it for a mortgage. Keep records of the actual support payments, such as bank deposits, canceled checks, or agency payment histories. A tax return generally will not show those receipts.
How FHA Treats Child Support You Pay
FHA treats the child support you pay as a recurring monthly debt. HUD’s definition includes court-ordered or otherwise agreed-upon payments, and the lender must verify the arrangement. Provide the signed divorce decree, separation agreement, maintenance agreement, or other legal order documenting the obligation. The lender also reviews pay stubs covering at least 28 consecutive days to check for garnishment related to support.
Documented Payment vs. Wage Garnishment
The lender uses the greater of:
- The amount shown in the most recent decree or agreement establishing your payment obligation.
- The monthly amount is being garnished from the borrower’s wages.
If the agreement requires $600 per month but the monthly garnishment is $700, the lender uses the $700 amount.
How the Payment Enters Your DTI Calculation
The lender uses your gross qualifying income before child support withholding and includes the support payment in your monthly debts. For example, if you earn $6,000 monthly before deductions and $700 is withheld for child support, the calculation uses $6,000 in income and a $700 support obligation. The lender should not also subtract that $700 from income, which would count the same obligation twice.
How Child Support Affects Your FHA Debt-to-Income Ratio
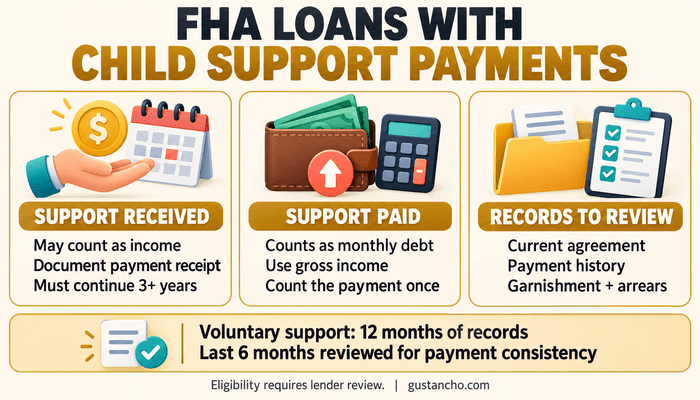 Monthly child support that the borrower is required to pay is included with the borrower’s other recurring debts when calculating the debt-to-income ratio. For example, if a borrower has:
- $500 monthly car payment
- $300 minimum credit card payments
- $800 monthly child support
The lender generally counts all three obligations when determining total monthly debt. For FHA loans with child support payments, a large support obligation can reduce the mortgage amount for which the borrower qualifies, even when credit and income are otherwise strong.
FHA Does Not Have One DTI Maximum for Every Borrower
Borrowers should not assume that FHA automatically allows a specific debt ratio, such as 56.9%. Loans receiving an automated underwriting approval are evaluated based on the complete credit profile. Manually underwritten FHA loans follow separate ratios and compensating-factor requirements. The child support payment is simply one of the recurring obligations included in that calculation.
What Happens When a Child Support Obligation Ends?
The three-year rule applies to support that is received as qualifying income; it does not permit a lender to ignore the support you owe merely because the payments are set to end within three years. The fact that a child has a birthday does not mean that your obligation has ceased. The lender should review the controlling agreement or court order, any subsequent amendments, and the documentation confirming the current required payment.
Check for Remaining Arrears
Ending current support does not always clear any past-due amounts. Depending on your order and state law, you may still need to make arrears payments or continue wage withholding. Send a recent statement from your child-support agency that shows any unpaid balance and what you still need to pay. Include any documents about ending support or wage withholding. This helps the lender figure out what counts toward your debt-to-income ratio.
Child Support Ending Soon? It May Affect Qualification Differently
The remaining term of the obligation can matter in mortgage underwriting. We’ll review the court order, payment schedule, and loan program requirements.FHA Loans With Past-Due Child Support
If you owe past-due child support, have your lender review the delinquency and federal administrative offset status before relying on a mortgage approval. Obtain current records from the child-support enforcement agency showing the outstanding balance, required payments, and any garnishment or offset information. Provide any repayment agreement or payoff documentation for the lender’s review.
When Federal Administrative Offset Prevents FHA Financing
Federal law prohibits FHA-insured financing for borrowers subject to federal administrative offset because of delinquent child support. This is an eligibility restriction, not simply another payment in the debt-to-income calculation. Making three repayment-plan payments does not automatically establish FHA eligibility. The lender must verify the current status rather than assume that a repayment agreement or payment receipt resolves the restriction.
Policy Note: May 18, 2026 Screening Proposal
On May 18, 2026, HUD proposed automated screening through FHA Connection using the Treasury Department’s Do Not Pay portal. HUD expressly identified the proposal as a draft policy that could not be used until finalized. That announcement described a proposed screening process for an existing restriction. It did not establish that the proposed screening or clearance procedures were already in force.
Can a Non-Occupying Co-Borrower Help You Qualify?
An eligible co-borrower who will not live in the home may contribute qualifying income. Their debts also enter the lender’s calculation, and your child support obligation still counts. FHA generally limits non-occupying borrower transactions to 75% loan-to-value (LTV). For eligible family-member transactions, the maximum may increase to 96.5% LTV, subject to these restrictions:
- The 96.5% family-member exception does not apply to two- to four-unit properties.
- It also excludes a sale by one family member to another family member who will be a non-occupying co-borrower.
Have the lender review the family relationship, property type, and transaction before relying on the additional income.
Child Support Documentation Problems and How to Fix Them
Deposits Cannot Be Clearly Identified
If an agency handles your support payments, ask for its payment history and compare the amounts and dates to your bank deposits. For direct payments, use canceled checks or transfer records that show who sent the money. If you cannot explain a deposit, it may not count as child support.
The Agreement and Actual Payments Do Not Match
Give the most recent signed modification along with the original agreement or order. If payments changed but there was no formal modification, explain why and include payment records. The lender must see the difference between a documented change and missed or partial payments.
Payments Are Irregular
Collect the full history of your receipts, including any missed months, partial payments, and lump-sum deposits. Do not send only the months with full payments. A full record helps the lender figure out the qualifying amount and see if more documents are needed.
Garnishment Exceeds the Stated Support Payment
Give the withholding order, recent pay stubs, and a breakdown from the agency that shows what the deduction covers. List current support, arrears payments, and other charges separately. This helps the lender match the garnishment to the documented obligation.
Example FHA Loan Scenario With Child Support
In this hypothetical scenario, a borrower has $6,000 in gross monthly qualifying income and these monthly obligations:
- Proposed FHA housing payment: $1,450
- Child support: $900
- Car payment: $450
- Minimum credit card payments: $200
The housing payment includes principal, interest, property taxes, homeowners’ insurance, FHA mortgage insurance, and any applicable association dues. Total monthly obligations are $3,000. The borrower’s total debt-to-income ratio is: $3,000 ÷ $6,000 × 100 = 50% DTI. The $900 child-support payment is included in monthly debts. It is also not subtracted from the $6,000 gross qualifying income. A 50% DTI does not establish loan approval. The lender must still evaluate the borrower’s verified income, credit, assets, and applicable automated or manual underwriting requirements.
Before You Make an Offer: Child Support Checklist
- Current agreement: Share a signed court order, divorce decree, or voluntary support agreement, along with any updates or changes.
- Payment records: Collect your bank statements, canceled checks, or payment histories from the agency for the time frame your lender needs.
- Garnishment documents: Provide the withholding order and recent pay stubs that show deductions and any payments made toward overdue support.
- Past-due support: Get current records from the agency that show your balance, repayment requirements, and any enforcement or federal offset details.
- Modifications or termination: Let your lender know about any ongoing changes and share the most recent signed documents confirming any approved reductions or end dates.
Before you decide on a purchase price, ask your lender to confirm your qualifying support income, monthly payment, and any outstanding eligibility questions.
FAQs About FHA Loans With Child Support Payments
Can I Qualify Without Using My Child Support Income?
Yes. If your other qualifying income is sufficient, you may choose not to disclose child support income or have the lender consider it. You must still disclose support payments you owe.
Does Child Support Count If It Is Missing From My Credit Report?
Yes. Required support payments must be disclosed and included in the lender’s evaluation even when they do not appear on your credit report. The lender verifies the obligation through the applicable documents.
Can I Pay Off Back Child Support Before Closing?
Potentially. Provide payoff evidence and updated child-support agency records. The lender must verify that the delinquency and any related federal administrative offset restriction have been resolved before determining eligibility.
Can an FHA Loan Close While a Support Modification Is Pending?
It depends on whether the lender can document the income or obligation. Provide the current order and disclose the pending change. The lender will determine whether a finalized modification is needed before closing.
This article about “FHA Loans With Child Support Payments: Income, DTI, and Documentation Rules” was updated on October 6th, 2026.