If you have faced bankruptcy, foreclosure, or a short sale, some loan programs may let you wait less time before applying for a mortgage if you qualify for an exception. To do this, you need to show that something outside your control caused your credit issues and that you have since managed your finances responsibly. The lender will still need to confirm that you meet the extenuating circumstances guidelines, any required waiting period, and all other mortgage qualifications.
What Qualifies as an Extenuating Circumstance?
Events a lender may evaluate include:
- Involuntary job loss or a substantial reduction in income.
- Serious illness or major uninsured medical expenses.
- Death of a household wage earner.
- A natural disaster that disrupts income or creates substantial expenses.
- Certain divorce-related financial hardships.
The lender applies the selected loan program’s definition to the facts of your situation. The program sections below explain where exceptions may be available.
Documents That Support an Extenuating-Circumstances Request
Ask your lender which records are relevant before gathering documents. Organize them by date so the underwriter can compare the hardship with the affected accounts.
Job Loss or Reduced Income
Useful records may include:
- A layoff notice or employer confirmation explaining when and why employment ended.
- Severance documents and unemployment-benefit records.
- Pay records or tax returns showing income before, during, and after the interruption.
- Bank statements showing the effect on available funds.
- Recent pay statements or other evidence of current qualifying income.
These records help distinguish an involuntary income interruption from an ordinary job change.
Illness or Medical Expenses
Explain how the medical hardship affected household finances. A continuing medical condition and continuing financial instability are different questions. Focus on:
- When income decreased, or expenses increased.
- How those changes affected payments.
- What income is available now.
- What ongoing obligations remain and how they affect the ability to repay the proposed mortgage.
Explain how you have recovered financially by showing your current income, manageable debts, and a positive payment history. It is possible to have a stable financial situation even if you are still dealing with a medical condition. You can use documents like medical bills, insurance explanations of benefits, claim settlements, employer records showing leave or reduced income, and recent income or account statements as evidence. Fannie Mae also accepts medical reports, bills, and insurance records as supporting documents. The lender will identify the evidence needed for the particular claim and loan program. Ask which records are relevant before submitting medical information; do not assume that a complete medical history is required.
What Usually Does Not Qualify as an Extenuating Circumstance?
Not every financial problem qualifies simply because it made payments difficult. Situations that generally do not support an extenuating-circumstances exception by themselves include:
- Excessive spending
- Taking on more debt than the borrower could afford
- Poor money management
- Repeated late payments without a documented hardship
- Voluntarily stopping payments
- A predictable expense that was not financially planned for
- A pattern of recurring financial problems
A borrower also should not assume that a job change, divorce, or business problem automatically qualifies. The lender must look at what actually happened, whether it was outside the borrower’s control, and whether it directly caused the derogatory credit. That is why the extenuating circumstances guidelines focus more on the facts and documentation than on the name of the hardship.
What Should an Extenuating Circumstances Letter of Explanation Include?
The letter of explanation should be short, factual, and supported by the documents in the loan file. It should explain:
- What happened
- When it happened
- Why was it outside the borrower’s control?
- How it caused the financial hardship
- Which payments or credit events were affected
- When the situation was resolved
- What has changed since then
Avoid turning the letter into a long personal story. The underwriter needs a clear connection between the event and the derogatory credit. For Fannie Mae loans, the written explanation must also demonstrate that the borrower had no reasonable alternative but to default on the affected financial obligations.
Keep the Letter Consistent With the Documentation
Dates, employment information, account history, and hardship details should match the supporting documents. An explanation that conflicts with the credit report, bankruptcy records, tax returns, or employment history can create additional underwriting questions.
What an Underwriter Checks Before Considering an Exception
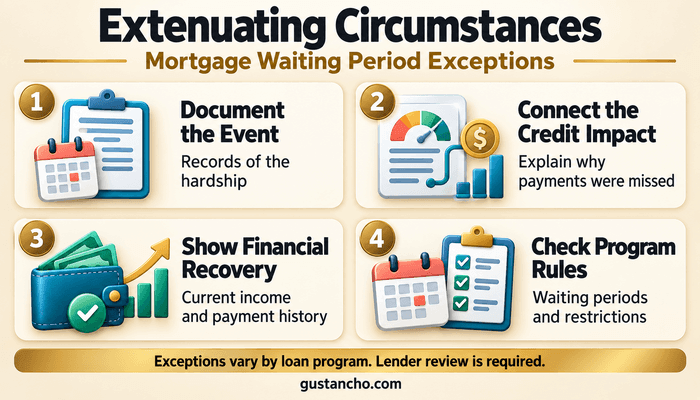 An underwriter compares the explanation with the borrower’s financial history. Four questions help determine whether the evidence supports the request.
- Did payment problems begin before the hardship? The underwriter looks at when the hardship occurred and compares it to the first missed payments and the account’s earlier history. If there were late payments before a layoff, those need a separate explanation. A hardship that happened later might explain some issues, but not the whole credit history.
- Was the financial impact large enough to account for the default? The review looks at the borrower’s household income both before and after the event, as well as their necessary expenses, benefits, severance payments, and available funds; it is important to note both the amounts involved and the length of time for which they apply, since the records must demonstrate how the financial disruption affected the borrower’s ability to meet their obligations.
- Were reasonable alternatives available? Where the program requires this analysis, explain why available resources could not prevent default. For example, Fannie Mae requires a written explanation to establish that the borrower lacked reasonable alternatives. Insurance delays, funding restrictions, and necessary household expenses may help explain what happened.
- Does subsequent payment history support an isolated hardship? The underwriter looks at how the borrower managed their debts after their finances got better. If payments have been made on time, this supports the borrower’s explanation. If there are more late payments, these need to be reviewed further. USDA’s exception guidance also asks the lender to explain why the problem is unlikely to recur and why the borrower remains a good credit risk.
Hypothetical Example: Job Loss Followed by Missed Payments
In May, the borrower loses their job and as a result their monthly take-home income drops from $6,500 to $2,800; total housing and other essential expenses amount to $4,300. The $3,000 in available savings is enough to meet about two months of the $1,500 monthly shortfall. The first missed mortgage payment is due in July. There is evidence to support the request: the employer’s records verify the layoff; the account histories indicate that the payments had been up to date before hand; and the bank statements show that the household’s savings were decreasing as they were meeting their essential expenses. Subsequent income and payment records indicate improved financial stability. There is evidence that casts doubt on the request: the mortgage payments had already become overdue before May; the records show that income had remained at its former level; or there were substantial accessible funds whose source could not be explained. Moreover, any further missed payments after income had recovered would also need to be accounted for. The underwriter would check that the records do, in fact, support the sequence described in the borrower’s letter.
Fannie Mae Extenuating Circumstances Guidelines
Chapter 7 or Chapter 11 Bankruptcy
The standard waiting period is four years from the bankruptcy discharge or dismissal date. Documented extenuating circumstances may reduce it to two years.
Chapter 13 Bankruptcy
A discharge requires two years, with no exception for extenuating circumstances. A dismissal normally requires four years, but documented extenuating circumstances may reduce that period to two years. Both periods start from the applicable discharge or dismissal date.
Multiple Bankruptcy Filings
More than one bankruptcy filing within seven years generally requires that five years have elapsed from the latest discharge or dismissal. An exception may reduce this to three years if the most recent filing was due to documented extenuating circumstances.
Foreclosure
The standard waiting period is seven years from foreclosure completion. Documented extenuating circumstances may reduce it to three years. Between years three and seven:
- LTV, CLTV, and HCLTV are capped at the lower of 90% or the transaction’s otherwise permitted maximum.
- Purchases are limited to principal residences.
- Limited cash-out refinances may be permitted for all occupancy types, subject to applicable eligibility requirements.
Second-home purchases, investment-property purchases, and cash-out refinances require the full seven-year period.
Short Sale, Deed-in-Lieu, or Mortgage Charge-Off
The standard waiting period is four years from completion of the event. Documented extenuating circumstances may reduce it to two years.
How Fannie Mae Measures the Waiting Period
For manually underwritten loans, the waiting period ends on the new loan’s disbursement date. Desktop Underwriter (DU) initially measures the period from the credit report date because it does not have the disbursement date. The lender must still verify that the required period has elapsed and may use the disbursement date for that determination. An early credit report can therefore affect the DU result. The lender may need an updated report and resubmission or an eligible manual underwriting review. DU also cannot independently determine whether a hardship qualifies as an extenuating circumstance; the lender must document that decision.
Bankruptcy and Foreclosure Involving the Same Mortgage
If the lender verifies that the mortgage debt was discharged in bankruptcy, the bankruptcy waiting period may apply. Otherwise, the longer applicable waiting period for bankruptcy or foreclosure applies. For the supporting records and timing details, see our guide to waiting periods when a mortgage was included in bankruptcy.
Extenuating Circumstances Guidelines for Mortgage Approval After Financial Hardship
Some lenders apply stricter overlays or may not consider all available exceptions. We’ll review your hardship, recovery, credit history, and mortgage options.Freddie Mac Extenuating Circumstances Guidelines
Manual Underwriting: Recovery Period Overview
With documented extenuating circumstances, Freddie Mac’s manual underwriting recovery periods are:
- Chapter 7 or Chapter 11 bankruptcy: 24 months from discharge or dismissal.
- Chapter 12 or Chapter 13 bankruptcy: 24 months from discharge or dismissal.
- Foreclosure: 36 months from completion, with a separate exception for qualifying mortgages extinguished in Chapter 7.
- Deed-in-lieu of foreclosure: 24 months from the execution date.
- Short sale: 24 months from completion.
These periods are measured to the new mortgage application date. Without an extenuating circumstances exception, Chapter 7 or Chapter 11 normally requires 48 months. Chapter 12 or Chapter 13 requires 24 months after discharge or 48 months after dismissal.
Property and Financing Restrictions
Under this exception path, a previous foreclosure or deed-in-lieu, or a short sale within the past seven years, limits financing to:
- Primary-residence purchases: LTV, TLTV, and HTLTV cannot exceed the lower of 90% or the transaction’s otherwise permitted maximum.
- No-cash-out refinances: The loan must meet Freddie Mac’s applicable refinance requirements.
Second-home purchases, investment-property purchases, and cash-out refinances are excluded from this path. The lender must also document completion of the housing event.
How Loan Product Advisor Findings Affect the Review
An Accept result from the Loan Product Advisor (LPA) means Freddie Mac has assessed the borrower’s credit reputation as acceptable. The lender must still satisfy the applicable Guide requirements and the conditions in the Feedback Certificate. With a Caution result involving significant derogatory credit, the lender must document qualifying extenuating circumstances or treat the difficulties as financial mismanagement. If the loan proceeds through permitted manual underwriting, the recovery periods and restrictions above apply. For the complete requirements and the special bankruptcy-and-foreclosure provisions, review Freddie Mac’s credit assessment requirements for manually underwritten mortgages.
FHA Extenuating Circumstances Guidelines
Chapter 7 Bankruptcy: Timing and Exception Requirements
FHA normally requires 2 years between the Chapter 7 discharge and the assignment of an FHA case number. During that period, the borrower must have rebuilt good credit or avoided taking on new credit obligations. A manually underwritten loan may be considered after at least 12 months but less than two years, when the lender documents:
- A hardship beyond the borrower’s control caused the bankruptcy.
- The borrower has managed finances responsibly afterward.
- The borrower’s present circumstances indicate that the events leading to bankruptcy are unlikely to recur.
Foreclosure and Deed-in-Lieu: The Limited Divorce Exception
The usual waiting period is three years before case number assignment, measured from the deed-in-lieu date or transfer of ownership to the foreclosing entity. A documented hardship exception also requires that good credit be re-established. Divorce alone does not qualify. FHA recognizes a narrow exception when:
- The mortgage was current when the borrower divorced.
- The former spouse received the property.
- The mortgage was subsequently foreclosed.
An inability to sell due to a job transfer or relocation does not qualify on its own.
Short Sale: What “Remained Current” Requires
The standard three-year period runs from the title transfer through the short sale to case number assignment. The borrower-current exception may eliminate that wait when, throughout the 12 months preceding the short sale, both the prior mortgage payments and installment-debt payments were made within the month due. A separate hardship exception requires documented circumstances beyond the borrower’s control and subsequent credit recovery. FHA also recognizes a narrow divorce-related short-sale exception when the mortgage was current at the time of divorce, the former spouse received the property, and a short sale followed.
Chapter 13: An Extenuating-Circumstances Exception May Not Be Needed
FHA’s ordinary manual underwriting rules may permit approval during an active Chapter 13 plan when:
- At least 12 months of the repayment period have elapsed as of the case number assignment.
- The most recent 12 months show satisfactory payment performance, with all required payments made on time.
- The borrower has written bankruptcy-court permission for the mortgage.
This is an established eligibility path under the updated handbook, rather than a request to shorten the Chapter 7 waiting period. VA also permits favorable consideration after at least 12 months of satisfactory Chapter 13 payments and approval by the trustee or bankruptcy judge. See our guide to VA loans during Chapter 13 bankruptcy.
VA Extenuating Circumstances Guidelines
VA does not treat bankruptcy, foreclosure, or short sale as an automatic permanent disqualification. Instead, the lender reviews the cause of the credit event, how much time has elapsed, and whether the Veteran has re-established satisfactory credit.
VA Chapter 7 Bankruptcy
A Chapter 7 bankruptcy discharged more than two years before closing may generally be disregarded for this purpose. When the discharge occurred between one and two years before closing, favorable consideration may be possible when:
- The borrower has re-established satisfactory credit, and
- The bankruptcy resulted from verified circumstances beyond the borrower’s control.
Examples given by VA include unemployment, prolonged strikes, and uninsured medical bills. A Chapter 7 bankruptcy discharged within the previous 12 months will generally make it difficult to determine that the borrower has re-established satisfactory credit.
VA Foreclosure
A foreclosure completed more than two years before closing may generally be disregarded. When the foreclosure occurred between one and two years before closing, the lender may consider the borrower for approval when satisfactory credit has been re-established, and the foreclosure resulted from verified circumstances beyond the borrower’s control. VA applies a similar fact-based review to a deed in lieu or a short sale. Unlike some other programs, VA explicitly states that divorce is generally not considered a circumstance beyond the borrower’s or spouse’s control.
USDA Extenuating Circumstances Guidelines
For USDA guaranteed loans, certain credit problems may qualify for a lender-approved exception. Loans receiving a GUS Accept or Accept with Full Documentation recommendation generally do not require a credit exception.
Who Makes the Credit Exception Decision?
When an exception is required, the lender must document that the circumstances were temporary, beyond your control, and unlikely to recur based on your household’s current situation. The lender’s underwriter reviews your supporting evidence, documents the reasons for the exception, and explains why you remain an acceptable credit risk. Your explanation and supporting records must be consistent with the rest of the loan file. The lender takes responsibility for the credit decision. USDA does not separately approve the lender’s credit exception, although USDA may request the documentation for review.
Problems a Credit Exception Cannot Waive
USDA does not allow lender-approved credit exceptions for:
- Previous USDA losses.
- Delinquent non-tax federal debts.
- Delinquent child support.
- Ineligible Credit Alert Verification Reporting System (CAIVRS) results.
These issues must be addressed under the applicable USDA eligibility rules. A documented hardship alone cannot override them. See USDA’s credit guidance, Attachment 10-A.
Re-Establishing Credit After an Extenuating Circumstance
A borrower usually needs to show that the financial hardship is over and that credit has been managed responsibly since then. Re-established credit may include:
- Housing payments are made on time.
- Installment accounts paid as agreed
- Revolving accounts kept current.
- No new serious derogatory credit
- Stable employment or income
- Improved cash reserves
There is no single credit-recovery rule that applies to every mortgage program. The lender will consider the time since the hardship, the severity of the prior credit event, and the borrower’s current financial position.
Avoid New Credit Problems During the Recovery Period
New late payments, collections, overdrafts, or other serious credit problems can weaken an extenuating-circumstances claim. The borrower is trying to show that the previous problem was isolated and unlikely to recur. A clean payment history after the hardship helps support that argument.
Common Reasons Extenuating Circumstances Are Denied
Not every hardship request is approved. Common reasons include:
- The event was not truly outside the borrower’s control.
- Documentation is incomplete
- The hardship does not line up with the dates of the credit problems.
- Late payments started before the claimed event.
- Financial problems continued long after the hardship ended.
- The borrower has not re-established satisfactory credit.
- The explanation conflicts with the credit report or bankruptcy records.
- The borrower had reasonable alternatives but chose not to pay
- The event is ongoing or likely to happen again.
Another common problem is trying to use a general life difficulty as an exception without showing how it actually caused the derogatory credit.
A Strong Story Is Not Enough
Underwriters rely on documents, dates, and credit history. A well-written letter of explanation can help organize the facts, but it cannot replace evidence. The strongest request is one where the explanation, supporting documents, and credit timeline all tell the same story.
Does Divorce Qualify as an Extenuating Circumstance?
The outcome varies by lender. The USDA includes divorce among the circumstances that may justify a credit exception. With Fannie Mae, the financial disruption in question must satisfy its own criteria for extenuating circumstances. The Veterans Administration usually does not regard a divorce as something beyond the control of the borrower or their spouse. With regard to the FHA, there is a limited exception for foreclosure or a short sale if the mortgage was up to date at the time of the divorce, the former spouse took over the property, and the foreclosure or short sale occurred thereafter. It is advisable to check the relevant section of the program before relying on such an exception.
Problems That Can Weaken Your Request—and Practical Next Steps
The Hardship and Credit Dates Do Not Match
Compare employment records, account statements, and credit-report dates. Identify when income actually stopped or expenses increased, when payments became delinquent, and when any bankruptcy or property transfer occurred. If an account shows an incorrect date, obtain records from the creditor or servicer and request a correction.
Documents Establishing the Event Are Missing
Request relevant third-party records from the employer, benefits agency, insurer, creditor, court, or mortgage servicer. If an original document is unavailable, ask the lender whether another verifiable record can establish the same facts.
Some Late Payments Predate the Hardship
Separate earlier delinquencies from those that followed the event. Explain each accurately and ask the lender how the earlier payment history affects the review. Do not attribute every credit problem to a later hardship.
Payment Problems Continued After Income Improved
Provide a current budget, recent income records, and payment histories. Explain any remaining obligations or delayed expenses that affected the recovery period. Ask the lender what additional payment history or financial changes are needed before reconsideration.
The Explanation Conflicts With Other Records
Check the letter against bankruptcy documents, tax returns, employment history, and account statements. Correct factual mistakes and explain genuine differences, such as the gap between a bankruptcy discharge and a later transfer of property.
The Event Does Not Meet the Program’s Exception Rules
Ordinary overspending, unaffordable borrowing, or recurring budget problems may not support an exception. Ask the lender to identify the unmet requirement and assess eligibility under the standard rules. If the obstacle is a waiting period or transaction restriction, confirm the relevant dates and available loan options.
Before Applying: A Short Checklist
- Confirm whether you need an exception or may qualify under ordinary program rules.
- Identify the loan program and whether automated or manual underwriting applies.
- Verify the relevant discharge, dismissal, or property-transfer date and the program’s waiting-period measurement point.
- Prepare your factual explanation and the supporting records requested by the lender.
- Review current income, debts, payment history, closing funds, and any property or transaction restrictions with your loan officer.
FAQs About Mortgage Extenuating Circumstances
Can Identity Theft or Fraud Support an Extenuating-Circumstances Request?
First, address accounts or charges resulting from identity theft through the appropriate credit-report correction or blocking process. The CFPB explains that you can request blocking by submitting an identity theft report, proof of identity, and a letter identifying the fraudulent information. Follow the CFPB’s identity-theft guidance. A separate question arises when fraud causes a financial loss that prevents you from paying a legitimate obligation, such as your mortgage. The lender may evaluate that loss as a potential hardship under the applicable program rules. Keep records distinguishing fraudulent accounts from genuine debts affected by the loss.
Do I Need an Exception if the Normal Waiting Period Has Already Passed?
You generally do not need an exception solely to shorten a waiting period that has already ended. The lender must still verify the relevant dates, evaluate your credit history, and confirm that you meet the remaining loan requirements. You may still need explanations or documentation concerning earlier credit problems.
Does One Bankruptcy for Each Spouse Count as Multiple Bankruptcies?
Under Fannie Mae’s rules, no. One bankruptcy for the borrower and one for the co-borrower do not add up to multiple bankruptcies. The lender evaluates each borrower’s history separately. If either borrower has more than one filing within the previous seven years, the multiple-bankruptcy requirements may apply to that borrower.
Does Having Savings During the Hardship Hurt My Request?
Savings can become part of the review, particularly when the program requires an explanation of why default could not reasonably be avoided. Document how much money was accessible, when it was used, and which necessary expenses it covered. Fannie Mae requires an explanation to establish that the borrower lacked reasonable alternatives to default.
Can I Get an Exception Approved Before Applying for a Mortgage?
A loan officer can conduct a preliminary review and identify likely loan options and missing documents. Final acceptance of an exception generally occurs during the underwriting of the actual mortgage application. An initial assessment helps you prepare, but the decision depends on the complete loan file and applicable requirements.
What Can I Do if a Lender Declines My Exception Request?
Ask for the specific reason and whether it involves a program requirement, the lender’s own policy, missing documentation, or your current financial qualifications. Provide relevant missing records and correct factual errors. If a waiting period or credit-recovery requirement remains unmet, ask what must change before reconsideration. You can also seek another lender’s assessment using the same complete, accurate information; that lender must still follow the applicable program rules.
This article about “Extenuating Circumstances Guidelines for Mortgage Approval After Financial Hardship” was updated on October 5th, 2026.