Saving enough for a down payment and closing costs can delay a home purchase even when the monthly payment fits your budget. Colorado DPA mortgage programs may help eligible buyers cover part of those upfront expenses through grants or assistance loans.
The important questions are how much help you can receive, whether you must repay it, and which program fits your situation. Some options serve both repeat buyers and first-time buyers.
This guide focuses on assistance. For a broader comparison of financing choices and mortgage qualification requirements, read our Colorado mortgage loans guide.
How Colorado Down Payment Assistance Works
Down payment assistance provides financial help for buying a home, covering costs such as the down payment, closing costs, and prepaid items like insurance. CHFA, the Colorado Housing and Finance Authority, offers assistance through participating lenders. Its assistance must be paired with an eligible CHFA first mortgage. You must satisfy the requirements for both. Your lender determines the approved amount and documents how it will be applied at closing. Assistance is not an automatic cash payment simply because you are buying a home.
CHFA Grants and Second Mortgages: Amounts and Repayment
CHFA’s standard assistance choices have different repayment obligations. The option available to you depends on the selected first mortgage program.
CHFA Down Payment Assistance Grant
CHFA’s standard DPA grant provides up to $25,000 or 3% of the first mortgage loan amount, whichever is less. The grant does not require repayment. Grant assistance is available with specified programs. For example, SmartStep Plus offers a grant option, while Preferred Plus uses second-mortgage assistance. Do not assume every CHFA mortgage offers both choices. Review CHFA’s down payment assistance information with your lender before selecting a program.
CHFA Down Payment Assistance Second Mortgage
CHFA’s standard DPA second mortgage offers up to the lesser of $25,000 or 4% of the first mortgage loan amount. It carries a zero-percent interest rate, with no accrued interest or scheduled monthly payments. The balance remains a debt secured by the home. Repayment is generally triggered by events such as paying off the first mortgage, selling or refinancing the property, or ending its use as your primary residence. Limited refinance exceptions may apply. Specialized CHFA programs can have different assistance amounts. Read the terms for the actual assistance loan you are considering.
Example: Assistance on a $400,000 First Mortgage
With a hypothetical first mortgage of $400,000, the standard maximum grant is $12,000, and for a second mortgage, the standard maximum is $16,000. In this case, the second mortgage offers a greater potential sum but includes a repayable balance. These calculations show the maximum amounts available under the programs. The amount you are approved for will depend on the eligible costs, the borrower’s contribution requirements, and the program chosen.
Short on Down Payment or Closing Costs?
Colorado DPA programs may help with down payment and, depending on the program, certain closing costs. Get a realistic cash-to-close estimate before you start house hunting.Which CHFA Programs Offer Down Payment Assistance?
CHFA programs connect assistance to a specific first mortgage and to eligibility rules. The following options are useful starting points for a lender review. Use CHFA’s current program matrices to confirm the complete requirements.
CHFA Preferred and Preferred Plus
Preferred pairs conventional financing with CHFA’s program requirements. Preferred Plus adds optional second-mortgage assistance. This program is not restricted to first-time buyers. A repeat buyer may qualify if the application meets the current requirements. It does not offer CHFA’s standard DPA grant.
CHFA SmartStep and SmartStep Plus
SmartStep supports eligible FHA, VA, or USDA first mortgages. SmartStep Plus offers assistance through a grant or second mortgage, subject to program requirements. First-time buyer status is not required. Ask the lender to compare the available assistance options and the first-mortgage pricing for each.
CHFA FirstStep and FirstStep Plus
FirstStep uses FHA financing. FirstStep Plus also offers help with a second mortgage, but CHFA’s standard grant is not available with this option. Usually, only first-time buyers, qualified veterans, or repeat buyers purchasing in certain areas are eligible to apply. There are also income and purchase price limits. Before you decide, ask your lender to explain any federal recapture-tax rules that might apply.
CHFA HomeAccess and HomeAccess Plus
HomeAccess serves eligible borrowers living with a permanent disability, as well as eligible custodial parents and legal guardians of an individual living with a permanent disability. Specific documentation and occupancy requirements apply. HomeAccess Plus can provide a zero-interest second mortgage of up to $25,000, regardless of the first mortgage amount. The current matrix specifies a $500 minimum borrower contribution, which may be made with an eligible gift. HomeAccess is not restricted to first-time buyers, and military service is not a general eligibility requirement. Review the current HomeAccess program matrix for the complete terms.
Who Qualifies for Colorado DPA Mortgage Programs?
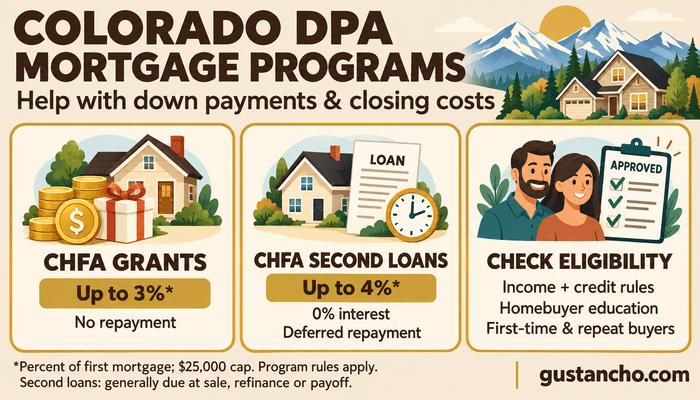
There is no single eligibility standard for every Colorado assistance program. Start with the specific program name, then check its rules against your finances and the property.
Credit Requirements
CHFA generally requires a qualifying credit score of at least 620 for scored borrowers. Certain programs may accommodate borrowers without a credit score, subject to their underwriting rules. Having no credit score is different from having a score below the program minimum. A lender’s flexible approach to the first mortgage cannot waive an assistance program’s requirements. Your debts, payment history, qualifying income, and underwriting findings also affect approval.
Income Limits and How Income Is Counted
All CHFA home loan programs have income limits, but their limits and calculation methods differ. Some use mortgage qualifying income. Others require a separate gross annual income calculation that can include income from household members who are not borrowing. Tell the lender who will live in the home and disclose the household’s sources of income. Do not assume that leaving a spouse off the mortgage excludes that spouse’s income from every assistance calculation.
First-Time Buyer Status and Prior Ownership
For CHFA programs that require first-time buyer status, the definition generally refers to ownership of a principal residence during the three years preceding closing. Someone who owned a home earlier may still satisfy that definition. Exceptions can also apply under specified programs. Have the lender review your ownership history before deciding that you are ineligible.
Property and Occupancy Requirements
CHFA purchase assistance is for eligible owner-occupied homes only; vacation homes and investment properties do not qualify. Property eligibility depends on the selected mortgage and assistance program. Condos, manufactured homes, homes with accessory dwelling units, and other property types require the appropriate review. Send the lender the listing and property details before relying on assistance in your offer. A borrower’s eligibility does not establish that every property qualifies.
Homebuyer Education and Your Required Contribution
CHFA requires borrowers and co-borrowers to complete approved homebuyer education before closing. Use a CHFA-approved provider and confirm the certificate meets the selected program’s requirements. Many CHFA purchase programs require a minimum $1,000 borrower contribution, although specialized programs can differ. That minimum does not guarantee that $1,000 covers your entire purchase. You may still need funds for costs that assistance does not cover. Ask for an estimate showing your total cash to close after assistance, earnest money, and permitted credits.
Local Colorado Assistance: metroDPA and Aurora
Statewide assistance is one place to start. Local programs have separate geographic boundaries, income rules, and funding arrangements.
metroDPA in Participating Front Range Communities
Denver sponsors metroDPA for eligible purchases in participating Front Range cities and counties. You do not necessarily have to buy within Denver to use it. The current program describes assistance as an interest-free, deferred second mortgage. Repayment can be required when the first mortgage is paid off through a sale or refinance, or when the home stops being your primary residence. Check the address and current terms through the official metroDPA program information. Have the lender confirm the assistance amount and repayment terms for the option being offered.
Aurora Down Payment Assistance
Aurora provides a discount of up to 10% of the purchase price for eligible homes located within the city boundaries, on the condition that the income requirements are met. Help is available on a silent second loan basis without any monthly payments, and repayment takes place when the first mortgage is sold, refinanced, or paid off. Before including assistance in your purchase plan, check the City of Aurora’s assistance page to make sure it is available.
Compare the Costs of Using Down Payment Assistance
Assistance can help you buy sooner, but the upfront benefit should be weighed against the first mortgage’s costs and any future repayment obligations.
Ask for comparable estimates with and without assistance using the same property, loan amount, and loan term. Examine the first-mortgage rate, monthly payment, fees, cash required at closing, and assistance balance.
A deferred second mortgage also matters if you expect to move or refinance soon. Its payoff can affect your sale proceeds or the funds needed for a refinance. A grant and a zero-interest second mortgage produce different financial commitments. Choose based on the complete offer and your plans for the home.
How to Apply for Colorado Down Payment Assistance
Start the assistance review early enough to identify eligibility issues before you commit to a property or closing deadline.
Identify the Program and Participating Lender
Tell the lender where you plan to buy, your approximate budget, your household income, available savings, and whether you have owned a home before. For CHFA assistance, use a CHFA participating lender. For local programs, confirm the lender can work with that specific assistance provider. Ask which program is being evaluated and what approval or funding steps remain.
Provide Assistance-Specific Documentation
Along with the first-mortgage documents, the lender may need records supporting prior homeownership, household income, completion of education, an eligible gift, or eligibility for a specialized program. FirstStep may require additional affidavits. HomeAccess requires acceptable disability-related documentation. Local assistance can require a separate application. Request the checklist for the named program so you can provide the right records from the start.
Confirm the Funds and Closing Requirements
Before depending on assistance, obtain a clear explanation of the approved amount, your remaining cash requirement, and any outstanding program conditions. Ask who reserves or approves the assistance, whether funds have been committed, and what happens if the property or closing date changes. Review the grant terms or second-mortgage documents before signing.
Final Thoughts on Colorado DPA Mortgage Programs
Before relying on assistance, get answers to three questions: How much has been approved? How much money must you still bring to closing? What future events could require repayment?
Those answers will help you decide whether the assistance fits your purchase and your home plans.
To discuss Colorado DPA mortgage programs, call Gustan Cho Associates at (800) 900-8569 or email gcho@gustancho.com. Share where you plan to buy and your household situation so the team can review potential options and applicable lender requirements.
Colorado Down Payment Assistance FAQs
Can I Receive Both a CHFA Grant and a CHFA DPA Second Mortgage?
No. CHFA does not allow borrowers to combine its DPA grant and DPA second mortgage into a single first-mortgage transaction. A separate local assistance program would require its own compatibility review.
Can I Add CHFA Assistance to Any Mortgage?
No. CHFA assistance must be paired with an eligible CHFA first mortgage. Confirm the program combination before selecting a lender or assuming assistance can be added to an existing loan offer.
Can CHFA’s Grant Pay Off Credit Cards or Cover an Appraisal Shortfall?
No. CHFA’s DPA grant cannot be used to pay off debt or to cover the gap between the sale price and the appraised value. Assistance must be applied to permitted costs.
Can I Receive Unused CHFA Assistance as Cash Back?
No. Excess funds from a CHFA DPA grant or second mortgage cannot result in cash back to the borrower. Any permitted reimbursement of your own documented funds is a separate question governed by the applicable loan rules.
Can Gift Money Meet My Required Borrower Contribution?
Eligible gift funds may satisfy the contribution requirement. Have the lender verify the source, documentation, and eligibility under both the assistance program and the first mortgage.
What Happens to My CHFA Assistance Loan If I Refinance?
You generally must repay the assistance balance. Certain eligible CHFA FHA Streamline refinances may allow the existing second mortgage to remain through approved subordination. Home Access assistance loans are not eligible for that exception. Confirm the applicable terms before planning a refinance.
This article about “Colorado DPA Mortgage Programs For First-Time Homebuyers” was updated on September 29th, 2026.