Buying a Second Primary Home While Renting Your Current Home
You can buy a new primary residence and keep your current house as a rental. You don’t have to sell your current home before qualifying for another owner-occupied mortgage. The key is to show the new property will be your main home and that you can qualify for the new loan while still paying your current mortgage.
Often, rental income from your current home can help cover some or all of that mortgage payment. Lenders often call the home you’re moving out of your departing residence.
Many people say ‘second primary home,’ but that’s not technically correct. Lenders don’t allow you to have two primary residences at the same time. Usually, you buy a new home as your main residence and turn the old one into a rental or investment property. In short, you can buy a new primary residence without selling your current home. If you rent out your old home, qualifying rental income may help cover its mortgage.
Can You Buy Another Primary Residence Without Selling Your Current Home?
As of September 2, 2026, Fannie Mae generally allows 75% of documented market rent and may require six months of reserves if you have less than a year of property management experience. Freddie Mac has its own documentation rules. Yes. There is no general, conventional mortgage rule requiring homeowners to sell their current residence before purchasing another home to become their new primary residence. You must still qualify for the new mortgage.
Fannie Mae specifically recognizes a primary residence that will be vacated and converted to an investment property when the borrower purchases a new primary residence as an eligible departing residence.
Lenders will ask what you plan to do with your current home. You can sell it, keep it as a second home, leave it vacant for a while, or turn it into a rental. determines whether any rental income can be used when calculating your debt-to-income ratio.
What Does Buying Second Primary Home Really Mean?
The term “second primary home” is widely used by consumers, but it is not the best technical term. A principal residence is the property you primarily occupy as your home. Fannie Mae defines a principal residence as a property occupied by the borrower as their primary residence. FHA is even more explicit: its current Handbook states that a person may have only one Principal Residence at any one time.
Therefore, a Homeowner Moving From House A to House B Generally Has:
- House A is the former or departing residence, which may become an investment property.
- House B becomes the new principal residence.
- Owning both homes is usually not the issue. What matters most are your plans for the new home, your debt-to-income ratio, how you document rental income, your savings, and the mortgage program you choose.
Difference Between Second Home versus Investment Property
These occupancy classifications should not be confused.
- A primary residence is normally the property you intend to make your main home.
- A second home is generally an additional property the borrower personally occupies but does not use as the primary residence.
- An investment property is primarily owned to generate rental income or investment returns.
- If you are permanently moving into the new property and renting your old home to tenants, the new property would generally be treated as your principal residence and the former home as an investment property.
- The borrower’s actual intentions for the property are a critical consideration.
- It is not permissible to misrepresent a rental property as a primary residence or to claim multiple primary residences in order to obtain more favorable mortgage terms.
How Mortgage Lenders Qualify You When You Keep Your Current Home
The hardest part of buying another primary residence is usually not owning two homes. It is qualifying with two housing obligations. Suppose you are qualifying for a mortgage while having two housing payments. You have your current mortgage payment, and the new home will have a $3,000 monthly housing payment. Without usable rental income, the lender may have to consider both obligations when determining whether your income can support the new mortgage. This can make your debt-to-income ratio much higher.
Issues With Having Two Mortgage Payments
This can raise your debt-to-income ratio a lot until the old home is sold, paid off, or qualifies for special mortgage rules. The lender must count that housing cost. This payment usually includes the loan principal, interest, property taxes, homeowners’ insurance, mortgage insurance if needed, homeowners’ association fees, and other required housing costs. This total housing cost is often called PITIA. Fannie Mae specifically requires lenders to consider the status of other real estate owned when qualifying the borrower. A current principal residence converting to investment use must be evaluated under the applicable rental-income and reserve guidelines.
Rental Income Can Help You Qualify
Rental income may allow you to offset some or all of the departing residence’s mortgage expense. But lenders usually don’t add the full lease amount to your income. Agency rules consider vacancies, maintenance, operating costs, and other landlord expenses. Fannie Mae and Freddie Mac currently use a 75% treatment in applicable departing-residence calculations, although their documentation requirements and treatments of positive income differ.
Debt-to-Income Ratio Still Matters
There is no single DTI percentage that guarantees approval for every borrower. The acceptable debt-to-income ratio depends on the loan program, credit profile, automated underwriting findings, down payment, reserves, income stability, property type, and lender requirements. If you get automated approval, you might qualify with a higher debt-to-income ratio than someone with a different risk profile. That’s why it’s important to get the details of your departing residence right.
Can Rental Income Help You Qualify for the New Home?
Lenders may count rental income from your departing residence if the lease, deposit, equity, and reserve requirements are documented correctly.Fannie Mae Departing Residence Rental Income Guidelines for 2026
Fannie Mae changed its departing-residence guidelines in September. This matters because some older mortgage articles still mention outdated equity requirements. Under current Fannie Mae guidance, a primary residence that will be vacated and converted into an investment property when the borrower purchases a new primary residence is eligible for departure-residence rental-income treatment.
Fannie Mae No Longer Uses the Old 25% Equity Rule Shown in Many Articles
Older mortgage guidance frequently stated that borrowers needed at least 25% equity in their departing residence before projected rental income. That is no longer the standard Fannie Mae rule for departing residences. Fannie Mae’s September 2, 2026, rules focus on the borrower’s current housing payment, proof of market rent, how rental income is calculated, property management experience, and required savings. Some lenders may have stricter rules than Fannie Mae’s minimum guidelines. These extra rules are called lender overlays.
How Fannie Mae Documents Rent on a Departing Residence
The lender must document a current housing payment to qualify using rental income from the departing residence. The lender must also document the monthly market rent. Under Fannie Mae’s current rules for leaving a home, acceptable proof may include a full property appraisal showing market rents, a rent comparison form, such as Form 1007, for the occupied home, or approved market analysis tools. Fannie Mae allows market analysis from sources such as MLS, Zillow, Redfin, or similar sites if the lender identifies at least 3 comparable rental properties and follows the rules.
Fannie Mae Does Not Permit a Lease for a Departing Residence
This is an important change to be aware of. Rules: lease agreements cannot be used as proof of rental income for a home you are leaving. That is different from Freddie Mac. Borrowers and loan officers should find out early whether the loan follows Fannie Mae or Freddie Mac rules, rather than assuming the paperwork is the same.
How Fannie Mae Calculates Departing Residence Rental Income
Fannie Mae usually takes the documented total monthly market rent and multiplies it by 75%.
- The lender then subtracts the full housing payment on the home you are leaving.
- Assume the documented market rent is $3,200 per month.
- Seventy-five percent of $3,200 is $2,400.
- If the departing residence has a $2,200 PITIA, the adjusted result is $200 higher.
- Under the current Fannie Mae rule,
- if the result is positive, it can reduce the housing payment on the old home, but any extra amount cannot be added to your income for qualifying.
- If the housing payment were $2,800 instead, the calculation would show a $400 monthly loss.
- That $400 would usually be counted in your debt-to-income ratio.
Fannie Mae Reserve Requirements for a Departing Residence
Another major requirement involves cash reserves. If the borrower has less than a year of property management experience, Fannie Mae requires the lender to verify that the borrower has 6 months of savings to cover the housing payment on the old home. These savings are in addition to any other savings required because the borrower owns several financed properties. Planning ahead is essential. You might have enough income to qualify, but you could run into problems if you use too much cash for the down payment and closing costs on your new home.
Freddie Mac Guidelines for Converting a Primary Residence to a Rental

Freddie Mac also allows rental income from a primary residence to be converted into an investment property. However, Freddie Mac’s documentation rules differ from Fannie Mae’s. This difference matters because if you don’t fit one agency’s rules, you might have a better option with the other.
Freddie Mac Can Use a Lease. Lease documentation permits a lease when documenting rental income from converting a primary residence to an investment property.
The lease must be current and fully executed. For a newly executed lease, the first rental payment must generally be due by the first payment due date of the new mortgage. The rent amount on the lease must be backed up. This can include an appraisal or rent schedule, proof of rental payments received, or proof of the security deposit and first month’s rent.
Freddie Mac Generally Uses 75% of Gross Rent
Freddie Mac calculates qualifying rent from an applicable lease using 75% of the gross monthly rent. The 25% reduction covers possible empty periods, running costs, repairs, and other unexpected expenses. For example, a $3,000 monthly lease would generally produce $2,250 in rental income before comparing it with the departing property’s housing expense.
Property-Management Experience Can Affect Freddie Mac Rental Income
Freddie Mac distinguishes between borrowers with prior property management experience and those without. When at least one borrower has at least 1 year of investment-property management experience, the full qualifying net rental income may be used. If no borrower has at least 1 year of property management experience, rental income is usually limited to covering only the monthly housing payment on the old home. This difference is important if your property brings in extra cash each month.
Do You Need to Sell Your Current Home Before Closing on the New House?
The right strategy depends on income, assets, equity, debt-to-income ratio, and whether the borrower needs proceeds from the existing home for the new purchase. Many homeowners buy their next primary residence before selling or renting out their current home.
The right strategy depends on income, assets, equity, debt-to-income ratio, and whether the borrower needs proceeds from the existing home for the new purchase.
Someone with high income may qualify while carrying both housing payments without using any rental income. Another borrower may need departing-residence rental income to make the DTI work. A third borrower may need proceeds from the sale of the existing home for the down payment. These are three very different mortgage situations, even though each borrower is buying a new primary residence.
Advantages of Purchasing a New Home Prior to Selling the Existing Property
Buying your new home before selling the old one can make things less stressful because you don’t have to close both deals at once. This approach also lets you move into the new property first, get the old home ready for tenants, make repairs, or avoid moving twice back is the potential obligation to pay two mortgages simultaneously. Sufficient savings and adherence to qualification requirements are therefore critical.
A Home-Sale Contingency Is Another Option
Some buyers make the purchase of their new home contingent on selling their existing property. This may reduce financial risk for the buyer, but sellers do not always accept home-sale contingencies, especially in competitive housing markets. It’s a good idea to check if you qualify for a mortgage before making an offer. Showing you can qualify without selling your current home can make your offer stronger.
Can You Rent Out Your First Home Without Refinancing It?
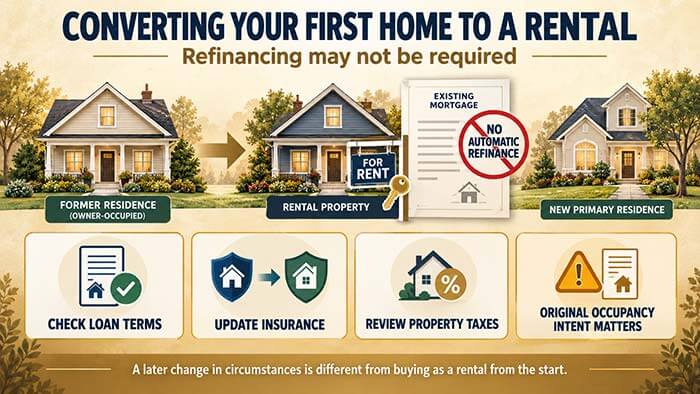
Turning your old primary residence into a rental doesn’t mean you have to refinance your current mortgage into an investment-property loan. Fannie Mae’s own departing-residence guidelines specifically contemplate a borrower vacating a principal residence and converting it to investment use while purchasing another principal residence.
If you turn your home into a rental, talk to your insurance agent. You may need to change your owner-occupied policy to a landlord policy. Homestead exemptions and other property tax benefits may change if your home is no longer your main residence.
However, borrowers should check the occupancy terms in their original mortgage papers. Owner-occupied loans are made with the intention that the borrower will live in the home when the loan closes. A borrower should never buy a home as a primary residence if they plan to use it only as a rental from the start. A change in circumstances is different.
Can You Buy Your New Primary Home in Another State?
Yes. Many people keep a home in one state while buying a new primary residence in another. They may use employment relocation, retirement, moving closer to family, lower living costs, marriage, divorce, or lifestyle changes. Your lender will need to know how the move affects your income for qualifying.
Moving With the Same Employer
If you move to a new location but keep working for the same employer, your income situation is usually straightforward. The lender may ask for documents showing your transfer, your new work location, your salary, and confirmation that your job will continue.
Starting a New Job After Relocating
Starting a new job doesn’t automatically stop you from qualifying for a mortgage. However, the lender has to make sure your income meets the paperwork and stability rules for the loan. Things like job contracts, offer letters, start dates, salary, bonuses, and savings can all affect whether you qualify.
Moving to Another State
Retirees may qualify using eligible retirement income instead of employment income. Social Security, pensions, retirement distributions, annuity income, investment income, and certain asset-based income calculations may potentially be used when they meet the applicable mortgage guidelines. It is advisable It’s smart to check your mortgage qualifications before you retire or make big job changes.
Having Two Mortgage Loans at the Same Time?
Sometimes, but FHA is more restrictive than conventional financing in this area. HUD’s current FHA Handbook 4000.1 states that a Principal Residence is the dwelling where the borrower maintains or will maintain their permanent home and generally occupies for the majority of the calendar year. FHA also states that a person may have only one Principal Residence at any one time. If you already have an FHA-insured mortgage on your current principal residence, FHA generally will not insure another property as your principal residence unless you qualify for one of HUD’s specific exceptions.
FHA Relocation Exception
One exception involves employment-related relocation. A borrower may obtain another FHA-insured mortgage without selling the property securing the existing FHA loan when relocating for an employment-related reason and establishing a new principal residence more than 100 miles from the current principal residence.
FHA Increase in Family Size Exception
Another exception may apply when the borrower’s legal dependents have increased, and the current home no longer meets the family’s needs. HUD requires satisfactory evidence of an increase in legal dependents, and the loan-to-value ratio on the current principal residence must generally be 75% or less or be paid down to that level based on the outstanding mortgage balance and a current residential appraisal.
Vacating a Jointly Owned Property
FHA also provides an exception when a borrower vacates a jointly owned principal residence with no intention of returning, while an existing co-borrower continues to occupy the property. There is also an exception involving certain non-occupying co-borrowers on existing FHA-insured mortgages. These rules differ from simply owning another property. The restriction is especially important when a borrower wants to maintain one FHA-insured principal residence mortgage while obtaining another FHA-insured mortgage.
Have Two VA Loans at the Same Time?
Eligible Veterans may sometimes keep an existing VA-financed property and purchase another primary residence using their remaining VA entitlement. VA specifically states that Veterans do not have to be first-time homebuyers and that there is no lifetime limit on how many times the VA home loan benefit can be used.
When a Veteran still has an outstanding VA mortgage, the Certificate of Eligibility can show how much entitlement remains available.
The new property must still satisfy VA’s occupancy requirement and become the Veteran’s residence. If there is insufficient remaining entitlement to provide the required guaranty for the new loan, a down payment may be required. This is commonly referred to as using remaining entitlement or second-tier VA entitlement.
How Cash Reserves Affect Buying Another Primary Residence
Keeping cash reserves is especially important if you keep your current home. Lenders want to know you can keep making payments if the home is vacant, tenants don’t pay, or repairs come up. Reserves are usually the money you have left after your down payment and closing costs. Depending on the program, checking, savings, some investment accounts, and certain retirement assets may count as reserves. Fannie Mae requires six months of savings to cover the old home’s payment if you have less than a year of property management experience. You may need more savings if you own several financed properties. Sometimes, putting less down is a better mortgage strategy.
Denied Because You Are Keeping Your Current Home?
Some lenders apply overlays or misunderstand departing-residence rental income rules. We’ll review your file and compare FHA, VA, conventional, and Non-QM options.Buying Second Primary Home With Both Mortgages?
If your income is high enough to cover both mortgage payments, it’s often easier to get approved since you don’t have to depend on rental income. Suppose a borrower earns $12,000 per month and has a $2,500 mortgage on the current home. The new home will have a $3,500 monthly payment. Adding both payments brings housing costs to $6,000, not counting car loans, student loans, credit cards, or other debts. Using qualifying rental income from your old home can significantly reduce the housing payment used in your mortgage application. The best approach depends on your full financial situation.
Common Mistakes When Buying Second Primary Home and Renting the Old One
A common mistake is thinking a signed lease means the lender will count all the rent. That is not the case. Fannie Mae’s current rules do not allow a lease to be used as proof of rent in this situation, but Freddie Mac allows a properly documented and supported lease. Another mistake is making a down payment that leaves you with too little in reserves. Borrowers sometimes forget that turning a home into a rental can affect insurance, property taxes, tax breaks, and maintenance. Another mistake is waiting until after signing a purchase contract to find out if rental income from the old home will count. It’s important to have a mortgage strategy before making an offer.
Best Mortgage Strategy for Buying Before Selling or Renting Your Current Home
Start by deciding what you want to do with your current home. If you plan to sell, find out if the sale needs to close before you buy the new home. If you want to keep it, decide if it will stay vacant, be used by you, or be rented out. Next, see if you qualify while making both payments.
If not, check whether you can use rental income from your old home and whether Fannie Mae or Freddie Mac is the better fit reserves before choosing your down payment amount.
If you already have an FHA or VA mortgage and want to use the same program again, check the extra rules about occupancy, entitlement, or having more than one mortgage before making an offer. It’s important to review your entire situation early, rather than assuming you have to sell your current home first. ‘Buying second primary home’ usually means buying a new primary residence while keeping your old one.
Many Homeowners Don’t Have to Sell Their Current Property
The first home can potentially become a rental property. Your first home can become a rental while your new house becomes your primary residence.me ratio, departing-residence rental income, reserves, occupancy, employment or retirement income, and the mortgage program being used.
Fannie Mae’s September 2026 update matters because the old 25% equity rule no longer applies. Freddie Mac has different paperwork rules, so plan your loan before signing a purchase contract.
If someone told you that you have to sell your current home before buying another, it’s a good idea to have your situation reviewed under both Fannie Mae and Freddie Mac rules before making a decision.
Final Thoughts: Buying Second Primary Home
How much equity do you have in your current home, of if there is not equity, can you afford two mortgages? Buying next home can be incredibly confusing but it does not have to be. Buyers need to deal with a loan officer who is up-to-date on current guidelines. At Gustan Cho Associates, we hold our loan officers to a very high standard. Dale Elenteny, NMLS 904444, a senior mortgage loan originator at Gustan Cho Associates, says the following about buying second primary home:
Homebuyers should be up to all mortgage guidelines. If for any reason the loan officer does not know an answer, we have access to underwriters who will know the answer. So, you have decided you want to buy a new primary residence.
All in all, there are various mortgage strategies to finance a new home purchase prior to selling the exiting existing residence. To find options and qualify for a home mortgage with a lender with no lender overlays, please contact us at Gustan Cho Associates at 800-900-8569 or text us for a faster response. Or email us at gcho@gustancho.com. The team at Gustan Cho Associates is available 7 days a week, evenings, weekends, and holidays.
Frequently Asked Questions About Buying Second Primary Home and Renting Your Current Home
Can I Buy Another Primary Residence Without Selling My Current House?
Yes. Conventional mortgage guidelines do not automatically require you to sell your current property before buying a new primary residence. You must qualify for the new mortgage while properly accounting for the existing property and its housing expenses.
Can I Rent Out My Current Home and Use the Rent to Qualify for Another Mortgage?
Potentially. Both Fannie Mae and Freddie Mac have guidelines that allow qualifying rental income from a primary residence to be converted to an investment property. Documentation requirements differ between the agencies.
How Much Rental Income Can I Use From My Departing Residence?
Fannie Mae and Freddie Mac typically apply 75% of the eligible gross rent before comparing income to the property’s housing expense. How any positive or negative result affects qualification depends on the agency’s guidelines and the borrower’s property management history.
Do I Need 25% Equity to Rent My Current Home and Buy Another Primary Residence?
Not under Fannie Mae’s current September 2, 2026, departing-residence rule as a universal eligibility requirement. Older mortgage guidance frequently referenced a 25% equity rule, but Fannie Mae’s current policy focuses on market-rent documentation, qualifying rental-income calculations, housing-payment history, reserves, and property-management experience. Individual lenders may still impose overlays.
Do I Need a Signed Lease to Use the Rental Income From My Departing Residence?
It depends on the agency. Under Fannie Mae’s current departing-residence rules, a lease agreement is not permitted as the document used to establish the rental income. Freddie Mac permits a qualifying lease when its documentation and support requirements are met.
Can I Have Two FHA Mortgages if I Move to Another Home?
Only under certain circumstances. FHA generally limits borrowers to one FHA-insured Principal Residence, but HUD provides specific exceptions involving employment relocation, an increase in family size, vacating certain jointly owned properties, and qualifying non-occupying co-borrower situations.
Can I Keep My First VA Loan and Use it to Buy Another Primary Residence?
Potentially. Eligible Veterans may be able to use remaining VA entitlement while keeping an existing VA loan. The new property must become the Veteran’s residence, and a down payment may be required if the remaining entitlement is insufficient to cover the new loan amount.
Do I Have to Refinance My Current Mortgage When I Convert the Property to a Rental?
Not automatically. Borrowers who legitimately purchased and occupied their current home may later convert it to rental use without necessarily refinancing solely because they moved. However, the original mortgage documents, insurance coverage, property-tax treatment, and any applicable occupancy agreements should be reviewed before making the change.
Can I Buy a New Primary Residence in Another State and Keep My Old House?
Yes. This is common with employment relocations, retirement moves, and families moving closer to relatives. The lender will evaluate your new occupancy, qualifying income, existing housing obligation, departing residence rental income, if applicable, reserves, and overall debt-to-income ratio.