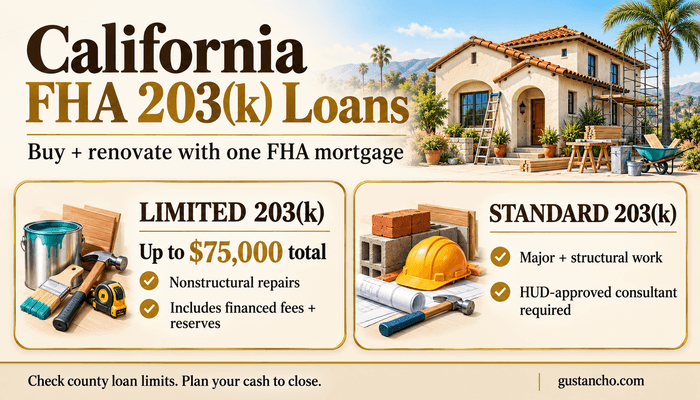
California FHA 203(k) loans allow eligible buyers to finance a home purchase and approved renovations with a single FHA-insured mortgage. You may qualify if you meet FHA borrower requirements, plan to occupy the home as your primary residence, and have an eligible property and an acceptable renovation plan. The Limited 203(k) covers qualifying nonstructural work with up to $75,000 in total rehabilitation costs, including applicable financed fees and reserves. The Standard 203(k) allows larger projects and structural repairs and requires a HUD-approved consultant. Your available financing depends on the project costs, after-improvement appraisal, borrower qualifications, and the county FHA loan limit.
What Are California FHA 203k Loans?
California uses HUD’s nationwide FHA 203(k) rehabilitation mortgage program; there is no separate California version. Eligible homeowners can also use the program to refinance and renovate an existing home. Federal program requirements apply statewide, while county loan limits, contractor pricing, permit requirements, and local building codes determine which properties and renovation plans are feasible.
How FHA 203(k) Financing Works
The buyer finds an eligible property, obtains estimates for the planned repairs, and applies for an FHA 203(k) mortgage based on the purchase and renovation project. The property is appraised with the proposed improvements taken into consideration. The lender then determines the maximum mortgage using FHA’s 203(k) calculation and the applicable county loan limit. At closing, the seller receives the funds due from the purchase, while the approved renovation funds are generally placed into a rehabilitation escrow account.
Repair Funds Are Not Given to the Borrower at Closing
The renovation funds are managed through the 203(k) process rather than handed directly to the homebuyer. Funds are released as approved work is completed and the applicable draw requirements are satisfied. This protects the borrower and lender by tying the renovation funds to the work being performed.
Limited vs. Standard FHA 203(k): Which one is right for you?
The correct FHA 203(k) option will depend on the scope of work required, the total rehabilitation budget, and whether the property can be occupied during construction. The Limited 203(k) covers qualifying minor renovations and non-structural repairs. The $75k rehabilitation limit includes applicable financing fees and contingency reserves, so the contractor’s bid must account for them. Eligible work is limited to roofing, HVAC, flooring, painting, and kitchen/bathroom updates (subject to the program’s scope restrictions).
The Standard 203(k) can be used for major rehabilitation, structural repairs, and eligible additions. Rehab costs must be $5,000 or more. The amount of renovation funds available is determined by the maximum mortgage calculation, the supported property value, and the county FHA loan limit.
A HUD-approved 203(k) consultant is required for Standard financing and optional for Limited financing. If a consultant is used, the lender will select an eligible consultant from HUD’s roster. The consultant will perform the property evaluation, prepare the work write-up and cost estimate, and assist with the required inspections, draw requests, and change orders. Structural work will normally require the Standard program even where the estimated cost of repair is less than $75k. Be sure to confirm the project type before finalizing contractor tenders. The $75,000 limit applies to the full eligible rehabilitation package, which includes financed fees and contingency reserves. These costs lower the amount left for the contractor’s work. For instance, if the repair bid is $75,000, it would use up the whole allowance before adding any extra financed rehab expenses. HUD’s 203(k) calculator factors in eligible fees and financed contingency reserves when figuring out the total rehab cost.
Ready to Explore a California FHA 203(k) Loan?
See whether a Limited or Standard FHA 203(k) loan may fit your purchase or renovation plans. Gustan Cho Associates can help you review the program requirements, property, and renovation details.2026 California FHA 203(k) Loan Limits
For 2026, FHA one-unit loan limits in California range from $541,287 in lower-cost counties to $1,249,125 in the highest-cost counties. Higher limits apply to eligible two- to four-unit properties. These limits apply to FHA case numbers assigned on or after January 1, 2026. Los Angeles and Marin Counties have a 2026 one-unit limit of $1,249,125, while Kern and Kings Counties have a one-unit limit of $541,287. Use HUD’s official FHA Mortgage Limits lookup to confirm the applicable limit by selecting California, the property’s county, FHA financing, and the correct limit year. The county limit generally applies to the base mortgage, which is the approved loan amount before financed upfront mortgage insurance is added. When you finance the upfront mortgage insurance premium, it is added to the base mortgage amount to establish the total mortgage amount. The total can therefore exceed the published county limit by the amount of the financed premium. This additional financing pays the insurance premium; it does not provide additional money for the purchase or renovations.
How the Appraisal and Maximum Mortgage Determine Your Financing
An FHA 203(k) appraisal considers the property’s expected market value after the approved improvements are completed. That after-improved value helps determine how much of the purchase and renovation project can be financed. When you buy a property, the FHA looks at the adjusted as-is value plus eligible rehab costs, fees, and reserves, and compares that to 110% of the appraised value after improvements. For condos, they use 100% of the after-improvement value. The loan-to-value ratio is applied to the lower amount, and the base mortgage must remain within the county FHA limit.
Usually, the county limit applies before you add financed upfront mortgage insurance. Make sure to distinguish between the base mortgage and the total mortgage balance when you review your financing numbers.
Spending money on renovations does not always mean your home’s value will go up by the same amount. The appraiser will compare your finished property to similar homes that have sold recently. If the appraised value or county limit keeps you from getting enough financing, you might need to renegotiate the price, change your planned improvements, or put in more of your own money. Look at the purchase price, full rehab budget, and expected financing all together before you decide to move forward with a project.
FHA 203(k) Costs Beyond the Down Payment
 When planning your budget, remember to include both the upfront FHA mortgage insurance and the annual mortgage insurance, which is paid monthly. You can usually finance the upfront premium or pay it at closing. Renovation costs might also cover consultant fees, draw inspections, permits, title updates, and contingency reserves. Ask for a written list that shows which costs can be included in your loan and which you’ll need to pay out of pocket. Be sure to plan for any closing costs not covered by the loan, prepaid taxes and insurance, and any reserves you need to fund yourself. When comparing Loan Estimates, make sure you use the same loan amount, term, and renovation budget for each one. Look at the interest rate, points, fees, mortgage insurance, total monthly payment, and the estimated cash you’ll need to close. Remember, a lower down payment doesn’t always mean you’re getting the best deal overall.
FHA 203(k) Credit Score Requirements
HUD’s current 203(k) calculation allows a maximum LTV of 96.5% with a minimum decision credit score of 580 or higher.
For borrowers with scores from 500 through 579, the maximum LTV is generally 90%, which means a larger minimum investment.
These are HUD limits, not a guarantee that every FHA 203(k) lender will approve those scores.
FHA 203(k) Guidelines vs. Lender Overlays
HUD sets the FHA program requirements; individual lenders can impose their own overlays (restrictions), and these overlays can affect credit score, debt-to-income ratio, reserves, property type, contractor qualifications, and acceptable renovation types. When reviewing an eligibility requirement, ask whether it comes from HUD or the lender providing the financing. Also check that the lender in question offers the Limited 203(k), the Standard 203(k), and any underwriting approach your application may require. An FHA program minimum in no way guarantees approval or availability of the product. It’s absolutely essential to review the borrower’s qualifications and project eligibility at an early stage so that any restrictions are identified before the buyer invests any money in detailed renovation plans.
How Your Debt-to-Income Ratio Is Evaluated
Your debt-to-income ratio (DTI) shows how your proposed housing payment and other monthly debts compare to your gross monthly income. The housing payment covers principal, interest, property taxes, homeowners insurance, FHA mortgage insurance, and any association dues. For example, if your total monthly debts are $3,600 and your qualifying income is $8,000, your DTI would be 45%. FHA’s TOTAL Mortgage Scorecard uses an automated system to review your application. It gives it either an Accept or Refer decision. If you get an Accept, you still need to verify your information and meet all requirements. A Refer means your application will go through manual underwriting. Sometimes, even if you get an Accept at first, your application may still require manual review. Manual underwriting follows FHA’s specific rules for ratios and documentation, but it does not always allow a higher DTI. If you qualify, certain compensating factors like having cash reserves, only a small increase in your housing payment, or enough leftover income each month can help you get approved for a higher DTI, as long as it fits within FHA’s manual underwriting limits. Check with your lender to confirm they offer manual underwriting for your 203(k) loan, and ask about any additional requirements. For more details on ratio limits and documentation, refer to the FHA Manual Underwriting Mortgage Guidelines.
Eligible California Properties for FHA 203(k) Financing
Eligible existing structures generally must have been completed for at least one year before FHA case-number assignment. The lender may request a Certificate of Occupancy or equivalent documentation to verify the completion date. California FHA 203(k) loans can be used for more than just a traditional detached single-family home. Eligible properties can include one-unit homes, qualifying two- to four-unit properties, townhomes, certain manufactured homes titled as real estate, eligible condominium and site-condominium units, HUD-owned properties, and qualifying mixed-use properties that are primarily residential.
FHA 203(k) Is for Owner-Occupied Property
The borrower must meet FHA’s occupancy requirements. A 203(k) should not be confused with a fix-and-flip or investor renovation loan. It is primarily intended to help eligible owner-occupants purchase or refinance residential property that needs rehabilitation.
Condominiums Have Additional Restrictions
An eligible condominium unit can use 203(k) financing, but rehabilitation is generally limited to the interior of the individual unit. The project and unit must also satisfy the applicable FHA condominium requirements.
What Repairs and Improvements Can Be Financed?
The FHA 203(k) program can cover a wide range of repairs when the work improves, modernizes, or makes the property safer and more functional. Typical eligible projects can include kitchens, bathrooms, roofing, plumbing, electrical systems, HVAC, flooring, painting, energy-efficiency improvements, accessibility improvements, driveways, walkways, fences, decks, patios, porches, and eligible appliances. HUD also permits certain lead-based paint stabilization work and the repair or removal of an existing in-ground swimming pool.
Structural Work Requires the Right 203(k)
Structural repairs and major remodeling can be financed through the Standard 203(k) when they meet FHA requirements. The Limited 203(k) is restricted to non-structural work. That distinction should be determined before the borrower chooses the loan type and before contractor bids are finalized.
Work Must Meet Building Requirements
Renovations must comply with the FHA Minimum Property Requirements and meet or exceed applicable local building codes. California projects may also require city or county permits depending on the work being completed.
Repairs That Cannot Be Financed With an FHA 203(k)
FHA 203(k) proceeds cannot be used simply for any improvement the borrower wants. HUD does not permit financing for luxury items, improvements that do not become a permanent part of the property, or work that solely benefits a commercial use within the property. For example, installing a new luxury recreational feature should not be treated the same as repairing an existing property component.
Limited 203(k) Has Additional Restrictions
The Limited 203(k) cannot be used for major rehabilitation or structural remodeling. Under current FHA rules, work is too extensive for the Limited program when, among other things, it is expected to take more than nine months, requires architectural plans or a consultant-prepared work write-up, requires more than four draws per contractor, or prevents the borrower from occupying the home for more than a total of 30 days during rehabilitation. A project that exceeds the Limited program’s scope may still qualify under the Standard 203(k).
FHA 203(k) Contingency Reserves
A contingency reserve sets aside money for unexpected rehabilitation expenses, such as concealed damage discovered after work begins. Whether FHA requires this reserve depends on the program and the property’s age and condition.
For a Standard 203(k), properties at least thirty years old generally require a reserve of at least 10% of financeable repair and improvement costs. That minimum increases to 15% when utilities are not operable as identified in the consultant’s work write-up. For properties under thirty years old, reserves are generally discretionary unless there is evidence of termite damage, which requires a minimum 10% reserve. The financeable reserve cannot exceed 20% of financeable repair and improvement costs.
For a Limited 203(k), FHA does not mandate a contingency reserve, but the lender may establish one. Any financed reserve counts toward the program’s $75,000 total rehabilitation limit, reducing the amount available for contractor work and other eligible financed expenses. For example, a 10% reserve on $50,000 in financeable repair and improvement costs equals $5,000; a 15% reserve equals $7,500. Include the applicable reserve and fees when reviewing the project budget so the contractor’s estimate leaves enough room for those expenses.
Renovation Timelines, Occupancy Rules, and Contractor Payments
The approved rehabilitation agreement establishes your project’s completion deadline. Under HUD Mortgagee Letter 2024-13, FHA permits rehabilitation periods of up to 9 months for Limited 203(k) and 12 months for Standard 203(k) for case numbers assigned on or after November 4, 2024. Your agreement may establish a shorter deadline based on the approved work. Limited projects won’t stop the borrower from occupying the property for more than 30 days in the aggregate during the rehabilitation period. Standard financing can cover a much broader range of work which would leave the home uninhabitable. An eligible Standard transaction may include financed mortgage payment reserves for the approved period of uninhabitation (subject to a 12-month maximum and the rehabilitation agreement). Renovation funds are held in a rehabilitation escrow account. Contractor payments are made in accordance with the approved draw schedule, the applicable inspection requirements, and the initial disbursement rules. For Standard 203(k), the FHA allows up to five draw requests (four intermediate and one final). Each draw may consist of multiple disbursements. The Limited 203(k) allows up to four draws per contractor under HUD’s June 23, 2026 update. The lender must disburse funds within 5 business days after receiving a properly completed draw request and any necessary title update. Before you go final on it, make sure the contractor can work to the payment schedule and completion date. You need to factor in permits, inspections, material availability, and any temporary accommodation that might be required to assess whether the schedule is viable.
California FHA 203(k) Mortgage Example
Imagine a one-unit home purchase in LA County. Adjusted as-is value is $600k, total eligible rehab (including financed fees and reserves) is $70k, and the after-rehab appraised value is $720k. The borrower is eligible for 96.5% financing, and the rehab complies with the program requirements.
First, the as-is value adjusted (i.e., 600k)plus the eligible rehab costs(70k) = 670k. Then, 110% of the after-improvement value(720k x 1.10 = $792k). FHA takes the lower of the two: $670k.
Applying 96.5% financing gives you a 646,550basemortgage(670k x 0.965). That leaves a borrower contribution of $23,450 towards the acquisition and rehabilitation costs. The base mortgage is also within Los Angeles County’s 2026 one-unit FHA limit of $1,249,125. A property in a county with a lower limit would require a larger contribution. The $23,450 is just one component of the cash-to-close calculation. Closing costs, prepaid expenses, and other expenses paid at closing will add to that amount, whilst deposits already paid and permitted credits will reduce the amount due. Any financed upfront mortgage insurance premium is added separately to the base mortgage to establish the total mortgage amount.
Choosing a Contractor and Preparing Your California 203(k) Project
Before you make an offer, you need to establish the property’s major repair requirements and, where possible, obtain preliminary costings. You need to allow sufficient time in the purchase contract for the contractor to review the work, for the renovation documentation to be prepared, and for the appraisal to be carried out. Use the California Contractors State License Board’s license lookup to check the contractor’s license status and business details. Review the available complaint disclosures and ask for references for similar renovation work. The written contract should specify the work, materials, equipment, price, payment schedule, and expected start and finish dates. It should state who is responsible for obtaining the required permits (and whether permit fees are included) and who will coordinate the inspections. The CSLB Homeowner Checklist includes some very useful questions to review before signing. Have the mortgage team go through the contractor’s proposed payment schedule against the approved 203(k) draw process. The final bids should be in line with the approved repair scope and, for Standard financing, the consultant’s work write-up. Any contractor replacements or scope changes will in principle require new documentation and lender approval.
Hypothetical California Example: Structural Repairs Change the Loan Choice
Imagine a buyer looking at an older home in Fresno with the intention of just replacing the flooring, paint, and HVAC. The inspection then reveals a damaged load-bearing beam that would require structural repair. That project would be a Standard rather than a Limited 203(k), even if the total rehab costs were still under $75k. Identifying that issue early gives the buyer time to secure the required consultant review and revise the contractor’s bid, the financing, and the completion schedule before closing.
FAQs About California FHA 203(k) Loans
Can I Complete Some of the Renovation Work Myself?
Possibly, if the lender approves and you meet FHA’s self-help requirements. You cannot be reimbursed for your own labor. Any reimbursement for materials must comply with the approved rehabilitation agreement and escrow procedures.
Can I Change Contractors After Closing?
A replacement contractor requires lender review and approval. Notify your mortgage team before arranging the change so revised bids, agreements, payment arrangements, and completion deadlines can be reviewed.
What Happens if Renovation Costs Exceed the Budget?
Approved contingency funds may cover eligible unexpected expenses. If those funds are insufficient, you may need additional acceptable funds or an approved scope adjustment. Required repairs must still be completed.
What Happens to Unused Contingency Funds?
For Standard 203(k), unused financed reserves may pay for approved additional improvements or reduce principal. For Limited 203(k), they must reduce principal. Unused reserves you contributed personally may be refunded or applied toward principal after project closeout.
Can I Finance a Home that is Uninhabitable at Closing?
An eligible property may qualify for a Standard 203(k) loan with an approved rehabilitation plan. Mortgage-payment reserves may also be available. Limited projects cannot prevent occupancy for more than thirty days in total during rehabilitation.
Final Thoughts on California FHA 203(k) Loans
A viable California FHA 203(k) project is one in which the property, the scope of repairs, the supported value, and the available financing all work in concert. You need to make sure the approved budget will cover the work, fees, and reserves, and that the contractor is capable of meeting the completion schedule. Your monthly payment and your out-of-pocket cash commitment should be something you can live with throughout the renovation. Before you go any further, you need to have the itemized repair estimates, the contractor’s license and contact details, and any known permit requirements. Check the county FHA loan limit and get a written breakdown of the financed costs and the expected cash-to-close. Factor in temporary accommodation and any other unforeseen costs when assessing whether the project is within your budget.
This article about “California FHA 203(k) Loans: Requirements, Limits, and Renovation Rules” was updated on October 20th, 2026.