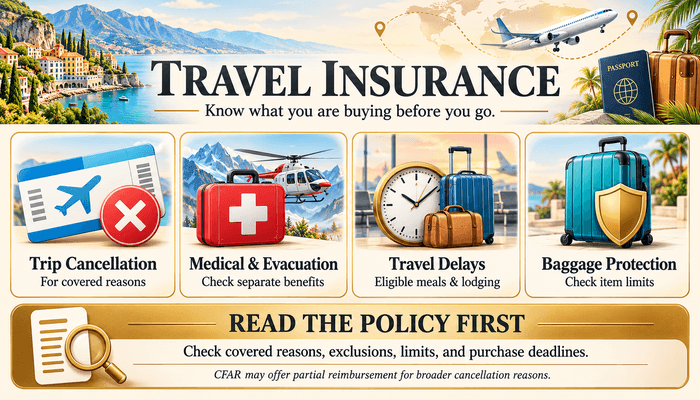
Travel insurance can help cover eligible losses if an unforeseen event disrupts your trip. The benefits available will vary by policy and may include trip cancellation, emergency medical treatment, evacuation, travel delay, and lost luggage. The amount of cover available will depend on the reason for the loss, the policy limits and the policy exclusions. Prior to purchasing, you should establish what you could lose and check what cover you already have via your health insurance, credit card, and so on.
What Does Travel Insurance Cover?
Travel insurance describes several types of protection. A package may combine benefits, while another plan may focus on medical care or a particular trip. Read the actual policy or certificate of insurance to see which benefits are included.
Trip Cancellation and Interruption
Trip cancellation coverage may reimburse eligible prepaid, nonrefundable expenses when you cancel before departure for a reason listed in the policy. Trip interruption coverage may help when a covered event forces you to end a trip early or changes part of your itinerary. For example, a serious unexpected illness may qualify, but simply deciding that you would rather stay home usually does not qualify under standard cancellation coverage. The insurer may require medical records or other evidence. Allianz Partners’ cancellation guidance explains why both the covered reason and the nonrefundable costs matter.
Emergency Medical Care and Evacuation
Travel medical insurance may help cover treatment costs if you become sick or injured while traveling. Your regular health insurance may offer limited overseas benefits, so check with your insurer before departure. Medical evacuation is a separate benefit that may cover transportation to an appropriate medical facility. Do not assume it guarantees transportation to your preferred hospital or home. The CDC’s travel insurance guidance explains the differences between cancellation, medical, and evacuation protection.
Travel Delays and Baggage
Delay benefits may reimburse eligible meals, lodging, or other expenses after a qualifying disruption. Baggage benefits may cover certain losses or essential purchases when luggage is delayed. Check the required delay period, covered causes, daily limits, and restrictions on individual items. Keep receipts and any written confirmation from the airline.
What Does Travel Insurance Usually Exclude?
A policy’s exclusions can be as important as its advertised benefits. Look for restrictions related to known events, pre-existing medical conditions, high-risk activities, and losses that do not qualify as covered reasons.
Pregnancy, mental health emergencies, terrorism, war, and disease outbreaks can have specific provisions. Do not assume that a general description of emergency coverage answers those questions. Ask the insurer to identify the provision that applies to your concern.
The Washington Office of the Insurance Commissioner’s buying guidance recommends reviewing exclusions, existing protection, health conditions, and outbreak or disaster coverage before purchasing.
Choose Travel Coverage That Fits Your Plan
Understand common policy limits and exclusions so you can make a more informed coverage decision.How Much Does Travel Insurance Cost?
The National Association of Insurance Commissioners’ consumer guide says policies usually cost about 5% to 10% of the trip price. Actual premiums vary with the coverage, travelers, destination, and other pricing factors. For a hypothetical $6,000 trip, that reference range would equal $300 to $600. It is a budgeting example, not a quote. Compare plans using the same travelers, dates, trip costs, and benefits. A lower premium may come with lower limits or fewer covered situations.
Standard Cancellation Coverage vs. Cancel For Any Reason
Standard trip cancellation insurance only covers reasons listed in your contract. Cancel For Any Reason, or CFAR, is an optional add-on with some plans that lets you cancel for more reasons. According to the NAIC’s travel insurance overview, CFAR usually pays back only part of your eligible costs, often between 50% and 75%. You usually need to buy it soon after booking, cover all your trip costs, and cancel a certain number of days before you leave. The details and availability depend on the plan and where you live. For example, if you cancel a $4,000 trip and your CFAR benefit covers 75%, you would get $3,000 back before any other adjustments. CFAR does not guarantee a full refund.
Travel Insurance and Pre-Existing Medical Conditions
A pre-existing condition exclusion could impact claims relating to a prior medical condition. The policy will define which conditions are covered, the time period in question, and how the exclusion applies to various benefits.
Some plans will in fact provide a waiver of that exclusion if certain conditions are met. The conditions may be that you buy within a certain period after the initial trip payment, that you insure the required trip costs, and that you are medically fit to travel at the time of purchase.
Travel Guard’s waiver explanation is a case in point. Other products will of course vary. A waiver will remove a particular exclusion; it won’t remove all exclusions or all guarantees in respect of all medical claims. New conditions will be assessed differently from pre-existing conditions under the policy.
When Should You Buy Travel Insurance?
Review insurance options when you make your first trip payment. Waiting can mean missing a deadline for time-sensitive benefits or finding that an event you want protection against has already become foreseeable. For example, buying after a storm has been named may result in related losses being excluded from coverage. The NAIC’s travel-planning guidance discusses this issue. Check when each benefit takes effect, and ask how to report additional trip payments or itinerary changes.
How to Compare Travel Insurance Policies
Begin by thinking about the financial risks for your trip. Add up any prepaid costs you would lose if you had to cancel and couldn’t get a refund. Next, consider your access to medical care, possible evacuation plans, planned activities, and who is traveling with you.
Look at the benefit limits, deductibles, reasons for cancellation that are covered, exclusions, and what you need to do to file a claim. Find out if medical benefits pay you directly or if you have to go through another insurer first. Also, see if emergency transport needs to be arranged or approved by the insurer.
Check what coverage you already have. Credit card travel benefits may require you to pay for your trip with the card and often have limits. Your homeowners or renters insurance could cover some belongings while you travel, but pay attention to deductibles and restrictions. The CDC Yellow Book’s insurance chapter lists questions to ask about overseas medical care, payment, exclusions, and help services.
How to File a Travel Insurance Claim
Get in touch with the insurer or claims administrator as soon as possible and be sure to adhere to the notification and filing deadlines in your policy. If it’s a cancellation then you should also get in touch with the travel supplier as soon as possible to effect the cancellation and to find out what, if any, refund is available. Document what happened, when it happened and the amount you are claiming. Depending on the loss the supporting documentation may be your booking confirmation, your receipt, your cancellation notice, medical records, an airline report or a police report. You must clearly state any refund you have already received and the amount of the loss which is still outstanding. Allianz Partners’ claims guidance is simply the information that an insurer might ask for. Your own insurer’s instructions will of course govern your submission. You must keep copies, you must keep the claim number and you must respond to any requests for further records. The time it takes to process a claim will vary from claim to claim depending on the amount of review required. Filing a claim does not guarantee payment. If your claim is denied you will need to request the written explanation and you should then review the relevant policy language and the options available to you in relation to a reconsideration.
Frequently Asked Questions About Travel Insurance
Is Travel Insurance Required for International Travel?
Requirements depend on the destination and visa involved. Some require proof of qualifying medical insurance. Check the destination government’s current requirements and any visa conditions before departure. An airline’s insurance offer does not establish what the destination requires.
Does Travel Insurance Cover COVID-19 or Another Disease Outbreak?
Read the specific provisions. Benefits for a covered illness can differ from benefits for fear of traveling, an outbreak, quarantine, or entry restrictions. Ask the insurer about the exact situation you want covered rather than relying on a general pandemic coverage label.
Can I Buy Travel Insurance After My Trip Starts?
Check eligibility directly with the provider. Do not assume a plan can be purchased after departure or that it will cover an event that has already happened. Ask about effective dates, waiting periods, and benefits that are no longer available.
Can Travel Insurance Cover a Cruise?
Some policies provide benefits relevant to cruises, but verify the provisions for onboard medical treatment, missed departure, interruption, and evacuation. Having access to a ship’s medical staff does not establish that treatment is included in your fare or covered by your insurance.
Do I Need Separate Insurance If My Credit Card Offers Travel Benefits?
Look at what your card covers and see if it matches your needs. Find out who is included, which purchases count, and what the limits are for medical, cancellation, and baggage claims. You might need extra insurance if your card doesn’t cover everything, especially for medical care or evacuation abroad.
Will Travel Insurance Pay for Skiing, Diving, or Other Adventure Activities?
What’s covered depends on the activity and the details of your policy. Check if your plan includes the activity you want to do, or if you need extra coverage. Make sure you’re protected for both medical care and evacuation.
Final Thoughts on Travel Insurance
Travel insurance is only going to be of any use if the benefits of it match the losses you could potentially incur. A person on a short, refundable trip will have very different requirements from a family with several substantial non-refundable bookings or someone going to a very remote destination. It’s important to compare those risks against the level of cover that you have. Before you buy, read the covered reasons, the exclusions, the limits, and the time-sensitive requirements. Keep your policy and assistance information, as well as your payment records, to hand throughout your trip. Knowing all that beforehand makes it far easier to select the right cover and to document a loss should anything happen.
This article about “Travel Insurance: What It Covers, Costs, and Common Exclusions” was updated on October 26th, 2026.