In this guide, we will cover and discuss the statute of limitations on collection accounts and charge-offs. We will go into detail on how older collection accounts affect qualifying for a mortgage. The Great Recession of 2008 has affected the financial lives of many Americans in this country as well as globally.
During the Financial Crisis of 2008, hard-working Americans not only lost their jobs and businesses, but homeowners lost equity in their homes. Many lost their homes to foreclosure.
Countless Americans also lost their retirements and businesses. Never before in history have so many hard-working Americans filed for bankruptcy and lost their homes to foreclosure. For those who did not file for bankruptcy protection, their credit has suffered. Many ended up with judgments, collections, and charge-offs that remain on their credit reports today.
Qualifying for FHA Loans With Collections and Charge-Off Accounts
Homebuyers can qualify for FHA loans with outstanding collections and charge-off accounts. FHA Guidelines on Collections do not require homebuyers to pay outstanding collections and charge-off accounts to qualify. Borrowers can have outstanding collections, charge-offs, judgments, and tax liens and still qualify for FHA Loans. With tax liens and judgments, borrowers need to get a written payment agreement. Borrowers need to make three monthly payments. Medical collections are exempt from debt-to-income ratio calculations.
Statute of Limitations on Collection Accounts: Credit Report and Mortgage Guide

Old collection accounts can cause a lot of confusion especially when someone is trying to improve their credit or get a mortgage. People often ask if an old debt can still be collected, if it should still show up on a credit report and if unpaid collections need to be paid before getting approved for a home loan.
Those questions involve different rules. The statute of limitations on collection accounts generally determines how long a creditor or debt collector has to sue over a debt.
This is different from how long negative information can stay on a credit report. It is also different from how FHA, VA and conventional mortgage rules handle collection accounts. Understanding those differences can help people avoid making payments making credit mistakes and facing delays when applying for a home loan.
What Is the Statute of Limitations on Collection Accounts?
The statute of limitations on collection accounts is generally the legal time period during which a creditor or debt collector can take action to collect an unpaid debt. Once the specific statute of limitations ends the debt may become time-barred. That does not mean the debt disappears. It usually means a debt collector can no longer legally sue or threaten to sue to collect the debt if the time period has ended.
How Long is the Statute of Limitations on Collection Accounts?
The exact time depends on state law, the type of debt and sometimes the terms of the agreement. There is no national rule that applies to all consumer debts. With nonmedical collections, here is how it works:
How Non-Medical Collection Accounts Can Impact Your Mortgage Loan Eligibility
Borrowers do not have to pay off nonmedical collections. However, if applicants have $2,000 or more in outstanding nonmedical collection accounts here is how it works: Then 5% of the outstanding balance is used as if it were a monthly debt of the borrower. This holds true even though they do not have to pay. If 5% of the outstanding collection accounts is too much for the home buyer to qualify, the mortgage applicant can make a written payment agreement with the collection agency on a monthly repayment plan: That figure will be used in lieu of the 5% of the outstanding collection amount. Charge-off accounts are exempt from debt to income ratio calculations.
Types of Contracts
Below are the State Statutes of Limitations on Collection Accounts for various kinds of agreements. All figures are in years.
Oral Contracts:
- Oral contracts are when consumers verbally agree to pay back the money that is loaned to them.
- However, oral contacts are very difficult to prove in court.
Written Contract:
- Written contracts are when an agreement between creditor and debtor and the terms, or rewritten and signed by both parties.
Promissory Note:
Promissory notes are a special form of a written contract. But the difference with a promissory note is that the scheduled payments. The interest on the loan is written out on the promissory note. Why should you care about the Statute of Limitations On Collection Accounts (SOL).
Statute of Limitations on Collection Accounts
Below is a Chart on the Statute of Limitation on Collection Accounts:
| State | Oral | Written | Promissory | Open-ended Accounts | State Statute: Open Accounts |
| AL | 6 | 3 | 6 | 3 | §6.2.37 |
| AR | 3 | 5 | 3 | 5 | §4-3-118 |
| AK | 6 | 3 | 3 | 3 | §09.10.053 |
| AZ | 3 | 6 | 6 | 6 | HB 2412 |
| CA | 2 | 4 | 4 | 4 | §337 |
| CO | 6 | 6 | 6 | 6 | §13-80-103.5 |
| CT | 3 | 6 | 6 | 6 | Chapter 926 Sec 52-576 |
| DE | 3 | 3 | 3 | 3 | Title 10 Sec.8106 |
| DC | 3 | 3 | 3 | 3 | §12-301 |
| FL | 4 | 5 | 5 | 4 | §95.11 |
| GA | 4 | 6 | 6 | 4** | §9-3-25 |
| HI | 6 | 6 | 6 | 6 | HRS 657-1(4) |
| IA | 5 | 10 | 5 | 10 | §614.1.5 |
| ID | 4 | 5 | 5 | 5 | §5-216 |
| IL | 5 | 10 | 10 | 5 or 10*** | 735 ILCS 5/13-206 |
| IN | 6 | 10 | 10 | 6 | §34-11-2-9 |
| KS | 3 | 3 | 3 | 3 | §60-512 |
| KY | 5 | 15 | 15 | 5 or 15 | §413.120 & 413.090 |
| LA | 10 | 3 | 10 | 3 | §2-3494-4 |
| ME | 6 | 6 | 6 | 6 | §14-205-752 |
| MD | 3 | 3 | 6 | 3 | §5-101 |
| MA | 6 | 6 | 6 | 6 | §260-2 |
| MI | 6 | 6 | 6 | 6 | §600.5807.8 |
| MN | 6 | 6 | 6 | 6 | §541.05 |
| MO | 5 | 5 | 5 | 5 | §516.120 |
| MS | 3 | 3 | 3 | 3 | §15-1-29 |
| MT | 5 | 8 | 8 | 8 | 27-2-202 |
| NC | 3 | 3 | 5 | 3 | §1-52.1 |
| ND | 6 | 6 | 6 | 6 | 28-01-16 |
| NE | 4 | 4 | 4 | 4 | §25-206 |
| NH | 3 | 3 | 3 | 3 | 382-A:3-118 |
| NJ | 6 | 6 | 6 | 6 | 2A:14-1 |
| NM | 4 | 4 | 4 | 4 | §37-1-4 |
| NV | 4 | 4 | 4 | 4 | NRS 11.190 |
| NY | 6 | 6 | 6 | 6 | §2-213 |
| OH | 6 | 6 | 6 | 6 | §2305.07 |
| OK | 3 | 3 or 5 | 5 | 3 or 5 | §12-95A(1), (2) |
| OR | 6 | 6 | 6 | 6 | §12.08 |
| PA | 4 | 4 | 4 | 4 | 42 Pa. C.S.5525(a) |
| RI | 10 | 10 | 10 | 10 | §6A-2-725 |
| SC | 10 | 10 | 3 | 3 | SEC 15-3-530 |
| SD | 3 | 6 | 6 | 6 | §15-2-13 |
| TN | 6 | 6 | 6 | 6 | 28-3-109 |
| TX | 4 | 4 | 4 | 4 | §16.004 |
| UT | 4 | 6 | 6 | 4 | 78-12-25 |
| VA | 3 | 5 | 6 | 3 | 8.01-246 |
| VT | 6 | 6 | 5 | 6 | §9A-3-118 |
| WA | 3 | 6 | 6 | 6 | 4.16.040 |
| WI | 6 | 6 | 10 | 6 | 893.43 |
| WV | 10 | 10 | 10 | 10 | §55-2-6 |
| WY | 8 | 10 | 10 | 8 | §1-3-105 |
Statute of Limitations versus the Seven-Year Credit Reporting Rule
One of the mistakes people make is thinking the statute of limitations and the credit-reporting period are the same. They are not.
The Statute of Limitations Deals With Lawsuits
The statute of limitations usually decides how long a creditor or collector can use the court system to collect a debt. Depending on the state and the type of debt that period may be years.
Credit Reporting Uses a Separate Timeline
Most negative information on a consumer credit report generally remains for about 7 years. That means a collection could become time-barred before it falls off a credit report. It also means a debt disappearing from a credit report does not necessarily prove that the underlying obligation no longer exists.
- Think of these as separate clocks.
- One clock concerns legal action.
- Another concern is credit reporting.
- A third set of rules becomes relevant when you apply for a mortgage.
When Does the Statute of Limitations Begin?
The answer depends on applicable state law. For many consumer debts, the timeline may be connected to the date of default, the first missed payment, the last payment, or another event defined under state law.
A Credit Report Can Show Several Different Dates Associated with One Account, Including:
- The date the account was opened.
- The date of the first missed payment.
- The charge-off date.
- The date the collection agency acquired the account; and
- The date of the most recent payment.
-
These dates do not mean the thing.
- If a collection account is old and there is worry about action people should consider talking to an attorney who knows their states debt collection laws.
Can Paying an Old Collection Restart the Statute of Limitations?
In some states yes. This is one reason people should be careful about making a payment on an old debt whether a collector calls or they are getting ready to apply for a mortgage.
Depending on state law making a payment or saying something about an old debt may restart the time period. That does not mean people should never pay an account.
It means they should know the results first. Before paying an old collection, especially one that may already be time-barred it may be a good idea to talk to both a qualified attorney and a mortgage expert.
Can a Debt Collector Sue After the Statute of Limitations Ends?
A debt collector usually cannot legally. Threaten to sue about a debt that is past the statute of limitations. However people should never ignore court papers. If you get a notice or a lawsuit about a collection account respond quickly and get legal help. Even if a debt is outside the statute of limitations that defense usually has to be used. Ignoring the lawsuit can cause problems.
Does a Collection Account Go Away After Seven Years?
Bad credit information usually stays on a credit report for about seven years. That does not mean a debt buyer can start the reporting period over every time the account is sold. Transferring a debt does not start a seven-year period for the original problem. People who think a collection has been wrongly updated or has wrong dates can challenge the information with the credit bureaus.
Do Collection Accounts Need to Be Paid Before Getting a Mortgage?
Not always. This is one of the important things for people getting a mortgage. A collection on a credit report does not mean it has to be paid before closing. The right answer depends on the loan type the amount of the collection the kind of property the debt-, to-income ratio, computer underwriting results and overall credit history.
Statute of Limitations on Collection Accounts and Bad Credit Explained
Don’t let guesswork decide your next move with collectors or lendersFHA Loans and Collection Accounts
FHA does not automatically require every collection account to be paid. When qualifying nonmedical collections have a cumulative outstanding balance of $2,000 or more, the lender generally must address the collections.
Depending on the Circumstances, the Lender May Use:
- An established payment arrangement.
- Verified payoff of the collection; or
- A calculated monthly obligation based on the outstanding balance.
This can make a major difference for borrowers who assumed they had to pay thousands of dollars before applying.
VA Loans and Collection Accounts
VA underwriting also does not automatically require every collection to be paid. Collection accounts are reviewed as part of the borrower’s overall credit profile. VA lenders may consider factors such as:
- Recent payment history;
- Whether the collections are medical or nonmedical;
- Outstanding collection balances;
- Residual income;
- Debt-to-income ratio; and
- Whether the borrower has re-established satisfactory credit.
- VA underwriting focuses heavily on the overall credit pattern rather than on one isolated account.
Conventional Loans and Unpaid Collections
Conventional financing can also be more flexible than many borrowers think. Under Fannie Mae automated underwriting guidance certain unpaid non-mortgage collection accounts and charge-offs may not need to be paid when financing a one-unit residence. Different rules may apply to homes, investment properties, multi-unit properties, judgments, liens and past-due accounts that are not classified as collections. The main idea is simple: Do not think every collection must be paid before getting preapproved.
Statute of Limitations Does Not Override Mortgage Guidelines
A debt being time-barred does not automatically mean a mortgage lender must ignore it. The statute of limitations deals primarily with legal collection activity. Mortgage underwriting addresses the borrower’s credit risk and loan program requirements. Those are separate issues. An old collection can be outside the statute of limitations and still appear on a credit report. If the account remains on the report, the lender may still need to evaluate it according to FHA, VA, conventional, or other underwriting rules.
Collection Accounts Versus Judgments
- A collection account and a judgment are not the same thing.
- A collection is generally an unpaid debt being pursued for payment.
- A judgment results from legal action and a court decision.
- Judgments may create additional issues involving liens, garnishments, property rights, and mortgage underwriting requirements.
- Borrowers with outstanding judgments should inform their loan officer early in the mortgage process.
- Waiting until underwriting discovers the judgment can create unnecessary delays.
Should You Pay Old Collections Before Applying for a Mortgage?
Not automatically. One of the most common mistakes borrowers make is trying to clean up their credit before having the mortgage file reviewed. They may pay old collections, close accounts, open new credit, dispute accounts, or drain savings needed for the down payment and closing costs.
- Sometimes paying a collection is the right move.
- Sometimes it is unnecessary.
- Sometimes a payment arrangement may be sufficient.
- Sometimes paying the debt can take away funds that would have been better used as reserves.
- The best way is to look at the mortgage profile before making big changes to credit.
Will Paying a Collection Increase Your Credit Score?
It could, There is no promise. The impact depends on the scoring model, how old the collection’s the overall credit history and how the account is reported. Mortgage lenders might use credit scoring models that’re different from the scores people get through free credit-monitoring services. Borrowers should not think that paying one collection will definitely lead to a jump in their credit score. A better strategy is to review the entire credit profile and determine which actions are most likely to improve mortgage eligibility.
What If the Collection Is Not Yours?
Do not pay a collection just because it appears on your credit report. Credit reports can contain errors. An account might belong to someone with a name could be from identity theft show the wrong amount or report wrong dates. If a collection is not yours. Has wrong details use the official credit-dispute process and include any proof you have.
Collection Accounts and Manual Underwriting
Borrowers with collections may still qualify through manual underwriting. Manual underwriting involves a more detailed review of the borrower’s complete credit history.
The Underwriter May Ask:
- Was the collection caused by a one-time hardship?
- Was it related to a medical emergency?
- Did the borrower experience unemployment or loss of income?
- Has the borrower established good credit since the event?
- Is the borrower current on housing payments and other obligations?
The aim is to find out if the collection shows a one-time issue or a continuing pattern of not paying debts. That is why borrowers with credit histories may do better by working with a mortgage professional who has experience, with manual underwriting.
Start Date of Statute of Limitations on Collection Accounts
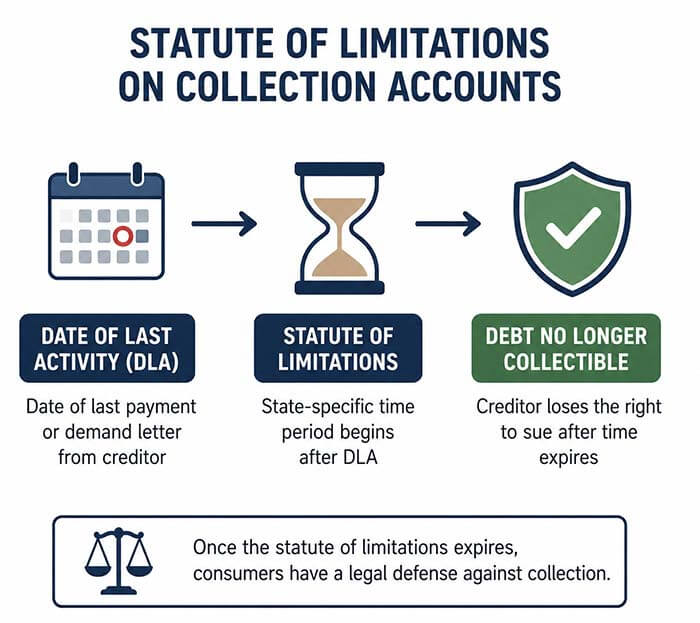 Statute of Limitations on Collection Accounts is a set amount of time by law if the creditor does not do anything to collect the debt owed by the debtor, the debt owed is no longer collectible. There is a start date when the statute of limitations on collection accounts starts. Here is the start date:
Date of Last Activity or DLA
This date is the date that debtors failed to make a payment on their credit account. This is the date that the creditor sent the consumer a demand letter for the full amount of payment. In the event, if creditors do not go after the consumer in a time frame permitted by law, consumers do have the right of defense against the creditor.
The Creditor Can No Longer Come After Them Due to the Elapse of the Statute of Limitations on Collection Accounts:
- Consumers should take the date of the last activity.
- This is the date of the last payment made by the consumer or the date of payment demand letter by the creditor.
- Then add the time that has elapsed by the statute of limitations on collection accounts in the state the debtor defaulted.
Case Scenario on Statute of Limitations on Collection Accounts
Case Scenario:
The consumer’s date of last activity on credit card payment was January 15, 2001. The credit card company sent a demand letter for full payment on July 15, 2001. There is a 6-year statute of limitations on credit cards.
The Statute of Limitations on Credit Cards
Consumers with collections and charge-off accounts can still qualify for FHA Loans. Homebuyers with collections and charge-offs do not have to pay off collections and/or charge off accounts. For information contact us at Gustan Cho Associates Mortgage Group at 800-900-8569 or text us for a faster response. Email us at gcho@gustancho.com.
Frequently Asked Questions About the Statute of Limitations on Collection Accounts
Is the Statute of Limitations Always Seven Years?
No. Seven years is commonly associated with credit reporting, not necessarily with the deadline for filing a collection lawsuit.
Does a Debt Disappear After the Statute of Limitations Expires?
No. The debt may still exist even if legal action to collect it is limited.
Do Collections Have to be Paid for an FHA Loan?
Not always. FHA has specific guidelines for how certain collection balances are handled.
Can I Qualify for a Mortgage with Unpaid Collections?
Yes, depending on the loan program, collection type, amount owed, credit history, and underwriting findings.
Should I Pay Collections Before Getting Preapproved?
Not without first reviewing the mortgage file. Paying unnecessary collections can reduce funds available for closing and may not improve qualification.
Final Thoughts on the Statute of Limitations on Collection Accounts
The statute of limitations on collection accounts is only one part of understanding old debt.
Borrowers Should Separate the Three Issues:
- How long a creditor has to sue.
- How long can the account remain on a credit report?
- How the mortgage lender must treat the collection.
- Those timelines do not always match.
- An old collection does not automatically prevent someone from becoming a homeowner.
- An unpaid collection does not always have to be paid before closing.
Before paying, settling, disputing, or establishing payment arrangements on old collections, have the entire credit and mortgage profile reviewed. Gustan Cho Associates works with borrowers who have collection accounts, charge-offs, lower credit scores, bankruptcies, foreclosures, manual underwriting scenarios, and other complex credit situations.
The goal is not simply to remove every negative item from a credit report. The goal is to determine the most effective path toward mortgage qualification based on the borrower’s actual loan program and financial circumstances.
This article is for general educational purposes only and should not be considered legal advice. Statutes of limitations and debt-collection laws vary by state. Consumers facing a lawsuit or potentially time-barred debt should consult a qualified attorney.