Credit Score Mortgage Guidelines for FHA, VA, USDA, and Conventional Loans
This guide covers credit score mortgage guidelines for FHA, VA, USDA, and conventional loans. There is no universal minimum credit score required to buy a house. The required credit score for a mortgage depends on loan type, down payment, automated underwriting results, overall credit history, lender requirements, and sometimes property occupancy or transaction type.
Learn credit score mortgage guidelines for FHA, VA, USDA, and conventional loans, including minimum scores, bad credit, and lender overlays.
For example, a borrower with a 580 credit score may not qualify for some conventional programs but could be eligible for an FHA loan. A veteran with the same score may qualify for a VA loan, as the Department of Veterans Affairs does not set a minimum credit score. A 620 credit score may provide more conventional loan options, while higher scores often result in better pricing and a broader selection of programs.
What Credit Score Do You Need to Buy a House?
The Consumer Financial Protection Bureau states that higher credit scores generally improve qualification chances and can lead to better mortgage rates and terms. Lenders do not approve or deny loans based solely on a credit score.
Underwriters also consider income, employment history, debt-to-income ratio, housing payment history, assets, reserves, down payment, recent late payments, collections, charge-offs, bankruptcy, foreclosure, and other risk factors.
Automated underwriting systems may assess the entire application differently than a lender focused only on credit score. As a result, two borrowers with the same credit score may receive different underwriting outcomes.
HUD Credit Score Mortgage Credit Score Guidelines on FHA Loans
FHA loans stand out as one of the most welcoming options for homebuyers with lower credit scores. HUD’s FHA guidelines permit borrowers with a Minimum Decision Credit Score of 580 or higher to qualify for maximum FHA financing, which generally means a minimum 3.5% down payment on a purchase.
Borrowers with credit scores between 500 and 579 are generally limited to a maximum loan-to-value ratio of 90%, meaning at least 10% equity or a 10% down payment is typically required.
Borrowers with credit scores below 500 are generally not eligible for standard FHA-insured financing under the FHA credit-score framework. HUD continues to identify the 500-to-579 and 580-and-above credit tiers in its FHA underwriting guidance.
Can You Get an FHA Loan With a 500 Credit Score?
It is possible, depending on the lender and the borrower’s overall financial profile. HUD guidelines permit financing for eligible borrowers with credit scores from 500 through 579 when the transaction does not exceed 90% loan-to-value. That does not mean every FHA lender will approve a credit score of 500. Spotting this difference can make all the difference for hopeful homebuyers.
HUD Agency Requirements on FHA Loans
HUD establishes the basic FHA requirements. Individual lenders can impose additional requirements called lender overlays. For example, one lender may require a 620 credit score even though FHA guidelines permit lower scores. Another lender may accept borrowers under 600 but require stronger payment history, reserves, lower debt-to-income ratios, or manual underwriting. A denial from one lender, therefore, does not necessarily mean the borrower is ineligible for an FHA loan.
FHA Loans With a 580 Credit Score
If your credit score is 580 or above, you could open the door to an FHA loan with just 3.5% down. A credit score alone does not guarantee approval. The borrower must still satisfy the remaining FHA requirements regarding income, employment, assets, debt, property eligibility, and credit history. Recent late payments or other major derogatory credit events can affect the underwriting decision even when the borrower’s numerical score meets FHA requirements.
FHA Manual Underwriting With Lower Credit Scores
Manual underwriting offers an alternative route for borrowers who don’t get the green light from automated systems. Manual underwriting evaluates the borrower’s overall creditworthiness rather than relying entirely on an automated underwriting decision.
HUD’s manual underwriting guidelines include specific debt-to-income ratio requirements based partly on credit score and compensating factors.
Borrowers with scores below 580 or without a credit score generally face more restrictive manual underwriting ratios than those with scores of 580 or higher. For this reason, borrowers with lower credit scores often benefit from consulting a mortgage expert familiar with both automated and manual underwriting processes.
VA Loan Credit Score Guidelines
The Department of Veterans Affairs does not establish a universal minimum credit score for VA loans. This guideline is one of the biggest sources of confusion for VA borrowers.
VA requires the lender to evaluate whether the veteran or eligible borrower poses a satisfactory credit risk, but VA does not require a score of 580, 600, or 620.
The VA Lender’s Handbook specifically states that VA does not have a minimum credit score requirement. VA also emphasizes the borrower’s overall payment pattern rather than focusing solely on isolated credit problems.
Why Do Some VA Lenders Require a 620 Credit Score?
Because lender requirements and VA requirements are not always the same. A mortgage company may establish its own minimum credit score even when the VA does not require one. These additional restrictions are lender overlays.
One lender could require 620. Another may permit a lower score when the borrower has sufficient residual income, acceptable recent payment history, stable income, and otherwise satisfactory underwriting.
Therefore, it is important to distinguish between denial by a specific lender and ineligibility under Department of Veterans Affairs (VA) guidelines.
VA Loans With Bad Credit
Even with a lower credit score, veterans may still find a path to VA loan approval. The lender will typically examine the circumstances that led to the lower score. Recent mortgage late payments, significant unpaid obligations, repeated late payments, bankruptcy, foreclosure, collections, and other derogatory items may require additional review. VA underwriting places substantial importance on the borrower’s overall willingness and ability to repay obligations.
USDA Loan Credit Score Guidelines
USDA Guaranteed Loans are another mortgage program in which the agency itself does not set a universal minimum credit score. USDA Rural Development currently states that its Single Family Housing Guaranteed Loan Program has no credit score requirement, although applicants must demonstrate the willingness and ability to manage their debts. Individual USDA lenders can still impose their own minimum credit scores.
Is 640 Required for a USDA Loan?
Not always—other factors come into play, too. The number 640 has long been associated with USDA automated underwriting, which is why many borrowers and even some mortgage websites describe 640 as the minimum
USDA requirement. USDA’s current consumer guidance expressly states that the guaranteed program does not require a credit score.
That does not mean every borrower with a score below 640 will receive approval. Automated underwriting results, credit history, lender requirements, debt ratios, income eligibility, property eligibility, and other underwriting factors still matter.
Ready to Apply With Your Current Credit Score?
Complete a quick application or send your credit scenario. We’ll review your scores, credit history, debts, income, and best mortgage options.
Conventional Loan Credit Score Guidelines
Conventional mortgage credit score rules have seen big changes in recent years. It is no longer accurate to state that every Fannie Mae conventional loan requires a minimum credit score of 620.
Fannie Mae’s current Selling Guide states that Desktop Underwriter, or DU, loan casefiles do not have a universal minimum credit score requirement. DU evaluates the borrower’s creditworthiness using multiple risk factors.
For manually underwritten Fannie Mae loans, the minimum is generally 620 for eligible fixed-rate mortgages and 640 for eligible adjustable-rate mortgages, subject to other requirements. Freddie Mac’s standard fixed-rate mortgage guidance continues to identify a 620 minimum Indicator Score unless otherwise specified in the Freddie Mac Guide.
Can You Get a Conventional Loan With a Credit Score Below 620?
Potentially, depending on the specific automated underwriting system, loan structure, mortgage insurance requirements, investor requirements, and lender. Fannie Mae DU’s removal of a universal minimum credit score requirement does not mean that every borrower with a score below 620 can obtain conventional financing. Lenders continue to evaluate the overall financial profile when making loan decisions. Mortgage insurance companies, individual lenders, specific loan products, loan-to-value ratios, and other eligibility rules can create additional restrictions. For many borrowers with significantly lower scores, FHA or another mortgage program may still provide a more practical path.
Why a Higher Credit Score Matters on Conventional Loans
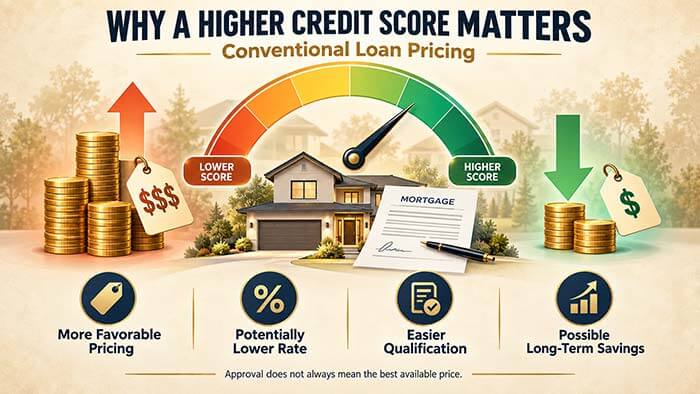
Even if you’re approved, your credit score can shape how much you pay over the entire life of your mortgage. Credit scores can affect conventional mortgage pricing through risk-based adjustments.
Higher scores generally provide access to more favorable mortgage pricing, while lower scores may result in higher rates or costs.
The CFPB notes that higher credit scores typically make it easier to qualify and can lead to lower interest rates. Therefore, improving your credit score before finalizing a mortgage can result in cost savings, even if you already meet the qualification requirements.
Mortgage Credit Scores Are Changing in 2026
The mortgage world is in the midst of its biggest credit scoring shake-up in decades. For many years, mortgage lending depended heavily on traditional Classic FICO models. However, this traditional system is undergoing significant changes.
In April 2026, HUD announced that FHA would permit VantageScore 4.0 and FICO Score 10T as eligible mortgage credit scoring models in addition to Classic FICO.
Fannie Mae and Freddie Mac also moved forward with the new scoring framework. On September 4, 2026, federal housing officials directed Fannie Mae and Freddie Mac to expand the availability of VantageScore 4.0 to mortgage lenders beyond the earlier limited rollout.
What Does VantageScore 4.0 Mean for Mortgage Borrowers?
The change does not mean every lender will immediately evaluate all borrowers with VantageScore 4.0. Mortgage systems, investors, credit reporting vendors, lenders, and underwriting platforms must implement the applicable rules operationally. This shift means the mortgage landscape is no longer ruled by a single credit score model. The scoring model used on a mortgage application may become increasingly important as the industry completes its transition.
FICO 10T and Trended Credit Data
FICO Score 10T and VantageScore 4.0 are designed to incorporate more modern credit information, including trended credit. Trended data reveals the story of how you’ve managed your balances over time, instead of focusing on just one moment in your credit history. The implementation of these models remains an evolving area of mortgage underwriting, so borrowers should ask their lender which scoring model is being used for their particular loan.
Why Your Mortgage Credit Score May Be Different From Credit Karma or Other Scores
Many homebuyers are surprised to discover that the credit score used by mortgage lenders differs from those provided by other sources. This discrepancy is typical and generally not a cause for concern. Consumers do not have one universal credit score. Different credit scoring models can produce different scores using data from Equifax, Experian, and TransUnion. A score used for a credit card, auto loan, consumer credit-monitoring service, or educational product may therefore differ from a score used for mortgage underwriting. The CFPB specifically warns consumers that the score they see may differ from the score a mortgage lender uses.
Mortgage Lenders May Review Multiple Credit Scores
Historically, mortgage lending has relied heavily on credit information from all three major credit bureaus. For a traditional three-score mortgage report, lenders have commonly used the middle score when three usable scores are available for an individual borrower. However, mortgage credit reporting and scoring requirements are changing quickly. Trust your lender’s official mortgage credit report, since scores from apps or websites often are not used for underwriting.
What Factors Affect Your Credit Score?
Credit scores are calculated using information contained in your credit reports. The exact formula depends on the scoring model. The CFPB identifies several common factors, including payment history, unpaid debt, the number and type of credit accounts, account age, credit utilization, new credit applications, collections, foreclosures, and bankruptcies.
Payment History
Late payments can have a significant impact on mortgage qualification. Recent mortgage late payments are especially important because housing payment history can indicate how a borrower is likely to manage a future mortgage. A single older late payment may be viewed differently from repeated recent late payments. Underwriters generally look at both the numerical score and the pattern behind that score.
Credit Card Utilization
Credit utilization is the slice of your available credit you’re actually using. Even if you pay on time, high balances can drag down your score. Paying them off can boost your mortgage profile. Borrower’s mortgage credit profile. Closing paid-off credit card accounts without a good reason can reduce available revolving credit and negatively affect credit utilization.
Collections and Charge-Off Accounts
Collections and charge-offs do not automatically mean that someone cannot get a mortgage. The effect depends on the mortgage program, the type and amount of the debt, when it occurred, whether it is disputed, and the overall underwriting findings. Government and conventional mortgage programs treat outstanding debt differently. Before paying off collections, check with an experienced loan officer. Sometimes paying them right before you apply can have unintended consequences.
Paying an account can affect your credit report, available cash, or underwriting conditions. The best approach depends on your specific mortgage situation.
A bankruptcy or foreclosure can significantly affect credit, but neither permanently prevents a borrower from becoming a homeowner again. FHA, VA, USDA, conventional, and Non-QM loan programs have different waiting periods and underwriting requirements after major derogatory credit events. What you do after a bankruptcy or foreclosure can matter just as much as the event itself. A borrower who has re-established credit and maintained all obligations on time may present a stronger risk profile than someone whose credit difficulties continued after bankruptcy or foreclosure.
What Is a Lender Overlay?
A lender overlay is an additional mortgage requirement imposed by a lender beyond the minimum rules established by the underlying loan program. Credit scores are one of the most common examples.
Suppose FHA permits a qualified borrower with a 580 score to obtain maximum financing. A lender could still establish a minimum score of 620.
That 620 requirement would be the lender’s rule, not FHA’s underlying minimum guideline. This difference is important for anyone with a lower credit score, manual underwriting, or a history of credit issues such as bankruptcies or late payments.
One Mortgage Lender’s Denial Does Not Always Mean You Cannot Qualify
Mortgage lenders do not all underwrite loans exactly the same way. A borrower may be denied because of a lender overlay rather than an actual FHA, VA, USDA, Fannie Mae, or Freddie Mac restriction. Before giving up on your dream of homeownership, find out exactly why your loan was denied. Ask whether the problem is an agency requirement, automated underwriting finding, investor restriction, mortgage insurance requirement, or lender overlay. The answer might unlock new possibilities with a different lender or loan program that’s a better fit for you.
Improve Your Credit Before Mortgage Approval
Lowering credit card balances, correcting report errors, removing unnecessary disputes, and avoiding new debt may help strengthen your loan file.
Can You Buy a House With a 500 Credit Score?
FHA is generally the first agency program to consider when a qualified borrower has a 500-to-579 credit score, because FHA permits financing in this range with a maximum loan-to-value ratio of 90%. VA borrowers may also have possibilities because VA does not establish a universal minimum score.
Other mortgage loan options, including certain Non-QM programs, may also be available depending on the borrower’s circumstances.
Having a 500 credit score does not guarantee you will qualify for a mortgage. Recent payment history, housing history, debt, income, reserves, down payment, derogatory credit, and the reason for the low score become important.
Can You Buy a House With a 580 Credit Score?
Yes, owning a home is still within reach with a 580 credit score. Many borrowers in this range qualify for the maximum FHA loan amount with just 3.5% down. VA borrowers may also qualify, depending on the lender and overall credit profile. A borrower should not assume a 580 score automatically means FHA is the only available mortgage option. The entire loan application should be reviewed before selecting a program.
Can You Buy a House With a 620 Credit Score?
With a 620 credit score, you could unlock a wider variety of mortgage options. Depending on the complete loan file, borrowers may qualify for FHA, VA, USDA, and conventional financing. A score of 620 does not guarantee approval. The automated underwriting system may still consider debt-to-income ratio, reserves, loan-to-value ratio, credit history, payment history, property type, and other risk factors. Increasing your credit score prior to closing may result in cost savings, as higher scores can lead to more favorable rates on conventional loans.
How to Improve Credit Before Applying
Boosting your mortgage credit score might not take as long as you think. The best approach depends on what’s holding your score back the score. For some borrowers, revolving credit utilization is the biggest issue. For others, incorrect reporting, recent late payments, too many new accounts, collections, or limited credit history matter more. Start by checking all three of your credit reports for errors or outdated information. The CFPB recommends reviewing credit reports and correcting errors before applying for a mortgage because incorrect information can lower a score and increase borrowing costs.
Pay Down Revolving Credit Strategically
Paying down credit card balances is often one of the most effective ways to improve your credit profile when your credit card utilization is high. The key metric is the balance reported to credit bureaus, not just making minimum payments. Since creditors report balances at different points in the billing cycle, timing may influence outcomes.
Do Not Open New Credit Before Closing Without Talking to Your Lender
Avoid applying for unnecessary credit cards, auto loans, personal loans, or other debts before and during the mortgage process. Inquiries and new monthly obligations can affect both credit scores and debt-to-income ratios. The CFPB says mortgage inquiries generally have a relatively small effect on credit scores and notes that multiple mortgage inquiries made while rate shopping within a 45-day window are generally treated as one inquiry for scoring purposes. Opening a new credit account is different and could put your mortgage approval at risk. Borrowers sometimes try to repair their credit before applying by disputing every derogatory item.
Such actions can complicate underwriters and automated underwriting systems may require certain disputes to be resolved or removed before the loan can proceed.
Similarly, paying an old collection is not automatically the best first step. Have your mortgage credit report reviewed before making significant changes to ensure your strategy aligns with your mortgage goals. Both matter. A credit score summarizes information from the credit report, but mortgage underwriting can examine the information behind the score.
For Example, Here is a Case Scenario:
- Two borrowers may both have a 620 score.
- One borrower may have high credit-card utilization but no late payments.
- The other may have low balances but several recent 30-day late payments.
- The numerical score is the same, but the underwriting risk may differ greatly.
- For this reason, mortgage lenders evaluate more than just the numerical credit score.
| Loan Type | Minimum Score (Typical) | Down Payment | Approval Notes (tied to credit score mortgage guidelines) |
| FHA | 580+ | 3.5% | AUS eligible with clean 12-month housing/credit. |
| 500–579 | 10% | Often manual underwriting; stricter DTI; compensating factors help. | |
| VA | No VA-set min | 0% | Lender overlays 580–620 common; residual income & overall file matter. |
| Conventional | 620+ | 3–5% (first-time buyers) | LLPAs priced by FICO/LTV/occupancy; higher FICO = better pricing. |
| Non-QM | Program-specific | 10–20%+ | Bank-statement, DSCR, recent BK/foreclosure allowed by program. |
This table maps directly to real-world credit score guidelines, helping borrowers match score bands with down-payment requirements and underwriting treatment.
Does a Higher Credit Score Lower Your Mortgage Rate?
Generally, yes. Higher credit scores usually indicate lower credit risk and can lead to better mortgage pricing, particularly for conventional loans. The relationship is not the same for every borrower or mortgage program.
The interest rate ultimately depends on several factors, including the loan program, credit score, loan-to-value ratio, property type, occupancy, loan amount, market conditions, and other pricing adjustments.
The CFPB states that borrowers with higher scores generally have greater access to mortgage options and lower rates, while borrowers with lower scores may have fewer choices and higher borrowing costs.
Should You Improve Your Credit Before Buying a House?
Not always. Waiting to improve a credit score can make sense when a relatively small increase could meaningfully reduce the down payment, improve mortgage pricing, or open a better loan program. However, borrowers should not necessarily delay purchasing a home if they already qualify and the transaction is financially prudent. Waiting for a specific credit score may not be required. Assess the potential benefits of a higher score. A mortgage loan officer can help you compare qualifying now versus waiting to improve your credit score.
Getting Approved for a Mortgage With Lower Credit Scores
If your credit score is on the lower side, you’ll want a strategy designed just for you, rather than a one-size-fits-all approach. The first step is to find the mortgage program that best fits the borrower rather than trying to fit the borrower into a specific lender’s requirements.
A strong mortgage application usually includes steady income, a good history of paying housing costs, manageable debt, some cash reserves, a reasonable down payment, and proof that past credit issues have been resolved.
Underwriting should also be reviewed before assuming that the numerical score alone determines approval. If your credit file is tricky, manual underwriting or exploring a different mortgage program could be your ticket to approval. Borrowers who have been denied due to credit concerns may seek a comprehensive review of their mortgage profile to determine whether the denial resulted from a program guideline, automated underwriting decision, or lender overlay.
Final Thoughts on Credit Score Mortgage Guidelines
There is no single minimum credit score that applies to every home loan. FHA permits eligible borrowers with credit scores as low as 500 under its 90% maximum LTV rules and generally allows maximum FHA financing beginning at 580. VA does not establish a minimum credit score. USDA currently states that its Guaranteed Loan Program does not require a credit score.
Conventional mortgage guidelines depend on Fannie Mae or Freddie Mac requirements, the automated underwriting system, mortgage insurance, loan characteristics, and lender requirements.
Credit scoring itself is also changing in 2026 with the expansion of VantageScore 4.0 and FICO Score 10T. It is important to recognize that a lender’s minimum credit score may not reflect the minimum required by the underlying mortgage program. Even if your credit isn’t perfect, you may have more options than you think—one lender’s denial doesn’t tell the whole story. Borrowers who need a five-star national mortgage company licensed in 48 states with no overlays and who are experts on credit score mortgage guidelines, please contact us at 800-900-8569. Text us on 262-627-1965 for a faster response, or email us at gcho@gustancho.com.
Frequently Asked Questions About Mortgage Credit Score Guidelines
What is the Lowest Credit Score You Can Have to Buy a House?
There is no single minimum score for every mortgage. FHA guidelines may allow eligible borrowers with scores as low as 500 to qualify with at least 10% down payment or 10% equity. VA and USDA do not set universal minimum credit scores for agencies, although individual lenders may impose their own.
Can I Get a Mortgage with a 500 Credit Score?
Potentially. FHA guidelines permit borrowers with scores between 500 and 579 to obtain financing with a loan-to-value ratio of up to 90% when all other requirements are satisfied. Finding a lender without a higher credit-score overlay may be necessary.
What Credit Score is Needed for a 3.5% Down FHA Loan?
FHA generally requires a Minimum Decision Credit Score of 580 for maximum financing, allowing a qualified homebuyer to purchase with a minimum 3.5% down payment.
What Credit Score is Required for a VA Loan?
VA does not establish a universal minimum credit score. Individual VA lenders may set their own minimum scores as lender overlays.
Does USDA Require a 640 Credit Score?
USDA’s current Guaranteed Loan Program guidance says there is no universal credit-score requirement. However, automated underwriting and individual lender requirements can affect borrowers with lower scores.
Is 620 Still the Minimum Credit Score for a Conventional Loan?
Not universally. Fannie Mae currently states that DU loan case files do not have a universal minimum credit score requirement. Manually underwritten Fannie Mae fixed-rate loans generally require at least 620, while Freddie Mac standard products commonly reference a 620 minimum Indicator Score unless otherwise specified.
Why is My Mortgage Credit Score Lower Than the Score on My Credit App?
Different lenders and credit products may use different scoring models and credit bureau data. A consumer credit-monitoring score, therefore, may not match the score used for mortgage underwriting.
Can I Qualify for a Mortgage After Being Denied Because of My Credit Score?
Possibly. The denial could result from a particular lender’s overlay rather than the minimum guidelines for FHA, VA, USDA, Fannie Mae, or Freddie Mac. A second review can determine whether another lender or loan program may work.
Does Paying Off Credit Cards Increase My Mortgage Credit Score?
It can, particularly when high revolving utilization is lowering the score. The extent of improvement depends on the borrower’s overall credit profile and on when the lower balances are reported to the credit bureaus.
Will Shopping for Mortgage Rates Hurt My Credit Score?
Mortgage credit inquiries can have a small effect on a credit score. However, the CFPB states that multiple mortgage inquiries within a 45-day rate-shopping period are generally recorded as a single inquiry for scoring purposes.
Can You Get a Mortgage Without a Credit Score?
In some circumstances, yes. Certain mortgage programs offer options for borrowers without traditional credit scores, provided alternative or nontraditional credit history can demonstrate satisfactory payment behavior. Requirements depend on the loan program and underwriting method.
Are Mortgage Lenders Required to Use FICO Scores?
The mortgage industry is moving away from an exclusively Classic FICO framework. FHA, Fannie Mae, and Freddie Mac have expanded the approved credit score models to include VantageScore 4.0, with FICO Score 10T also part of the modernization framework. Implementation can vary by lender and program.
Does Having a Low Credit Score Automatically Mean I Will Have a High Mortgage Rate?
Not automatically. Credit score is an important pricing factor, but mortgage rates also depend on the loan program, loan-to-value ratio, property type, occupancy, loan amount, market conditions, and other risk factors. Higher scores generally provide more favorable pricing opportunities.
FHA, VA, USDA, Conventional, or Non-QM? Compare Credit Requirements
Each mortgage program has different credit score rules and lender overlays. We’ll review your score, credit history, income, DTI, and loan options.