
Choosing a mortgage starts with three questions: What monthly payment can you afford? How much cash can you bring to closing? Will the loan work for the home you want? A house in Denver, a rural property outside Grand Junction, and a mountain condo may require different financing. This guide explains how to compare Colorado mortgage loans, understand qualification requirements, and get your finances reviewed before making an offer.
Compare Colorado Mortgage Loan Options
 Start with the programs that fit your eligibility, income documentation, and intended use of the home. Then compare their costs using the same purchase price and realistic estimates for taxes, insurance, and any homeowners association dues.
FHA Loans in Colorado
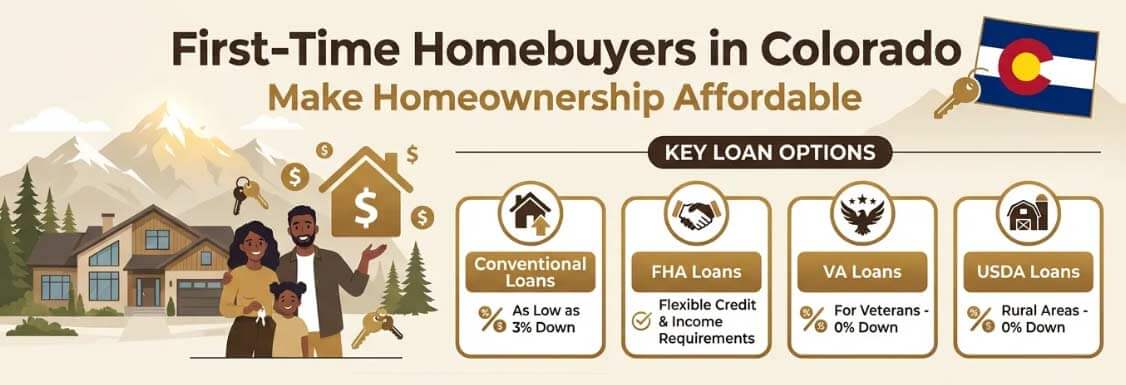
FHA loans can be worth considering if your credit history or savings make conventional financing difficult. The FHA allows a 3.5% down payment for those with a qualifying credit score of at least 580. Borrowers with scores from 500 through 579 may be eligible with at least 10% down, subject to underwriting and lender requirements. FHA loans require both upfront and yearly mortgage insurance premiums. Ask how those charges affect your payment and how long annual mortgage insurance will apply. FHA financing is available to both qualifying repeat buyers and first-time buyers.
VA Loans in Colorado
Veterans, service members, and some surviving spouses should consider a VA loan over other options. With enough entitlement and a good appraisal, you might not need a down payment. VA loans don’t have monthly mortgage insurance. A Certificate of Eligibility shows you qualify for the benefit, but your lender will still need to check your income, credit, and ability to repay. You may need to pay a VA funding fee unless you are exempt. You might also need cash for closing costs or if the appraisal is lower than the purchase price. Be sure to review the VA purchase loan requirements and funding fee details.
USDA Loans in Colorado
USDA’s Guaranteed Loan Program offers financing with no required down payment for eligible primary residences in qualifying rural areas. Both the property address and household income must meet the program’s requirements. Check the actual address through the USDA’s eligibility site. A city name or a property’s rural appearance does not establish eligibility. USDA loans include guarantee fees, and the lender reviews your ability to manage debt. This option is worth checking early when you are considering homes outside major urban areas.
Conventional Loans in Colorado
Some conventional purchase programs allow eligible buyers to put down as little as 3%. Eligibility can depend on the program, income, occupancy, property type, and first-time buyer status. A 3% down payment is not available for every conventional transaction. Conventional loans typically require private mortgage insurance when the down payment is below 20%. Borrowers may be able to cancel that insurance after meeting the applicable requirements. Conventional financing also offers options for second homes and investment properties, although those transactions follow different rules. Compare the Fannie Mae 97% financing options before assuming you need a large down payment.
Jumbo Loans in Colorado
A jumbo loan generally finances an amount above the conforming loan limit for the property’s county and number of units. The loan amount, rather than the home’s price alone, determines whether financing exceeds that limit. For 2026, the baseline conforming limit for a one-unit home is $832,750. Certain Colorado counties have higher limits. Check FHFA’s county loan limit information before deciding you need jumbo financing. FHFA Jumbo lenders set their own requirements for credit, down payments, debt ratios, and reserves. Ask how much money you must have left after closing.
Non-QM Loans in Colorado
Non-QM loans can provide alternatives when standard income documentation does not fit your finances. Depending on the lender, options may include bank statement loans for self-employed borrowers or rental property loans evaluated based on the property’s cash flow. These programs still require an underwriting review. Bank deposits are not automatically qualifying income, and a property’s advertised rent does not establish loan eligibility. Compare the documentation method, down payment, reserves, interest rate, and fees. If you are financing an investment property, also ask whether a prepayment penalty applies. Non-QM terms vary by investor and program.
Choosing a Loan as a First-Time Buyer
Start with any program tied to your eligibility, such as VA financing, and then compare other suitable options. A first-time buyer who qualifies for a low-down-payment conventional loan may make a different decision than a buyer with credit challenges considering an FHA loan. Ask for a comparison showing the monthly payment, mortgage insurance or program fees, and estimated cash to close. Use your budget to decide which option you can comfortably maintain.
Ready to Buy or Refinance a Home in Colorado?
Complete a quick application or send your scenario. We’ll compare Colorado mortgage programs, qualification requirements, payment options, and the next steps toward approval.Credit, Income, and Down Payment Requirements
A mortgage approval depends on several parts of your finances working together. A good credit score cannot replace adequate income, and a large down payment does not resolve every credit issue.
Credit Scores and Lender Requirements
The score shown in a consumer credit app may differ from the score used for your mortgage. Have the lender review a mortgage credit report before making decisions based on an online score. The VA does not have a minimum credit score requirement, though lenders are free to impose their own. Similarly, the USDA Guaranteed Loan Program also lacks a minimum credit score requirement; what remains important are a satisfactory credit history and the lender’s own requirements. The standard requirements depend on the method of underwriting. For example, Fannie Mae’s Desktop Underwriter does not use a fixed minimum third-party credit score. Moreover, the lender’s and mortgage insurance requirements can affect eligibility. If a lender declines your application, ask for the specific reason. Find out whether it involves a program rule, the automated underwriting result, or an additional lender requirement.
Income and Debt-to-Income Ratio
Lenders assess qualifying income from verified sources and evaluate its history, stability, and likelihood of continuation based on the income type. The debt-to-income ratio (DTI) measures your monthly debt payments against your gross monthly income. A standard housing payment includes principal, interest, taxes, insurance, mortgage insurance, and any association dues. If your monthly debt payments are $3,000 and your monthly income is $8,000, your debt-to-income ratio is 37.5%.While this calculation demonstrates the ratio, it does not guarantee loan approval. Eligible DTI ratios vary depending on the loan and underwriting approach, and VA underwriting also takes residual income into account.
Self-Employed Income
The fact that you are self-employed does not mean that you have to obtain a non-QM loan; you could be eligible for FHA, VA, USDA, or conventional financing provided that your documented income satisfies the rules of the chosen program. The revenue from business activities and the income used to qualify for a mortgage may be different. A lender is able to look at tax returns, the way the business is owned, the trends in income, and whether the money is available without weakening the business. Do not make a purchase decision based on this review unless the review has been completed. If the amount you need is not supported by standard documentation, inquire about whether an alternative documentation program applies. Fannie Mae’s guidance for self-employed borrowers describes how lenders assess business income.
Down Payment, Cash to Close, and Reserves
Your down payment is one part of the money needed for a purchase. Cash to close can also include closing costs, prepaid expenses, and initial escrow deposits, with adjustments for earnest money and permitted credits. On a $500,000 purchase, 3% is $15,000, and 3.5% is $17,500. Those amounts represent the down payment only. They do not include other transaction costs. Reserves are funds remaining after closing. Some loans require them, and keeping a financial cushion can also help you handle repairs and other expenses after moving in.
How Property Type Affects Your Loan Options
Tell your loan officer how you intend to use the property before making an offer. A loan suitable for a primary residence may not work for a vacation home or a rental property.
Primary Residences, Second Homes, and Rentals
FHA and USDA purchase financing are intended for qualifying primary residences. VA purchase loans also have occupancy requirements. Conventional financing can cover eligible primary residences, second homes, and investment properties. A second-home classification has specific requirements; a property bought mainly to generate rental income may need investment-property financing. Disclose planned rentals or management agreements early. The lender must review the home’s actual use.
Condos and Mountain Properties
If you are buying a condo, your lender might need to check both the condo project and your finances. Share the listing, association details, and any rental or management agreements before you decide to move forward. If you are looking at either mountain or rural houses, find out as early as possible regarding matters such as access, utilities, appraisals, and insurance. Get an insurance quote for the particular address to make sure that your estimated payment matches the property you are interested in.
Manufactured Homes and Properties Needing Repairs
Manufactured homes may require review of the home’s construction, foundation, title, and land ownership. Tell the lender if the home is on leased land or financed separately from the land. A property that needs repairs can also affect your financing options. Ask whether repairs must be completed before closing or whether an eligible renovation loan could cover the work. Borrower preapproval alone does not establish that a particular property is acceptable.
Colorado Mortgage Preapproval: Documents and Steps
Preapproval is most useful when it reflects a review of your finances and the kind of property you plan to buy. Ask what has been verified and what conditions remain.
Prepare Your Financial Documents
Lenders often ask for documents like recent pay stubs, W-2s, bank statements, identification, and details about your debts. Depending on your income, you might also need to provide tax returns, business records, benefit letters, or other paperwork. Let your lender know early about any gifts, recent job changes, unusual deposits, or money transfers. If you have a bankruptcy, foreclosure, or repayment agreement in your past, share those records so the lender can review them. The documents you need will depend on your loan, income, and what the lender finds during underwriting. It’s best to follow your lender’s checklist instead of assuming everyone needs the same forms.
Set a Budget and Review the Proposed Loan
Tell the lender your preferred monthly payment, the amount you have saved, and the price range you expect to pay. When talking about how affordable the purchase is, be sure to include the estimated amounts for taxes, homeowners’ insurance, and association dues. Find out if the preapproval states that you will pay off debt, make a specific down payment, or keep a certain amount in reserves. Make sure you understand those conditions before making your offer.
Compare Costs and Keep Your Approval Current
To compare loan offers, make sure you use the same loan amount, type, term, and down payment for each one. Check the points, lender fees, mortgage insurance, estimated cash needed at closing, and if the rate is locked in. The Consumer Financial Protection Bureau offers a Loan Estimate comparison guide to help you review and compare loan offers. While you are buying a home, talk to your loan officer about any new loans, changes in your job, or large transfers between accounts. The final approval will also depend on the property, title, updated financial details, and any other underwriting conditions.
Help With Down Payments and Closing Costs
Colorado buyers may be eligible for assistance through CHFA or local programs. You must qualify for the first mortgage and the selected assistance program. Availability, eligible uses, repayment terms, and total borrowing costs vary. If upfront cash is your main obstacle, read our Colorado down payment assistance programs guide for assistance-specific information. Ask your loan officer to compare your overall costs with and without assistance.
Final Thoughts on Colorado Mortgage Loans
The right Colorado mortgage loans should fit your monthly budget, available savings, and the property you plan to buy. Before making an offer, have your financial documents reviewed and ask your lender to explain the estimated cash-to-close and any remaining conditions on your preapproval.
If another lender has declined your application, bring the reason for the denial to Gustan Cho Associates. We can assess your situation and identify if a different loan program or lender is available.
Ready to discuss your Colorado home purchase? Call (800) 900-8569 or email gcho@gustancho.com to review your financing options.
Colorado Mortgage Loans FAQs
Do All Colorado Mortgage Loans Require a 620 Credit Score?
No. Requirements vary by loan program, underwriting method, lender, and mortgage insurer. FHA has published score and down payment thresholds, while VA and USDA do not set a universal agency minimum score. Have a lender evaluate your credit report and the complete application.
Do I Need 20% Down to Buy a Home in Colorado?
No. Some eligible borrowers can use low-down-payment or no-down-payment financing. Putting down less can affect mortgage insurance, program fees, and the amount borrowed. Compare the full payment and cash-to-close before choosing a down payment.
Can I Get a Colorado Mortgage If I Am Self-Employed?
Yes, if your documented income and overall application meet the program’s requirements. Have the lender calculate qualifying income before you shop. A standard loan may work; bank statement financing may be an alternative if a program is available that better fits your documentation.
How Do I Find the Mortgage Loan Limit for My County in Colorado?
Use FHFA’s conforming loan limit lookup for conventional conforming loans and HUD’s mortgage limit lookup for FHA. Select the correct county, year, and number of units. FHA and conventional limits are different.
What Documents Do I Need for Colorado Mortgage Preapproval?
Start with the lender’s checklist for your income and selected loan. Common requests include identification, income records, account statements, and debt information. Self-employed borrowers and applicants with recent credit events may need additional records.
Does Mortgage Preapproval Guarantee That I Can Buy Any Home?
No. The lender must also approve the property and complete the remaining underwriting review. Send unusual listings, condo information, rental restrictions, or repair concerns to your loan officer before relying on your preapproval for that purchase.
This article about “Colorado Mortgage Loans: Compare Programs and Requirements” was updated on September 29th, 2026.
