
Buying a Home in Oakbrook Terrace, Illinois
Buying a home or refinancing a mortgage in Oakbrook Terrace, Illinois, involves more than finding an advertised mortgage rate. The right loan program depends on your income, credit history, debts, assets, property type, occupancy, down payment, and underwriting guidelines that apply to your individual mortgage file. Gustan Cho Associates helps homebuyers, homeowners, and real estate investors evaluate traditional and alternative mortgage options. We often work with borrowers whose mortgage applications require more detailed underwriting due to credit issues, high debt-to-income ratios, self-employment, bankruptcy, foreclosure, irregular income, or prior mortgage denial.
Important location disclosure: Gustan Cho Associates no longer maintains a mortgage office in Oakbrook Terrace, Illinois. It operates as a DBA of Coast 2 Coast Mortgage Lending, LLC, NMLS 376205.
Coast 2 Coast Mortgage Lending is headquartered in St. Augustine, Florida. Gustan Cho Associates maintains a branch office in Salem, Wisconsin, NMLS 2885337. Mortgage availability depends on the applicable company, branch, loan originator, and state licensing. Over 80% of our borrowers are folks who could not qualify at other lenders due to stress during the mortgage process or a last-minute denial. Another reason homebuyers, homeowners, and investors choose Gustan Cho Associates Mortgage is that we offer every loan program available in the marketplace for owner-occupied, second-home, and investment properties. Our average loan officer has over 10 plus experience in originating tough loans. Any loan officer can qualify and originate a 700 FICO homebuyer with a 40% debt-to-income ratio.
Can Gustan Cho Associates Help With an Oakbrook Terrace Mortgage?
Yes, as long as licensing and loan program rules are met. Borrowers buying or refinancing in Oakbrook Terrace may qualify for FHA, VA, conventional, jumbo, or non-QM mortgages, depending on their situation. Gustan Cho Associates does not have an office in Oakbrook Terrace, but borrowers can work with licensed mortgage professionals remotely by phone, email, secure document upload, and online mortgage tools. Approval depends on underwriting, program rules, property eligibility, lender rules, and final approval.
Mortgage Options for Homebuyers in Oakbrook Terrace
There is no single best mortgage program for every Oakbrook Terrace homebuyer. Two borrowers purchasing homes at the same price can require completely different financing strategies. The loan officer should first review the complete borrower profile rather than automatically placing every applicant into the same mortgage program.
FHA Loans in Oakbrook Terrace
FHA loans can be useful for borrowers who need a lower down payment or whose credit profiles do not qualify for conventional financing. FHA underwriting considers much more than a credit score. Payment history, housing history, collections, charge-offs, debt-to-income ratio, employment, assets, and previous major credit events may all affect qualification.
For calendar year 2026, HUD lists the one-unit FHA loan limit for DuPage County at $541,287. FHA loan limits are updated annually, so borrowers should verify the applicable limit when they apply.
Some FHA borrowers receive automated underwriting approval. Others may require manual underwriting. That distinction matters because manual underwriting has additional requirements involving debt-to-income ratios, reserves, payment shock, housing history, and compensating factors.
Conventional Loans in Oakbrook Terrace
Conventional mortgages backed by Fannie Mae or Freddie Mac may work well for borrowers with established credit, qualifying income, and sufficient assets. Conventional financing can also provide flexibility for primary residences, second homes, and investment properties, subject to the requirements of the particular loan program.
The 2026 one-unit conforming loan limit for DuPage County is $832,750. Loans above the applicable conforming limit generally fall into the jumbo category. Loan limits change annually.
Borrowers should not think FHA loans are always easier or that conventional loans are always better. The right choice depends on factors such as down payment, mortgage insurance, interest rate, closing costs, monthly payment, property type, and your long-term financial goals.
VA Loans in Oakbrook Terrace
Eligible veterans, active-duty service members, and certain surviving spouses may qualify for VA financing. VA loans can offer significant benefits, including the possibility of financing a primary residence without a down payment when eligibility, entitlement, property, underwriting, and lender requirements are satisfied. VA underwriting also includes residual-income requirements in addition to reviewing traditional debt-to-income calculations. A high debt-to-income ratio by itself does not tell the entire story on a VA loan. Residual income, credit history, employment stability, assets, and the overall file can all be important factors in the underwriting decision.
Jumbo Mortgage Options
A mortgage amount above the applicable conforming loan limit may require jumbo financing. Jumbo loans usually have their own rules for credit, savings, down payment, income proof, and property eligibility. These rules can vary a lot between lenders. This is one reason comparing programs matters. A borrower who does not qualify under one jumbo program may fit another investor’s guidelines.
Non-QM Loans for Oakbrook Terrace Borrowers
Traditional FHA, VA, and conventional mortgages do not fit every borrower. Self-employed borrowers, real estate investors, borrowers with recent credit problems, or those whose taxable income does not show their real cash flow may need a non-QM or alternative mortgage program.
Non-QM does not mean there are no approval rules. Credit, savings, property value, down payment or equity, reserves, income or cash-flow proof, and other rules still apply.
Depending on the program and borrower qualifications, alternatives may include bank-statement loans, DSCR loans for investment properties, asset-depletion programs, profit-and-loss programs, and other non-QM financing. Interest rates, fees, early payment rules, and qualification requirements may also differ significantly from those of conventional and government loans.
Mortgage Options for Self-Employed Borrowers in Oakbrook Terrace
Self-employed borrowers sometimes have trouble qualifying because mortgage approval typically evaluates income differently from how a business owner views cash flow. Tax deductions that reduce taxable income also lower the income used for traditional mortgage approval.
Assuming a self-employed borrower cannot qualify, a mortgage expert should review tax returns, business history, bank statements, business setup, available cash, and mortgage programs.
In certain circumstances, a traditional conventional mortgage will still be the appropriate choice. In other situations, a bank statement, an asset-based program, or another non-QM program may provide an alternative. The goal should be to find a program that really fits the borrower’s financial situation, rather than pushing them into a loan they cannot afford.
Buying a Condo in Oakbrook Terrace
Condo buyers should know that mortgage approval looks at both the borrower and the condo project. A borrower can have high income, credit, and assets and still face financing problems if the condominium project does not meet the rules of the chosen loan program.
Depending on the deal, the lender may check insurance, homeowners association details, lawsuits, project finances, owner occupancy, commercial space, unpaid fees, building problems, and other project features.
Buyers considering an Oakbrook Terrace condo should discuss financing early in the buying process, rather than waiting until just before closing to determine whether the project is acceptable.
The Expertise of the Team at Gustan Cho Associates vs Other Loan Officers
Not many loan officers can do loans like the team at Gustan Cho Associates. Some of the cases we tackle are homebuyers with credit scores down to 500 FICO, outstanding collections, charged-off accounts, during Chapter 13 Bankruptcy, late payments after bankruptcy and/or housing event, mortgage late payments, tax liens, judgments, and employment gaps.
One-Stop Mortgage Shop Due To Hundreds of Alternative and Niche Loan Options
There are many self-employed buyers who cannot provide income tax returns due to the adjusted income. Gustan Cho Associates has countless non-QM and alternative financing mortgage options such as 12 months bank statement loans, non-QM mortgages one day out of bankruptcy and/or foreclosure, asset-depletion, 10% down payment jumbo loans, W-2 income only mortgages, no-doc mortgages, stated-income loans and many other types of mortgage options. The mortgage loan programs we have are for owner-occupant homes, second homes, and investment properties.
Thousands of Mortgage Options For Borrowers
Gustan Cho Associates has over 300 wholesale mortgage lenders. Gustan Cho Associates has the states to service borrowers, over 300 wholesale lenders, and competitive rates that most mortgage bankers cannot match.
Buying a Home in Oakbrook Terrace, Illinois? Start With Pre-Approval
Before you start touring homes, know your budget, monthly payment, down payment, closing costs, and loan options. Get pre-approved so you can shop with confidence.One-Stop Mortgage Shop | We Have All Types of Mortgage Options
Gustan Cho Associates, which the brick and mortar location is regionally based in Oakbrook Terrace, Illinois has a national reputation for being licensed in most of the 50 states. We are able to do government and conventional loans with no overlays on FHA, VA, USDA, and conventional loans. Non-QM loans and alternative lending programs include bank statement loans, no-doc mortgages, mortgages one day out bankruptcy and foreclosure, and even late payments in the past 12 months.
Being Able to Do Loans Other Lenders Cannot Do
The team at Gustan Cho Associates has a reputation for being able to do loans other lenders cannot do. Many of our clients find us through word of mouth, referrals from family members and friends, or through our National VERIFIED Preferred Realtor Partner Network. Over 80% of our borrowers are folks who either got denied or pulled out due to stress from their previous lender. The team at Gustan Cho Associates firmly believes the qualification and pre-approval stage of the mortgage process is the most important. The number one reason for stress during the mortgage process or a last-minute mortgage denial is due to not being properly qualified by the loan officer.
How Property Taxes and HOA Dues Affect Mortgage Qualification
A borrower qualifies based on the expected total housing payment, not just the loan principal and interest. For many mortgage programs, housing costs may include principal, interest, property taxes, homeowners’ insurance, mortgage insurance if needed, homeowners’ association fees, and other required housing costs. This is especially important in places where property taxes or condo fees make up a big part of the monthly housing payment.
A buyer who qualifies for a certain price in one community may qualify for a different amount in another because taxes, insurance, and HOA fees vary.
That is why a good mortgage pre-approval should look at expected total housing costs, not just the loan amount. Credit problems do not always mean you cannot buy a home. However, the type, severity, timing, and pattern of a credit problem matter. An isolated late payment can be evaluated differently from repeated recent delinquencies. An old collection can be treated differently from a recent late payment on a mortgage. Bankruptcy, foreclosure, short sale, loan modification, judgments, disputed accounts, and active Chapter 13 bankruptcy can each have different mortgage guidelines. The first step is to determine if a rule really blocks approval or if the problem comes from extra requirements set by a specific lender.
Understanding Mortgage Guidelines versus Lender Overlays
Sometimes borrowers are told they do not qualify when the real problem is extra rules set by a specific lender. An agency guideline is a rule set by an agency or investor. A lender overlay is an extra rule added by a lender that goes beyond the program’s rules. For example, a loan program may allow a certain credit profile, debt-to-income ratio, manual underwriting, or bankruptcy history, while an individual lender may choose not to accept these rules. That does not mean every borrower denied because of an overlay will qualify with another lender. The full application must still meet the program rules and the lender’s requirements. So, understanding why a loan was denied is very important.
What We Review When Another Mortgage Lender Says No
Many borrowers contact Gustan Cho Associates after experiencing problems with another mortgage company. When reviewing a difficult mortgage file, we do not start by just looking at who declined the loan.
Sometimes, a different program can be the real solution. At times, the borrower needs more time to improve credit, build payment history, save money, pay down debts, or wait the required time.
The most helpful questions are why the loan was declined, whether the problem was a TMMED program rule or a lender’s additional rule, whether the income was calculated correctly, whether another loan program might work better, and whether additional documents could change the approval decision. A careful mortgage review should find both options.
FHA and VA Manual Underwriting
Automated approval systems are important in mortgage lending, but not every borrower gets automatic approval. Some borrowers may qualify for manual underwriting when the program allows it. Manual underwriting usually requires a closer look at the borrower’s financial history and ability to handle the mortgage payment. Payment shock, savings, extra factors, credit history, income stability, and debt ratios can be especially important.
Manual approval should not be seen as a shortcut around mortgage rules. It is a different method with its own rules. Bankruptcy or foreclosure does not permanently prevent someone from getting another mortgage.
The waiting time depends on the type of mortgage program, the type of credit event, how the event was handled, and sometimes whether special circumstances apply. Borrowers in Chapter 13 bankruptcy may have mortgage options under certain loan programs if they meet requirements such as bankruptcy payment history and, if needed, court or trustee approval. Mortgage guidelines vary widely among FHA, VA, USDA, Fannie Mae, Freddie Mac, and non-QM programs, so borrowers should not rely on a single general waiting-period rule.
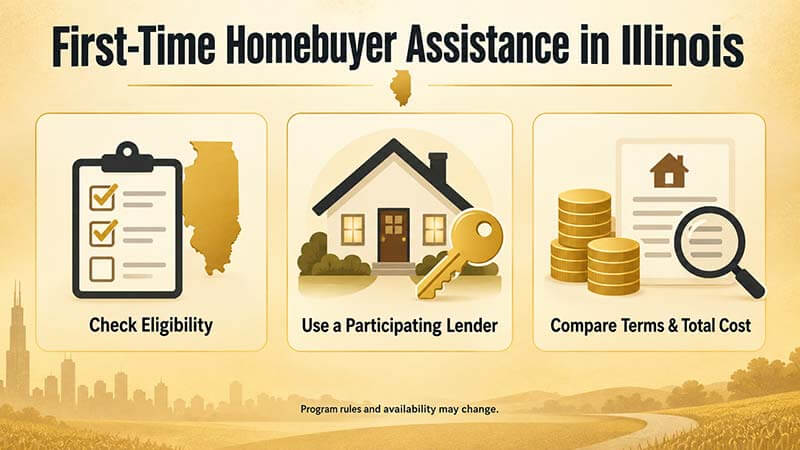
First-Time Homebuyer Assistance in Illinois
Oakbrook Terrace homebuyers may also want to research programs offered through the Illinois Housing Development Authority. IHDA administers homebuyer and down-payment-assistance programs for eligible Illinois borrowers. Program availability, assistance amounts, income limits, purchase price limits, lender participation, and other requirements may change.
Homebuyers should check the current rules directly with IHDA and find out whether their mortgage lender participates in the program. The program should also be compared with other financing options.
It can be helpful, but borrowers should understand the interest rate, second-mortgage terms, repayment rules, forgiveness options, and long-term costs before choosing a program.
Getting Pre-Approved Before Shopping for a Home
A good mortgage pre-approval is more than just getting a credit score and estimating income. A professional should check the borrower’s income documents, job, assets, credit report, regular debts, housing history, property type, down payment, and other important information. Complex files or caseComplex files or cases may need extra review before pre-approval is given. Finding problems before a purchase contract is signed is usually much easier than finding them days before closing.
Oakbrook Terrace Homebuyers Should Ask Their Mortgage Loan Officer
Before picking a mortgage lender, ask how the loan officer calculated your qualifying income, which program they suggest and why, if the lender has extra rules, what documents are still needed, and what could change the approval. A prior bankruptcy or foreclosure, recent late payments, self-employment, high debt ratios, student loans, multiple financed properties, or other complicated situations should be discussed before making an offer. Being upfront at the start of the mortgage process helps prevent surprises later on.
Contact Gustan Cho Associates About an Oakbrook Terrace Mortgage
Homebuyers and homeowners with questions about financing property in Oakbrook Terrace or elsewhere in Illinois can contact Gustan Cho Associates to discuss their individual mortgage scenario.
A mortgage consultation does not guarantee approval. Final approval depends on borrower qualifications, applicable mortgage guidelines, underwriting, property requirements, documentation, lender requirements, and all other loan conditions.
Gustan Cho Associates A DBA of Coast 2 Coast Mortgage Lending, LLC Company NMLS 376205
Phone: 800-900-8569 Email: gcho@gustancho.com For current company and individual licensing information, consumers should verify records through NMLS Consumer Access. Coast 2 Coast Mortgage Lending, LLC is headquartered in St. Augustine, Florida. Gustan Cho Associates also maintains a branch office in Salem, Wisconsin, NMLS 2885337.
Mortgage licensing and availability depend on the applicable state, company, branch, mortgage loan originator, and transaction. Consumers can independently verify current licensing through NMLS Consumer Access.
Gustan Cho Associates previously maintained operations in Oakbrook Terrace, Illinois. We no longer maintain an office there. This page remains available because homebuyers in Oakbrook Terrace and DuPage County need accurate information on mortgage qualification, loan programs, underwriting, and financing options.
Gustan Cho Associates | Our Team is Available 7 Days a Week
Open Hours
| 9 AM to 6 PM | Monday |
| 9 AM to 6 PM | Tuesday |
| 9 AM to 6 PM | Wednesday |
| 9 AM to 6 PM | Thursday |
| 9 AM to 6 PM | Friday |
| 9 AM to 5:30 PM | Saturday |
| 9 AM to 3:00 PM | Sunday |
Frequently Asked Questions About Oakbrook Terrace Mortgages
Do I Need to Use a Mortgage Lender Located in Oakbrook Terrace?
No. Mortgage lending is usually done electronically and remotely. The important thing is whether the mortgage company and loan officer are properly licensed or authorized for the transaction and whether the lender offers a loan program that fits the borrower.
Does Gustan Cho Associates Have an Office in Oakbrook Terrace?
No. Gustan Cho Associates no longer maintains an office in Oakbrook Terrace, Illinois. Gustan Cho Associates operates as a DBA of Coast 2 Coast Mortgage Lending, LLC, NMLS 376205.
Can I Get an FHA Loan to Buy a Home in Oakbrook Terrace?
Potentially. FHA financing is available for eligible borrowers and eligible properties when FHA and lender requirements are met. For 2026, HUD lists the one-unit FHA loan limit for DuPage County at $541,287. Loan limits are updated annually.
What is the Conventional Loan Limit in Oakbrook Terrace?
Oakbrook Terrace is in DuPage County. For 2026, FHFA lists the one-unit conforming loan limit for DuPage County at $832,750. Amounts above the applicable conforming limit may require jumbo or another financing program.
Can I Qualify for a Mortgage After Another Lender Denied Me?
Possibly. A prior denial does not automatically mean another mortgage program will work. The first step is to determine the specific reason for the denial. Some denials involve mandatory program guidelines, while others involve lender overlays, income calculations, documentation issues, or a loan program that did not fit the borrower’s circumstances.
Can Self-Employed Borrowers Get Mortgages in Oakbrook Terrace?
Yes, if they meet the loan program’s rules. Traditional mortgages usually use documented qualifying income. Some non-QM programs may review bank statements, assets, business cash flow, or other permitted documents.
