
VA Refinance Guidelines Quick Answer: VA home loan requirements include qualifying military service or surviving-spouse eligibility, a Certificate of Eligibility, satisfactory credit, sufficient qualifying income, and a home you intend to occupy. Lenders also review debts, residual income, available entitlement, and the property. Eligible buyers may purchase with no down payment and no monthly mortgage insurance, but a COE alone does not guarantee approval. Lenders can apply additional requirements beyond VA standards.
Which VA Refinance Fits Your Goal?
Start with two questions: What type of mortgage do you have, and what do you want the new loan to accomplish? These programs have different qualification and cost requirements.
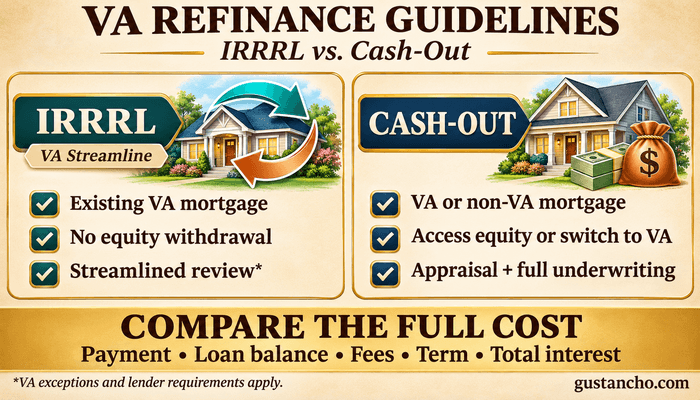
| Feature | VA IRRRL | VA cash-out refinance |
|---|---|---|
| Existing mortgage | Must be VA-backed | Can replace an eligible VA or non-VA mortgage |
| Main purpose | Improve the terms of an existing VA loan | Access equity, replace a non-VA loan, or change terms through full underwriting |
| Equity withdrawal | Cannot be used to withdraw home equity | May provide cash after required payoffs and costs |
| Appraisal | Generally not required by VA; exceptions or lender requirements can apply | VA appraisal required |
| Credit and income review | Usually streamlined; additional review may be required | Full underwriting |
| Occupancy | Certify current or previous occupancy | Must meet primary-residence occupancy requirements |
| Funding fee, unless exempt | 0.50% | 2.15% for first use; 3.30% for subsequent use |
| Monthly mortgage insurance | Not required | Not required |
An IRRRL is also called a VA streamline refinance. The cash-out program’s name can be confusing: receiving cash is not required when an eligible borrower uses it to replace a non-VA mortgage. For service eligibility and general borrower qualification, see our separate VA home loan requirements guide.
When Does an IRRRL Make Sense?
An IRRRL is worth considering if you already have a VA-backed mortgage and want better loan terms without taking out equity.
Common goals include reducing borrowing costs or moving from an adjustable-rate mortgage to a fixed rate. A fixed-to-fixed IRRRL generally requires a rate reduction of at least 0.50 percentage point. An ARM-to-fixed transaction may qualify without a lower interest rate.
The lower rate is only part of the decision. Adding fees to the balance or restarting a longer term can reduce the value of the refinance. VA generally does not require a new appraisal or a full credit-underwriting package for an IRRRL. However, VA exceptions and lender requirements can trigger additional review. “Streamline” does not mean automatic approval. The VA’s IRRRL overview explains the program’s basic purpose and occupancy rules.
When Should You Consider a VA Cash-Out Refinance?
A cash-out refinance may fit when you need equity proceeds or want to replace a non-VA mortgage with a VA-backed loan. For example, an eligible homeowner with an FHA or conventional mortgage may consider this route even without receiving cash. Removing monthly mortgage insurance can be a benefit, but the new rate, funding fee, closing costs, and repayment term must also be compared. This route requires a VA appraisal and full qualification. Ask the lender to assess the transaction before treating estimated equity as money available to spend. For loan-to-value limits, proceeds calculations, classifications, seasoning details, and document requirements, use our VA cash-out refinance guide.
What Timing and Borrower-Benefit Rules Apply?
You cannot assume a refinance is available immediately after obtaining a mortgage. For an IRRRL, VA’s seasoning guidance generally requires:
- At least six consecutive monthly payments made.
- At least 210 days between the existing loan’s first payment due date and the new loan’s closing.
The starting point is not simply the date you bought the home. Ask the lender to calculate your earliest eligible closing date based on your payment record. IRRRLs also have rate-reduction, fee-recoupment, and disclosure requirements. When principal and interest decrease, covered refinancing costs must generally be recouped within 36 months. Certain items, including the funding fee and escrow amounts, are excluded from that statutory calculation. If the IRRRL’s principal-and-interest payment stays the same or increases, the borrower generally cannot incur costs subject to that recoupment rule. Cash-out transactions have their own benefit and seasoning rules. The requirements are not identical for every VA-to-VA and non-VA-to-VA transaction.
How Do You Compare the Real Cost of Refinancing?
Request written offers using comparable loan amounts, terms, and rate-lock periods. Then compare each offer with the mortgage you already have.
| Figure to review | Why it matters |
|---|---|
| New loan balance | Shows how financed fees or equity withdrawals change your debt |
| Interest rate and APR | Helps you assess pricing alongside upfront charges |
| Principal-and-interest payment | Separates loan-payment changes from escrow changes |
| Remaining term versus new term | Reveals whether lower payments depend on extending repayment |
| Cash needed or cash received | Shows the immediate effect on your finances |
| Total costs and projected interest | Helps evaluate savings over your expected holding period |
The CFPB’s Loan Estimate explainer can help you identify these figures. A lower escrow payment does not necessarily mean the loan itself costs less. Compare property-tax and insurance assumptions as well as principal and interest. Also look closely at “no-closing-cost” offers. Costs may be added to the balance or covered by a lender credit associated with a higher rate. Either arrangement changes what you pay. The funding fee can also affect the comparison. For exemption categories, complete fee charts, payment options, and refund rules, see Understanding the VA Funding Fee.
How Can You Estimate Your Break-Even Point?
A simple planning calculation divides your nonrefundable refinancing costs by the monthly savings. Suppose you pay $4,800 in upfront refinancing costs and reduce principal and interest by $200 per month: $4,800 ÷ $200 = 24 months
In this simplified example, it takes two years of payment savings to recover those costs. Selling or refinancing again sooner could prevent you from reaching that point.
This personal budgeting estimate is different from the lender’s required VA recoupment calculation. It also does not capture all the effects of a changed balance or repayment term. Ask for a comparison over the period you expect to keep the loan. If you have 18 years remaining and replace it with a 30-year mortgage, the lower payment may come with more years of interest.
Three Examples of How to Choose
These are illustrative situations, not loan approvals or current rate quotes.
Existing VA Loan With No Need for Cash
A homeowner wants to reduce the cost of an existing VA mortgage and does not need equity proceeds. An IRRRL is a logical starting point. The homeowner should compare the savings, financed fees, new term, and break-even period. A full cash-out refinance may add requirements without serving an additional goal.
FHA Mortgage With a Goal of Moving to VA Financing
An eligible veteran has an FHA mortgage and wants to compare VA financing. An IRRRL cannot replace the FHA loan. A VA cash-out refinance may be an option even if the homeowner receives no cash. The comparison should weigh mortgage-insurance savings against the new rate, fees, balance, and term.
Low-Rate VA Mortgage With a Need for Renovation Funds
A homeowner wants renovation money but already has an attractive first-mortgage rate. An IRRRL cannot provide an equity withdrawal. A cash-out refinance may provide funds, but it also replaces the existing mortgage. Compare that result with keeping the first mortgage and using a suitable second-lien option. Review combined payments, fees, rate changes, and total borrowing costs.
How Should You Start Comparing VA Refinance Offers?
- Review the current loan. Get the balance, the note rate, the payment, the remaining term, and any second mortgage info.
- Define the goal. Are you after payment relief? Rate stability? Equity proceeds? A change from non-VA financing?
- Request comparable offers. Find out what VA loan options are available and how their costs and terms stack up against the cost and terms of your current mortgage.
- Confirm the requirements. Ask the lender to confirm timing, borrower benefit, occupancy, fee status, and any other underwriting conditions.
- Review the final figures. Compare the Closing Disclosure with the latest estimate and resolve unexpected changes before signing.
Gustan Cho Associates can help homeowners review their current mortgage and compare available VA refinance options. A useful starting point is a clear goal and an accurate estimate, rather than a promised payment reduction.
Frequently Asked Questions About VA Refinance Guidelines
Do You Have to Refinance With Your Current Mortgage Company?
No. You can apply with another lender that offers the appropriate VA refinance program. Your current servicer does not have exclusive rights to the refinance. Compare written offers and ask each lender about its requirements.
Can You Get an IRRRL if You Have a Home Equity Loan or HELOC?
It may be possible, but the second-lien holder generally must agree to remain behind the new VA first mortgage. An IRRRL cannot be used to pay off that separate debt. Discuss the second lien early because its treatment can affect the transaction.
Does an Escrow Refund Count as Cash-Out Proceeds?
An unused escrow refund is different from withdrawing home equity. Receiving a refund associated with the old loan does not, by itself, turn an IRRRL into a cash-out refinance. Ask the settlement provider to distinguish refunds, adjustments, and loan proceeds.
Should You Keep Making Mortgage Payments During the Refinance?
Yes. Continue following your current loan’s payment requirements until the servicer confirms payoff. Do not assume an advertised opportunity to “skip payments” means interest or other obligations disappear. Confirm payoff timing and the new loan’s first payment date.
How Long Does a VA Refinance Take?
There is no single closing timeline for every file. The lender’s review, required appraisal, title work, second liens, and document completeness can affect timing. Ask for a realistic schedule that also accounts for the loan’s earliest eligible closing date.
Final Thoughts on VA Refinance Guidelines
VA refinance guidelines show you which options you have. Deciding if refinancing makes sense comes down to looking at your overall financial outcome. Pick the option that matches your mortgage and your goals. Compare the costs, your remaining equity, your monthly payments, and how long it will take to pay off the loan. A lower payment helps only if you know why it’s lower and what you might give up for it.
This article about “VA Refinance Guidelines: IRRRL vs. Cash-Out Options” was updated on October 30th, 2026.
